
Introduction
AI infrastructure is often discussed as a single asset class. Its physical and financial components behave differently. Power assets are regulated, location-specific and long-lived. Data-centre facilities are specialised real assets whose value depends on power density, connectivity, cooling and access. Computing equipment is movable and identifiable, yet it can depreciate rapidly as new processors, networking standards and workload requirements emerge. Customer contracts can create high revenue visibility while concentrating repayment on a small number of technology counterparties.
The financing market has begun to reflect these differences. Public filings describe facilities secured by contractual cash flows and infrastructure assets, GPU-backed delayed-draw loans, customer-supported developments and project-level structures [34-43]. CoreWeave reported that its delayed-draw term facilities are constrained by the purchase price of eligible computing assets and secured by the relevant subsidiaries and assets [34-35]. A 2026 filing described a publicly syndicated HPC-backed delayed-draw facility aligned with customer deployments and the useful life of the GPU infrastructure [36]. These examples are transaction-specific. They show why a lender must define the financed perimeter, eligible assets and repayment source precisely.
Demand growth provides context for the capital need. The IEA estimated global data-centre electricity consumption at approximately 415 TWh in 2024 and projected substantial growth through 2030 [1-4]. The same evidence shows that local power constraints, technology efficiency and workload intensity can alter the path materially. A broad demand forecast does not resolve the credit question: which asset, contract and cash flow repays each lender if delivery is delayed or technology changes?
This paper provides a transaction framework for sponsors, banks, private-credit funds, infrastructure investors, equipment financiers and customers. It is for information only and does not constitute legal, tax, accounting, regulatory, engineering or investment advice. Every project requires current specialist review of its contracts, assets, jurisdiction and counterparties.
1 Decompose the AI infrastructure system into financeable perimeters
The first task is to replace a consolidated project label with an asset and obligation map. The map should identify five financing perimeters: power and energy infrastructure; land, shell and mechanical systems; computing equipment; customer receivables and deposits; and corporate obligations. Each perimeter should have an owner, borrower, operating dependency, eligible-cost definition, economic life and recovery route.
Power assets include generation, transmission contributions, substations, grid connection, storage and backup systems. Their value depends on permits, dispatch rights, fuel or supply contracts, interconnection and the ability to serve the financed load. Facility assets include land rights, buildings, cooling, electrical distribution, fibre, water and security. Their value depends on location, technical specification and the availability of power and customers. Compute assets include GPUs, CPUs, networking, storage and associated racks. Their value depends on title, serial identification, configuration, warranty, software compatibility and resale demand.
Customer cash should be mapped independently. A take-or-pay contract can support asset-level financing only when the obligor, term, payment obligation, acceptance test, termination rights, set-off, service credits and credit support are understood. A deposit can fund construction while also creating a refund obligation. Accounts receivable may be financeable after acceptance and invoice issuance. None of these should be counted twice across equipment, facility and corporate debt.
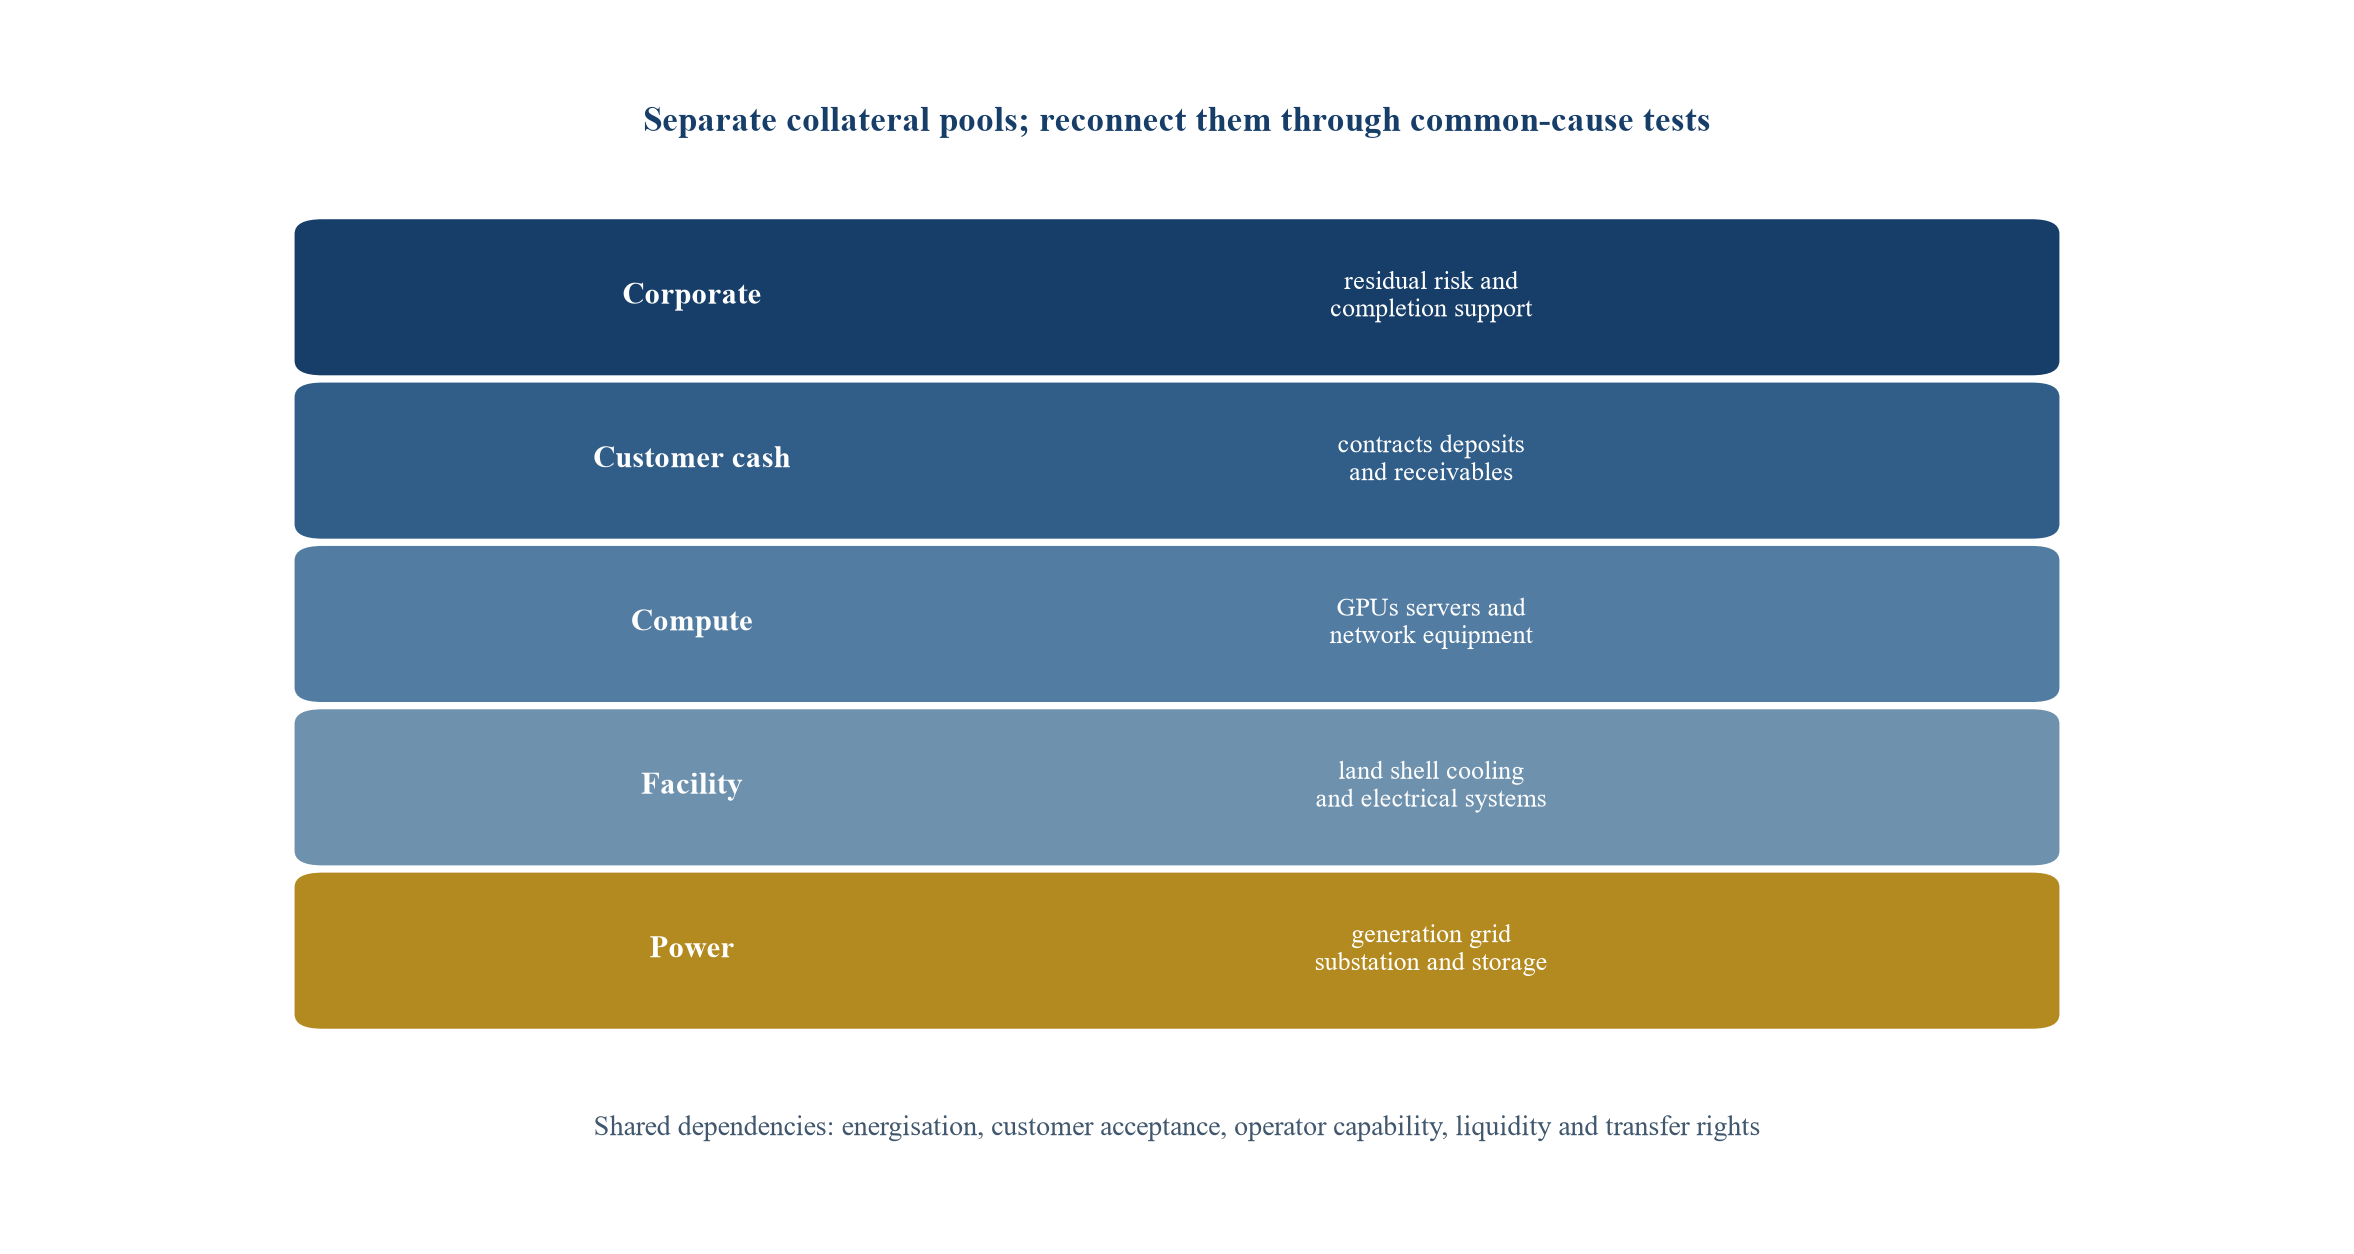
Proposed financing map; legal rights and economic dependence require project-specific evidence.
The perimeter map should reconcile to legal entities and contracts. If the power company, property owner and compute operator are separate, the map should show leases, service agreements, security, direct agreements and cross-defaults. Separation can protect lenders from unrelated risk. It can also create dependency on intercompany contracts that are weaker than external agreements. The transaction should be tested as one operating system and several recovery pools.
| Perimeter | Primary repayment source | Typical eligible collateral | Core underwriting question |
|---|---|---|---|
| power and energy | capacity or energy charges allocated to the project | generation, interconnection rights, substations and storage | can the assets provide dependable power through the debt term? |
| land and facility | rent, capacity and facility service payments | land rights, shell, cooling, electrical and network systems | can the facility operate or be re-let after customer or operator failure? |
| compute equipment | contracted compute payments and equipment proceeds | identified GPUs, servers, storage and networking | does debt decline before economic obsolescence and contract expiry? |
| receivables | accepted invoices from eligible customers | controlled receivables and contract rights | are amounts earned, undisputed, concentrated and collectible? |
| corporate | residual enterprise cash and equity value | shares, unrestricted assets and guarantees | can the enterprise absorb completion, interface and refinancing risk? |
Proposed underwriting structure; conclusions depend on executed documents and asset evidence.
2 Build an asset-life and contract-life matrix
Debt tenor should follow the shortest reliable life among the financed asset, customer cash flow and essential operating right. A long-lived substation does not justify long-tenor debt if its revenue depends on a compute contract that expires in five years. A multi-year customer commitment does not justify a high equipment advance rate if the hardware must be replaced earlier to meet performance obligations. A facility can remain useful after a chip cycle, provided its power density, cooling and connectivity can support replacement equipment.
The matrix should state legal maturity, scheduled amortisation, expected asset life, contract term, renewal rights, technology refresh date and terminal value. Each item should be supported by a named evidence source. Useful life for accounting can differ from economic value for credit. Equipment resale value should be based on identifiable configuration, removal cost, software and warranty transfer, market depth and time to sale. Property value should recognise site-specific power and re-letting constraints.
Amortisation should create a margin before the first relevant expiry. Equipment debt should pay down ahead of the supported economic life and customer term. Facility debt can extend further if independent re-letting value is evidenced. Power debt can be longest where contracted capacity, licences and continued-service rights are durable. Balloon exposure should be tied to a credible refinancing or disposal path rather than a terminal-value assumption alone.
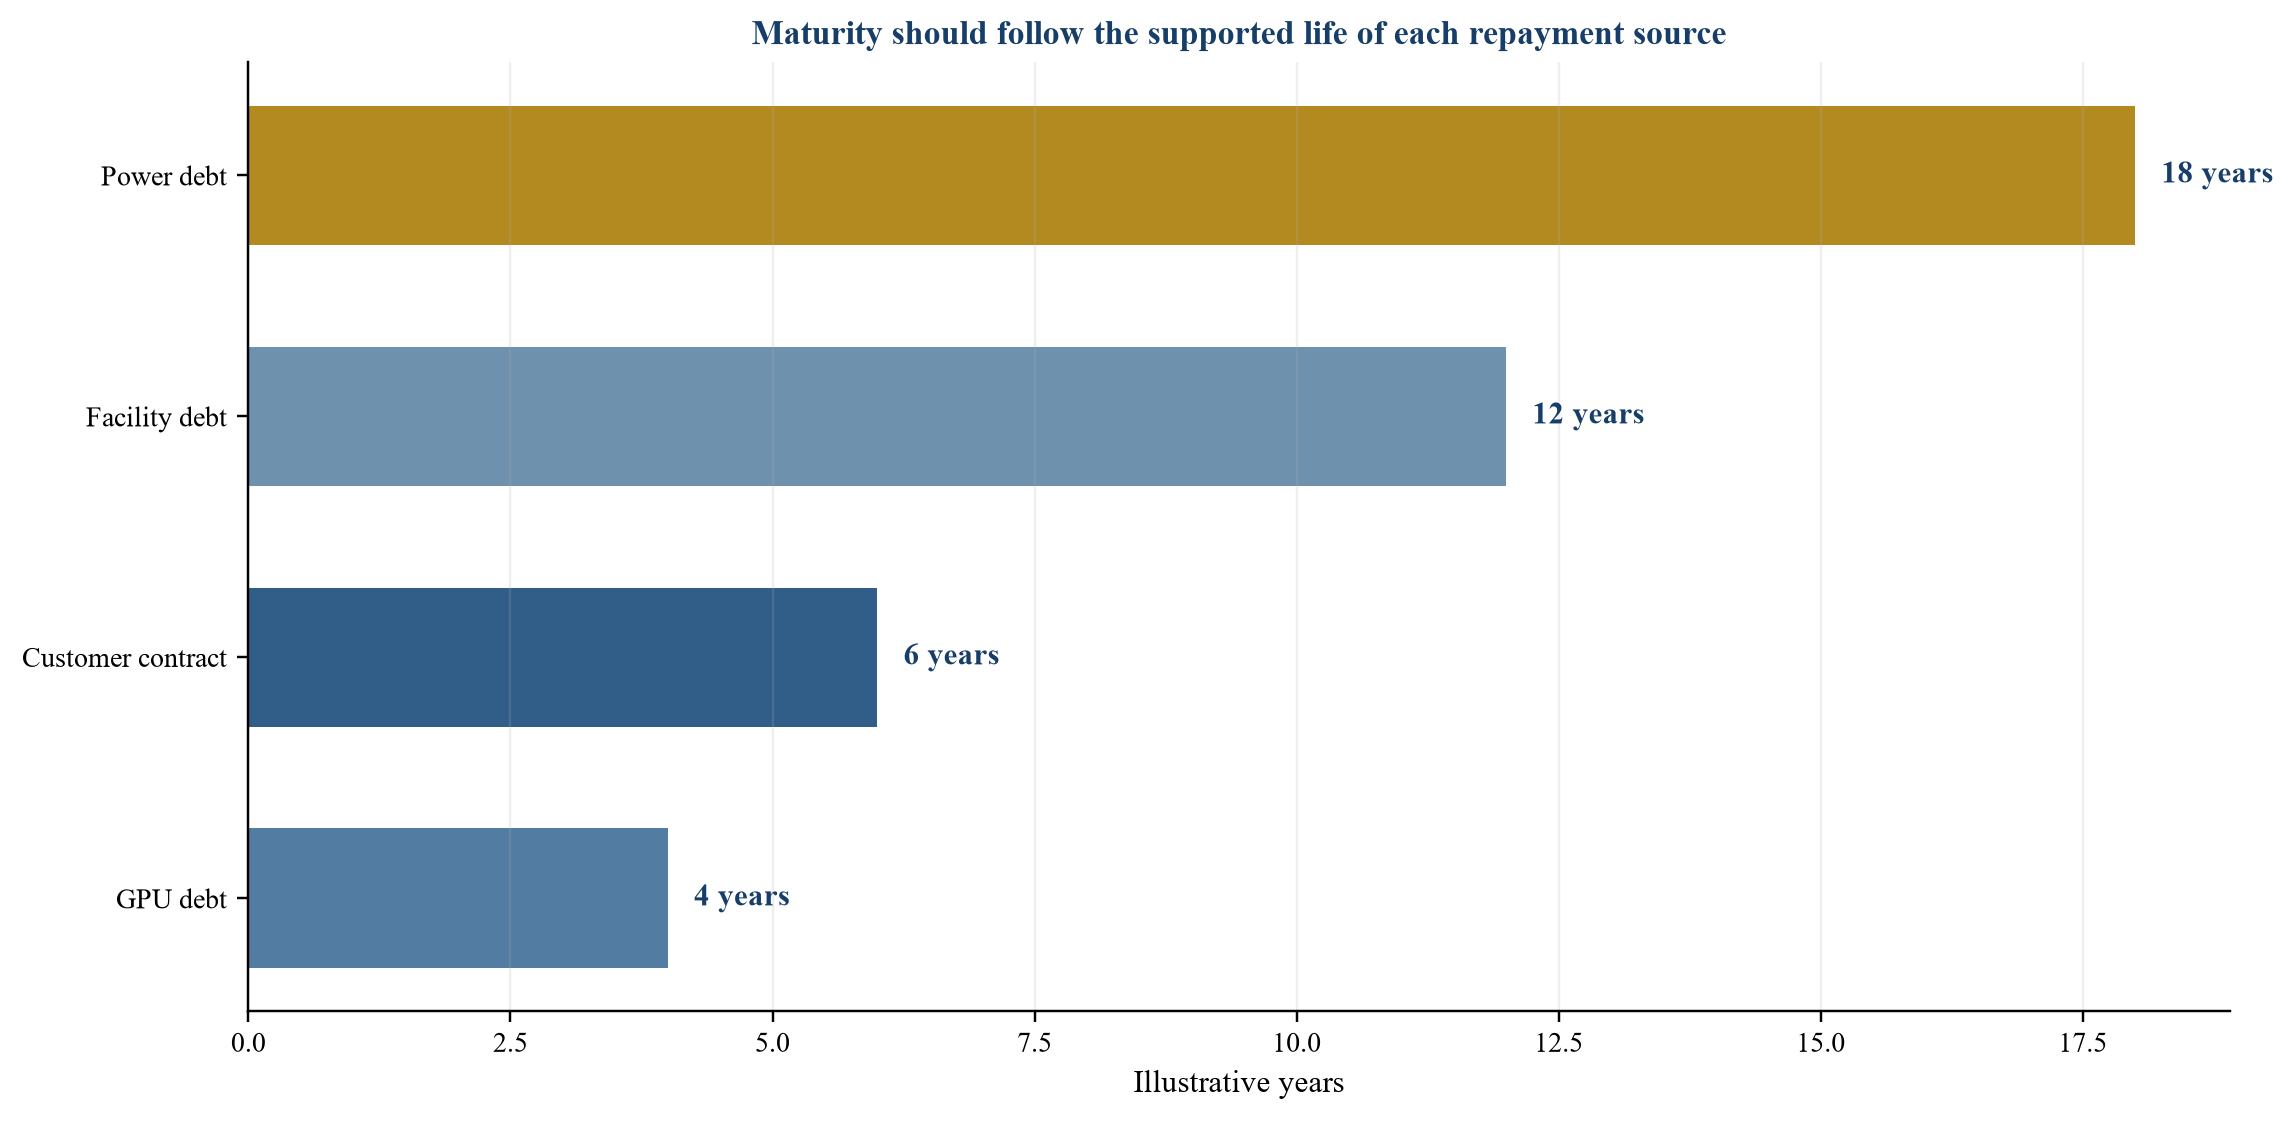
Years are management assumptions used to demonstrate tenor discipline.
The matrix should be refreshed when a contract is amended, equipment is substituted, a new generation source is added or technical standards change. A maturity that was prudent at closing can become exposed after a customer reduction or delayed refresh. Mandatory prepayment, cash sweep and reappraisal mechanisms should respond before the residual risk becomes concentrated at maturity.
3 Underwrite power debt as infrastructure credit
Power debt should be underwritten from the rights and assets that make electricity dependable for the financed load. Relevant evidence can include interconnection agreements, network-upgrade obligations, generation or supply contracts, fuel arrangements, permits, dispatch rights, curtailment, redundancy, commissioning and operating performance. Requested capacity, a development study or a non-binding utility indication should remain outside the base case until the applicable conditions are satisfied.
The revenue model should identify whether power cost is passed through, included in a fixed service price or managed through a collar. It should reconcile generation output, grid imports, losses, demand charges, network charges, storage and customer reimbursement. A pass-through clause can reduce commodity exposure while leaving timing, volume, basis and counterparty risk. Minimum demand charges can continue during a customer acceptance delay.
Power security should cover the assets and rights needed to continue service. A mortgage over a substation is insufficient if land access, fuel, dispatch software or the grid contract cannot transfer. Direct agreements should address notice, cure, step-in and transfer where legally available. The lender should understand how the power system operates after a default of the compute borrower or customer.
Advance rates should reflect construction status, revenue certainty, counterparty credit and transferability. Long-tenor debt may be appropriate after commissioning when power revenues or allocated capacity charges are durable. Construction debt should retain cost-to-complete protection, contingency and sponsor support. Debt sized from an ultimate campus load should exclude later capacity that lacks dependable rights and eligible customer demand.
4 Finance facilities from powered and transferable real-estate value
Facility debt should be based on a site that can deliver the contracted product and retain alternative-use value. The appraisal should distinguish land, shell, mechanical and electrical systems, cooling, fibre, water, security and tenant-specific improvements. Power density, redundancy and cooling design can determine whether the building can serve another customer or technology generation.
The lender should separate powered-shell value from fully fitted compute value. A building without dependable power can have materially different recovery prospects from a commissioned facility. Customer-specific improvements may have limited reuse. Shared infrastructure should be allocated transparently so that several borrowers do not each claim the same substation, road, fibre route or contingency.
Lease or service revenue should be tested for acceptance, commencement, escalation, operating-cost recovery, termination, restoration and assignment. Customer contributions should be tracked to the relevant assets and obligations. If a contribution is refundable after a delivery failure, it is a liability and liquidity exposure. If it reduces future rent, it affects the debt-service profile.
Facility debt can carry a longer tenor than compute debt when the building can be re-let and refreshed. The credit case should include time and capital required to replace a customer, modify cooling or electrical systems and install new equipment. Re-letting should not be assumed to occur immediately after a specialised tenant default.
5 Size GPU and equipment debt from identifiable assets and supported cash
Equipment finance should begin with a serial-level asset register. The register should record manufacturer, model, configuration, purchase price, delivery, title, location, warranty, software dependency, customer allocation, insurance and expected refresh date. Draws should follow invoice, delivery, inspection, title and deployment evidence. Substitutions should preserve or improve collateral quality and should remain subject to lender control.
The borrowing base should apply the lower of eligible cost and conservative market value, then apply concentration, age, configuration and contract haircuts. A processor can be technically functional and economically impaired if newer systems deliver materially better performance per unit of power or if the configuration has a thin resale market. Removal, transport, reconfiguration, software and recommissioning costs should reduce recovery value.
Customer cash can support higher advance rates when contracts are enforceable, take-or-pay, long enough and backed by creditworthy obligors. The lender should confirm that acceptance has occurred, performance standards are achievable and service credits do not create an open-ended deduction. A contract tied to specific equipment can improve visibility while reducing redeployment flexibility.
Scheduled amortisation should be front-loaded relative to expected depreciation. A cash sweep should respond to excess receipts, contract shortening, customer downgrade, warranty expiry or appraisal decline. Equipment debt should avoid a large balloon that assumes a deep resale market at the end of the technology cycle.
| Debt silo | Eligible-cost base | Illustrative advance rate | Illustrative tenor | Primary control |
|---|---|---|---|---|
| power and interconnection | USD 540m | 66.7% | 18 years | dependable capacity, commissioning and continued-service rights |
| land and facility | USD 760m | 59.9% | 12 years | powered-shell completion, appraisal and transferable customer cash |
| compute equipment | USD 880m | 60.0% | 4 years | serial register, eligible contracts, appraisal and rapid amortisation |
| fees, reserves and working capital | USD 220m | 0.0% | equity funded | controlled accounts and defined reserve purposes |
| total project | USD 2,400m | 56.0% blended | mixed | lesser-of silo limits and consolidated cap |
Advance rates and tenors are management assumptions for demonstration only.
6 Allocate customer cash once across the stack
One customer payment may economically support power, facility and compute obligations. The financing documents should allocate that cash through a controlled waterfall without allowing each lender to size debt from the gross contract amount. The allocation can be explicit in the customer contract, embedded in intercompany service charges or established through a lender-agreed model. It should reconcile to invoices, accounting and controlled-account receipts.
The allocation ledger should start with gross customer receipts and deduct taxes, service credits and essential operating costs. It should then assign power charges, facility charges and compute charges according to enforceable documents. Residual cash can support corporate debt or distributions after reserves and covenants. The ledger should show which lender has first claim, which costs can be paid before debt service and how shortfalls are shared.
Customer concentration should be measured on several bases: revenue, backlog, contracted megawatts, equipment allocation, receivables and debt service. A project with three contracts can still have one economic counterparty if affiliates, guarantees or termination rights converge. Concentration haircuts should apply consistently across the silos and again at consolidated level where the same default affects multiple facilities.
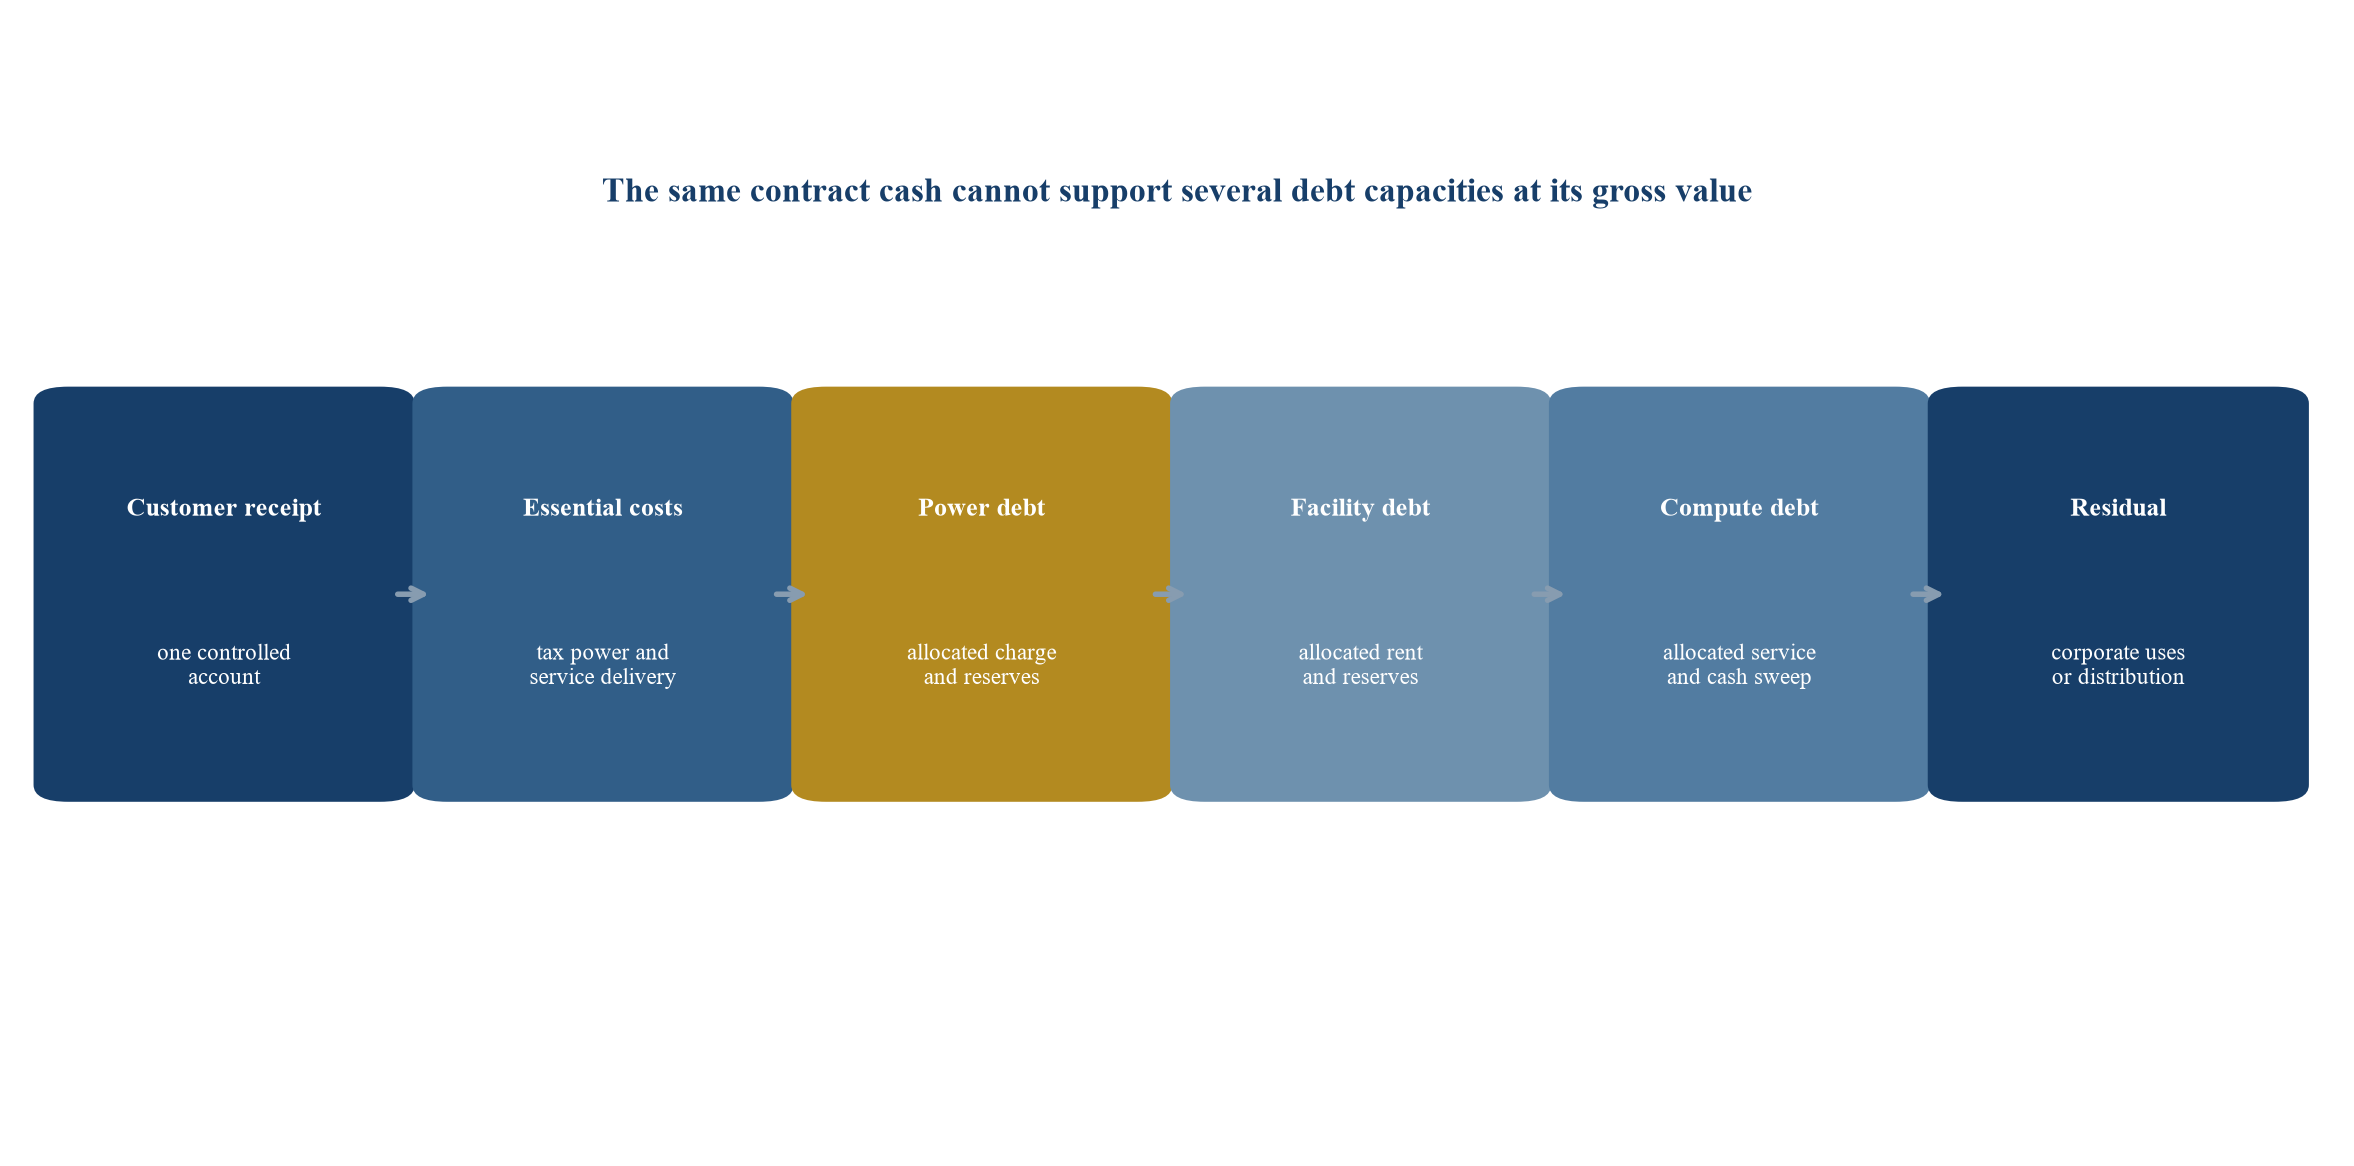
Proposed waterfall; priorities depend on executed finance and operating documents.
The model should contain an anti-double-counting schedule. Every dollar of customer cash should appear once as a source of debt service. Every asset should appear once in a collateral base unless intercreditor documents expressly recognise shared security. Guarantees, deposits, insurance and reserves should also be assigned to defined exposures. A sponsor guarantee should not be treated as funded liquidity until called and paid.
7 Model correlation across power, chips, facilities and customers
Separate legal silos do not create economic diversification by themselves. Several facilities can depend on one energisation date, construction contractor, customer acceptance test, software stack or operating team. The credit model should identify common causes and quantify their effect across all silos.
An energisation delay can postpone facility rent, prevent equipment acceptance and consume interest reserves. A customer termination can reduce compute revenue, weaken facility occupancy and remove the allocated power charge. A technology shift can reduce equipment value and require facility modifications. A cyber incident can interrupt customer service while leaving physical assets intact but cash unavailable.
The correlation matrix should score both probability linkage and loss linkage. A shared cause can be unlikely and still material because it impairs several repayment sources simultaneously. Stress tests should combine events with a credible relationship. Independent events can be combined separately to understand tail exposure without presenting them as a forecast.
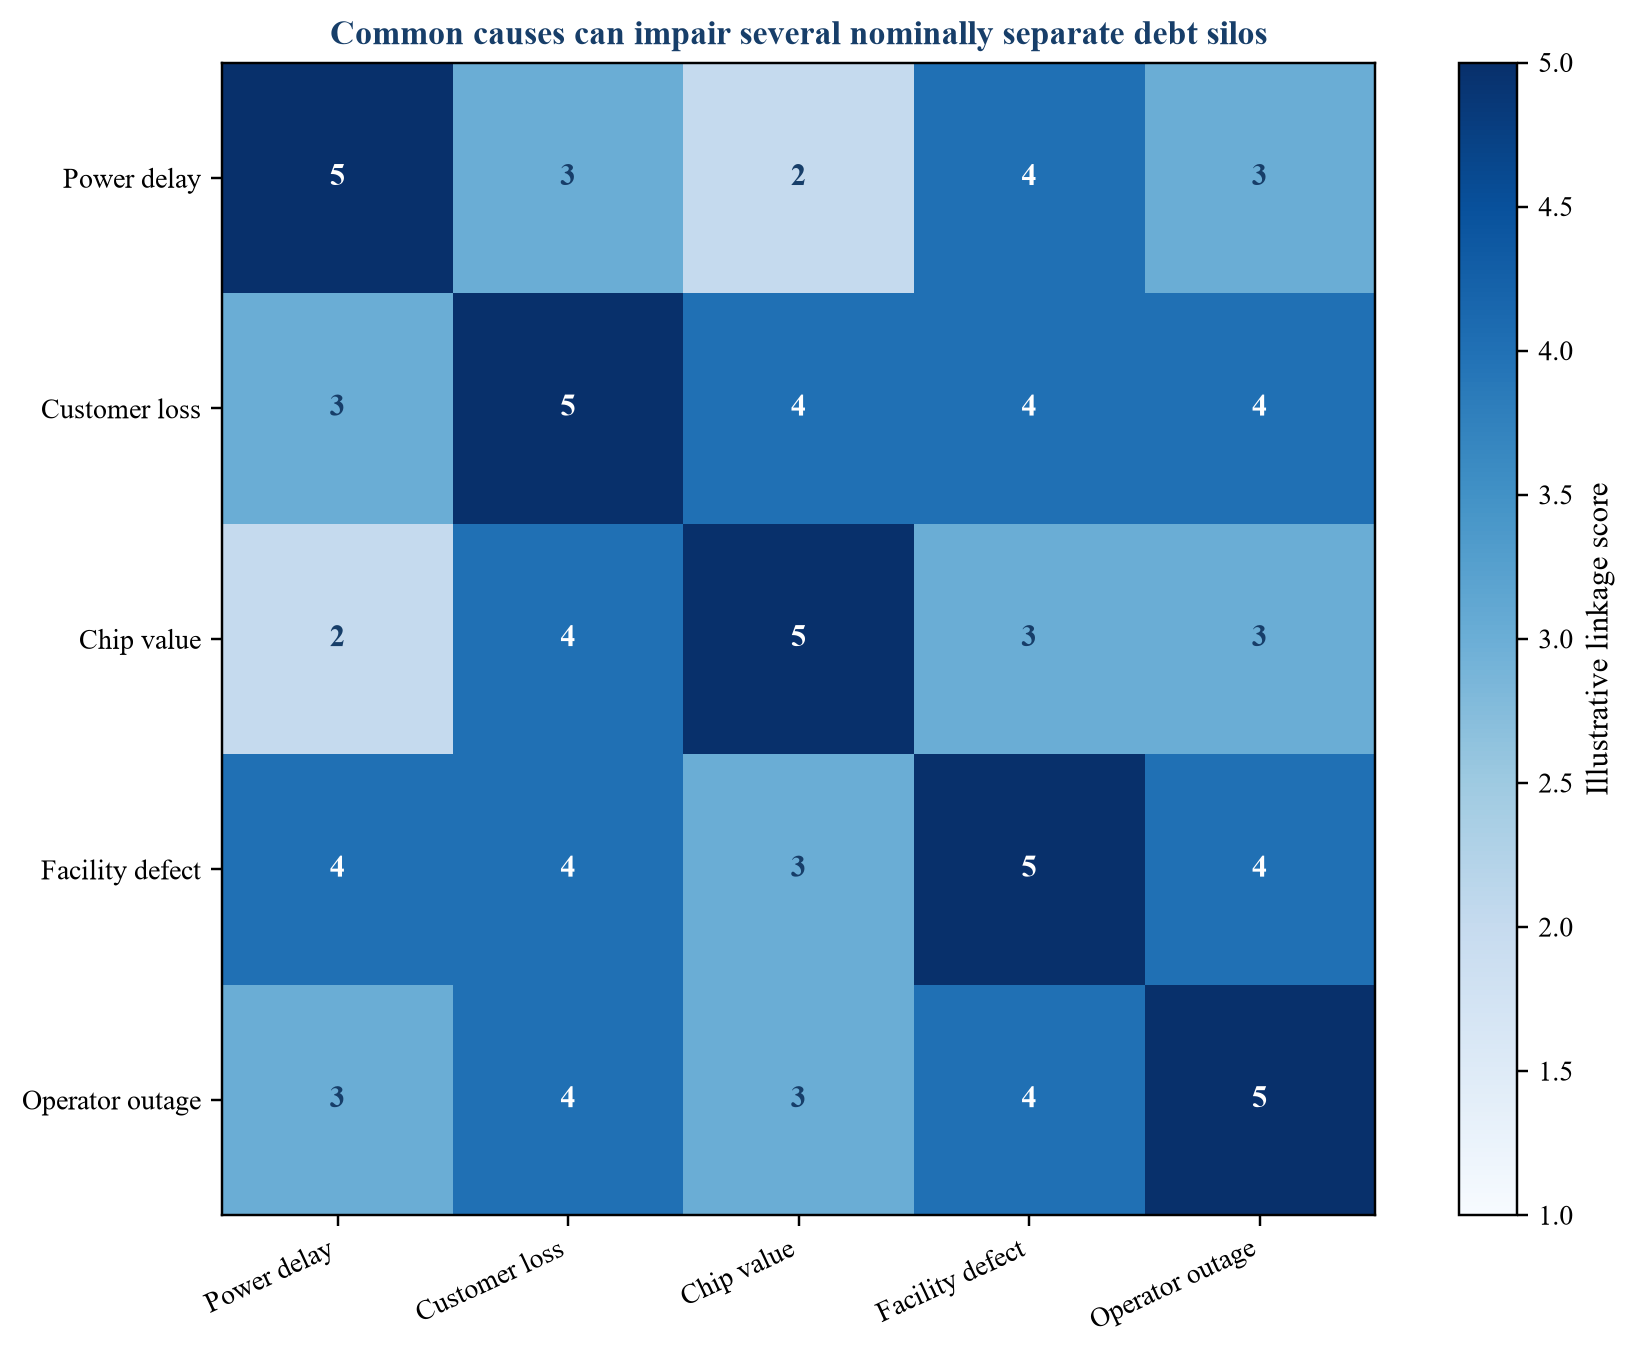
Scores are management assumptions on a one-to-five scale used to demonstrate the method.
Correlation should affect leverage, reserves and intercreditor terms. High shared dependence can justify a lower consolidated cap even when each silo passes its standalone test. It can also justify cross-entity information rights, coordinated draw stops and a common liquidity reserve. Cross-default should be calibrated carefully so that a contained issue does not destroy value unnecessarily while a system-wide event cannot be ignored.
| Common cause | Power debt effect | Facility debt effect | Compute debt effect | Consolidated response |
|---|---|---|---|---|
| energisation delay | capitalised interest and unavailable capacity charge | delayed completion and rent | idle equipment and delayed acceptance | stop draws, call support and extend reserves |
| anchor-customer loss | lower allocated power revenue | vacancy and re-letting cost | lost compute cash and weaker resale timing | haircut all affected bases and trap cash |
| technology change | possible change in load profile | retrofit and cooling cost | faster depreciation and refresh need | shorten equipment tenor and fund modification |
| contractor or interface failure | delayed commissioning | cost overrun and defects | deployment and warranty delay | apply integrated cost-to-complete test |
| cyber or operator outage | dispatch and control exposure | service interruption | customer credits and termination risk | preserve liquidity and enforce recovery plan |
Proposed stress design; project-specific probabilities and severities require evidence.
8 Design the intercreditor and security architecture
The legal architecture should reflect the physical system. Power, facility and equipment lenders may hold security over different assets while sharing customer cash, accounts, insurance proceeds or equity pledges. The intercreditor agreement should define priority, permitted payments, standstill, cure, enforcement, sale allocation and continued operation.
Each lender should know which assets it can control and which assets are essential but outside its collateral. Equipment lenders need access, removal and cooperation rights. Facility lenders need to protect the building from disruptive removal and may need equipment to preserve customer service during a sale. Power lenders need continued payment and access even if the compute operator defaults. Direct agreements can connect these rights to customers, utilities, landlords, operators and key vendors.
Enforcement should preserve enterprise value. Immediate equipment removal can destroy facility cash and customer continuity. An indefinite standstill can destroy equipment value as technology ages. The agreement should establish valuation, sale and substitution processes with time limits and minimum operating protections. Insurance proceeds should follow the loss and reinstatement decision rather than a broad priority rule alone.
Structural subordination should be explicit. Debt at a holding company depends on distributions from asset borrowers after operating costs, reserves and senior debt service. A corporate guarantee from an asset borrower can weaken ring-fencing and affect debt sizing. Restricted payments, intercompany charges and additional debt should be controlled across the group.
9 Apply the lesser-of silo tests and a consolidated debt cap
Standalone debt sizing is the first step. Power debt can be limited by eligible cost, dependable capacity cash and maximum leverage. Facility debt can be limited by cost, appraisal and supported rent. Equipment debt can be limited by eligible purchase price, conservative market value and contract cash. The project should then apply a consolidated cap based on total eligible cash, common-cause stress and minimum liquidity.
Management assumes total project uses of USD 2.40 billion. Management assumes USD 1.343 billion of debt before rounding: USD 360 million of power debt, USD 455 million of facility debt and USD 528 million of equipment debt. The balance comprises sponsor equity, customer contributions and reserves under the illustrative model. These are management assumptions and do not describe an identified financing.
The consolidated model should reconcile the three debt-service schedules to one customer cash allocation. It should test operating cost, power cost, acceptance timing, customer concentration, equipment depreciation, re-letting and refinancing. Debt capacity should equal the lowest result produced by asset-specific limits, allocated cash and consolidated downside constraints.
| Source | Amount | Principal use | Core availability control |
|---|---|---|---|
| power debt | 360 | generation, interconnection and substation assets | dependable capacity, certified cost and commissioning |
| facility debt | 455 | land, shell, cooling and electrical systems | powered-shell completion, appraisal and cost to complete |
| compute debt | 528 | eligible GPUs, servers and networking | serial assets, customer contracts and depreciation test |
| customer contributions | 240 | agreed capacity and customer-specific works | restricted use, milestones and refund treatment |
| sponsor equity and reserves | 817 | first-loss cost, fees, reserves and working capital | funded first or proportionately under agreed controls |
| total | 2,400 | complete and commission the integrated system | controlled sources equal approved uses |
All amounts are management assumptions in USD millions.
The model should include both silo and group distribution tests. A strong power borrower should not distribute cash that the integrated project needs to cure a facility delay when the structure relies on common sponsor support. At the same time, an equipment shortfall should not automatically consume protected power cash if separation and continued service can preserve value. The decision requires documented priorities and liquidity rules.
10 Use covenants, reserves and draw controls across the stack
The covenant package should monitor the physical and contractual variables that drive cash. Financial covenants alone can identify deterioration after the cause has emerged. Operating covenants can provide earlier warning through power, construction, acceptance, availability, customer credit and equipment measures.
Reserves should be assigned to defined risks. A debt-service reserve protects scheduled payments during temporary cash shortfalls. A completion reserve covers approved remaining cost and identified interface exposure. A major-maintenance reserve funds module work after operation begins. A customer-refund reserve protects restricted cash where delivery obligations remain outstanding. The model should prevent one reserve from being counted against several simultaneous risks.
| Control | Measurement | Early-warning trigger | Financing response |
|---|---|---|---|
| power readiness | dependable MW allocated to the financed stack | milestone slip or reduced entitlement | stop affected draws and update the integrated schedule |
| customer eligibility | allocated contract cash versus debt service | ratio below approved gate | reduce all affected borrowing bases and increase equity |
| eligible cost | certified direct cost and approved shared allocation | ineligible cost or unsupported change order | exclude cost and require sponsor funding |
| customer acceptance | accepted MW versus schedule | failed test or delayed decision | defer term conversion and require support |
| eligible cash | collected net receipts by contract | credit, dispute, amendment or concentration | haircut borrowing base and prepay |
| DSCR | historical and forward cash versus debt service | ratio below lock-up | block distributions and sweep cash |
| liquidity | unrestricted cash and dedicated reserves | reserve below required amount | sponsor cure or draw stop |
| remaining sufficiency | undrawn debt, committed equity and contingency versus cost to complete | sources fall below remaining uses | stop draw and call sponsor support |
| interface risk | open critical-path items and claims | unresolved item beyond latest safe date | independent review and funded contingency |
Proposed structure; thresholds require project-specific modelling and documentation.
Each borrowing base can recognise certified eligible cost during construction and allocated customer cash after delivery, acceptance, credit, performance, concentration and term haircuts. Advance rates can rise as completion and contracted occupancy improve, subject to asset-specific and consolidated leverage limits. A collateral pool should remain outside the base until it independently satisfies its eligibility test and is included in the anti-double-counting ledger.
Information rights should include schedules, contracts, customer credit, invoices, collections, generation, grid events, power cost, service levels, equipment, incidents, insurance and reserves. Definitions should be consistent across operating systems and finance documents. Independent verification should apply to measurements that govern draw, conversion, distribution or default.
11 Stress the integrated stack under correlated downside
Single-variable sensitivities can understate AI infrastructure credit risk. A customer delay can coincide with a facility cost overrun after power and equipment commitments have been made. Equipment can remain idle while interest, minimum power charges and facility costs continue. The downside model should combine events that share a plausible cause, customer or delivery date.
The first case should delay customer acceptance and calculate capitalised interest, customer remedies, minimum power cost and remaining contingency. The second should reduce eligible customer cash and equipment appraisal value. The third should apply a cost overrun to facility and power works. The fourth should combine delayed acceptance, lower equipment value, higher power cost and higher financing cost. Each case should show the effect on every debt silo and the consolidated liquidity position.
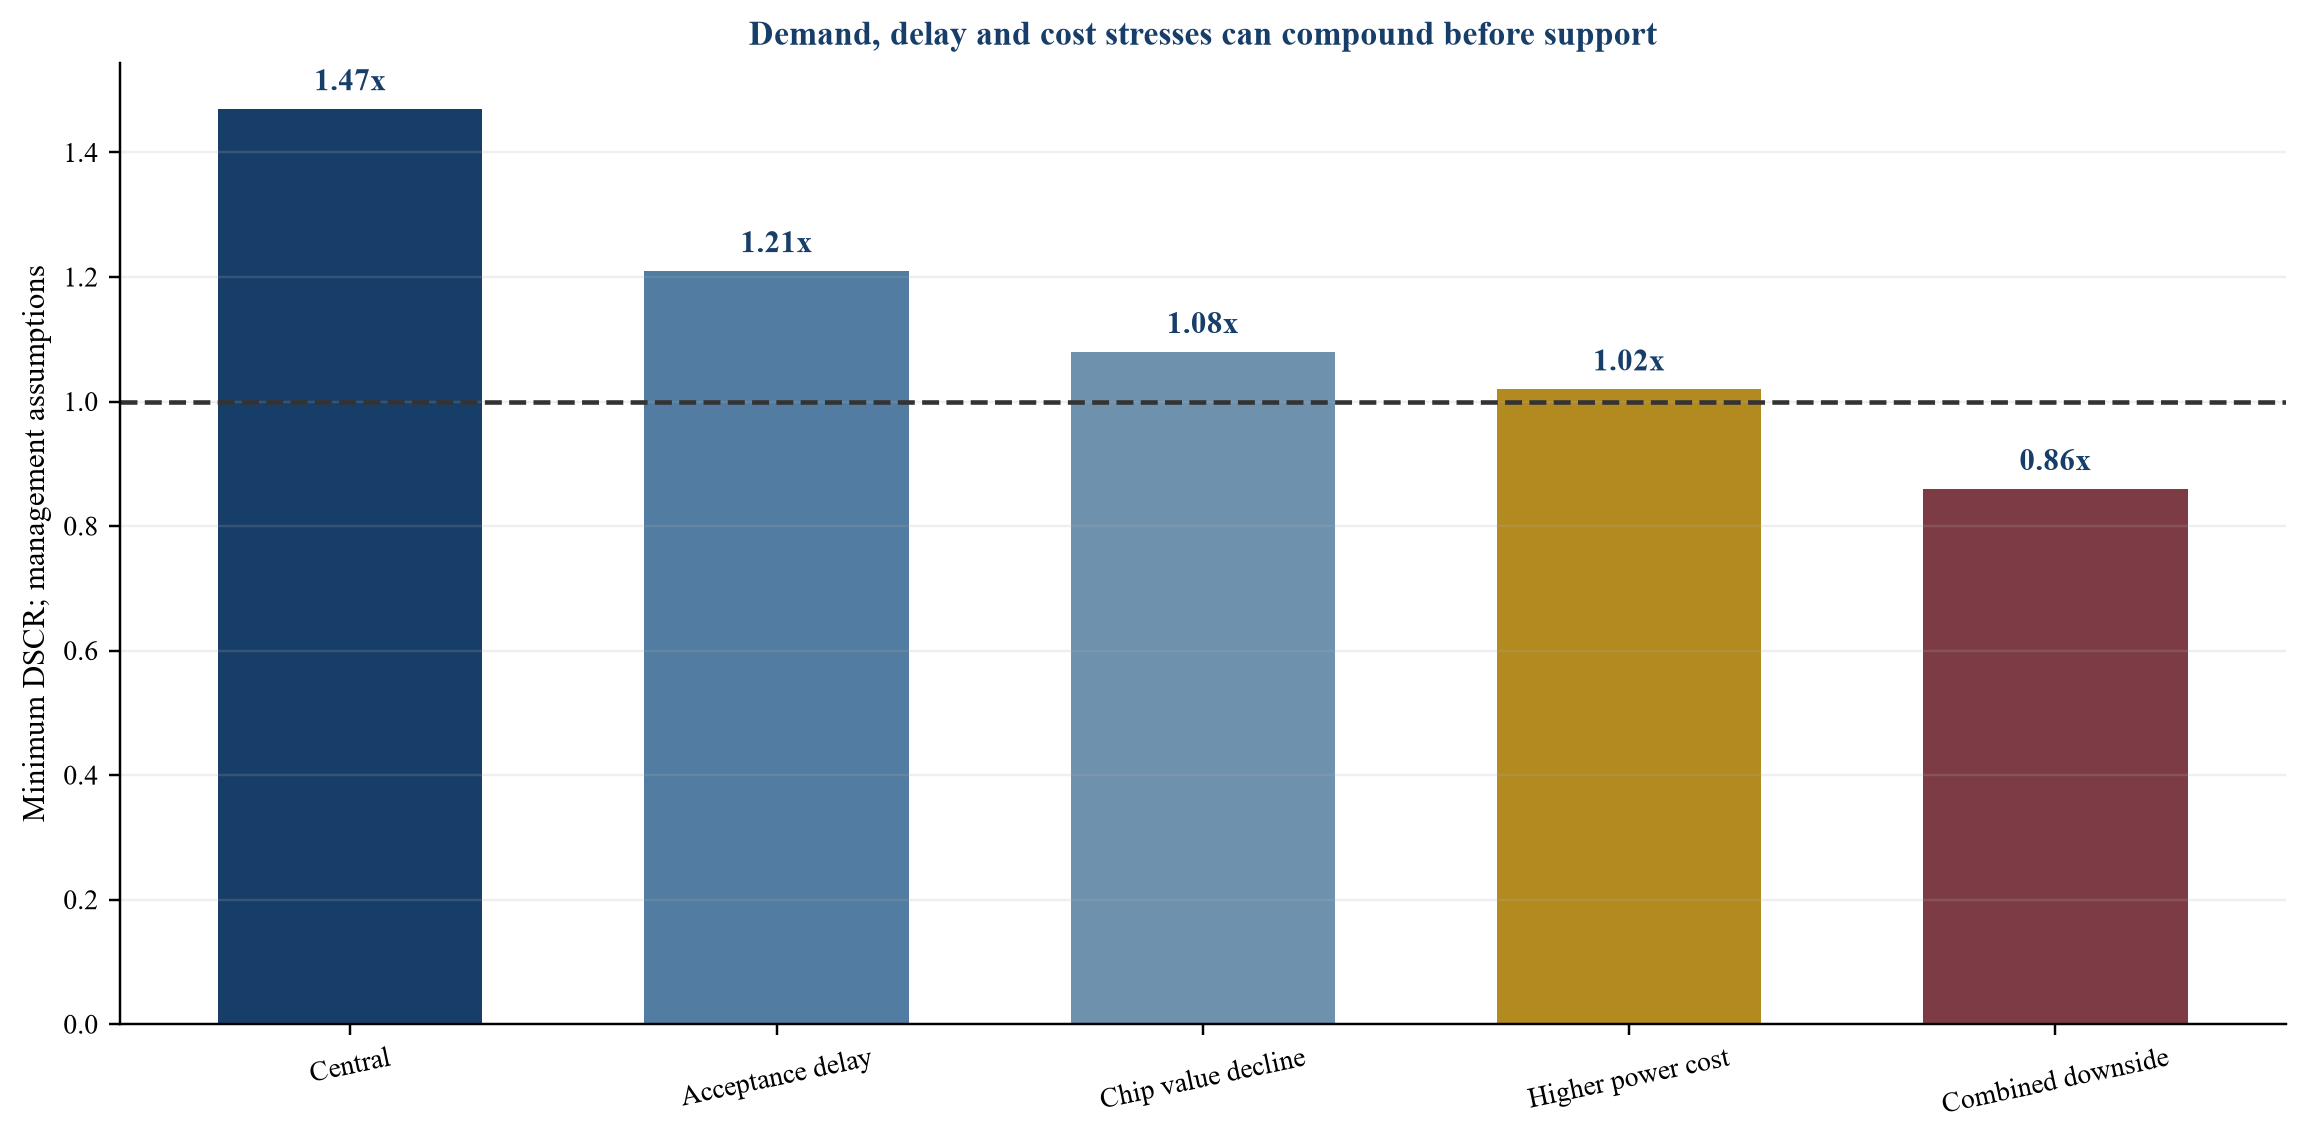
All ratios are management assumptions and do not describe an identified financing.
Each downside should state liquidity, cost to complete, covenant date, reserve use, support call, customer effect and recovery action. The model should identify the first binding constraint. A project can have positive long-term economics and fail because cash is unavailable during a delay. The liquidity bridge is therefore as important as the terminal valuation.
Stress actions should be executable. A draw stop protects uncommitted debt. Sponsor equity cures cost and delay where the sponsor has capacity and a binding obligation. Storage or grid optimisation can reduce operating cost within technical and contractual limits. Customer remedies can be negotiated only with consent. Asset sales and refinancing require time and market access. The credit case should not assume an action without authority, funding and lead time.
12 Align accounting, allocation and reporting with the credit stack
Accounting classifications should inform the model and remain separate from lender cash definitions. IFRS 15 requires identification of customer contracts, performance obligations, transaction price and the transfer of promised goods or services [44-45]. Variable consideration, service credits, modifications, prepayments and significant financing components can affect revenue timing. Revenue recognition does not establish cash availability under the financing waterfall.
Generation PPAs, campus leases, equipment facilities, guarantees and consolidation require review under applicable standards [44-48]. A dedicated asset or contract may create a lease or another accounting consequence. A special-purpose company can be consolidated by a sponsor or customer depending on control. The accounting conclusion should be documented without changing the underlying legal and credit analysis.
Tax can alter cash at several layers. The project should assess customs and import duties, value-added tax, withholding, property tax, fuel tax, transfer pricing, interest limitation, depreciation, incentives and loss use. Intercompany charges should be supported and consistent with the waterfall. Tax credits and incentives should enter the base case only after entitlement, timing and monetisation are supported.
Reporting should reconcile operations, contracts, accounting and cash. The project should bridge customer capacity to invoices, revenue, receivables and collections. It should bridge generation output and grid imports to power cost and customer reimbursement. It should bridge capital expenditure to assets, debt draws and remaining cost. Differences should be explained and carried into forecasts.
13 Integrate environmental and community obligations into credit eligibility
Power-intensive campuses can affect land, water, noise, emissions, transmission and local infrastructure. The project should identify applicable permits, assessments, consultation, mitigation, monitoring and reporting. General sustainability claims should not replace site-specific evidence.
The power strategy may combine renewables, natural gas, nuclear, storage and grid electricity. The IEA projects that renewables meet a substantial share of incremental data-centre demand while dispatchable sources remain important [1-4]. Contractual procurement and physical supply should be distinguished. Environmental attributes, grid mix, backup generation and onsite sources can produce different claims and risks.
Water and cooling should be assessed under expected and extreme conditions. The design should state source, quantity, treatment, discharge, redundancy and restrictions. Air cooling, liquid cooling and hybrid systems can change power and water profiles. Higher rack density can change both. The environmental model should use the actual design and location.
Lenders using the Equator Principles, IFC Performance Standards or related policies can require defined environmental and social processes [30-33,49]. The scope, category and obligations depend on the financing and project. Compliance cost, schedule and monitoring should be included in sources and uses. A permit or stakeholder delay can become a completion and liquidity risk.
14 Preserve continuity, transfer and refinancing options
Downside value depends on preserving the operating system. Lenders should understand whether generation contracts, grid service, land, permits, equipment, software, customer contracts, data and staff can remain available after default. Security over one entity may be insufficient when essential rights sit in another.
Direct agreements can give lenders notice, cure, step-in and transfer rights. Their terms should align across customer, generation, utility, landlord, operator and key vendors. Cure periods should allow practical action without forcing a critical counterparty to continue indefinitely. Consent requirements, licence restrictions and regulatory approvals should be identified before closing.
The replacement plan should name the capabilities required to operate generation, grid interfaces, campus systems, computing equipment, networks, cybersecurity and customer service. A replacement operator may need vendor support and customer approval. Access credentials, source code, monitoring, spares, procedures and records should remain controlled and transferable where legally permitted.
Cybersecurity and operational resilience require specific attention. A default or transfer can increase access and continuity risk. NIST and CISA frameworks can inform governance, incident response and recovery [50]. The financing package should require prompt notice of material incidents, tested recovery, access control and preservation of customer obligations.
| Element | Evidence before funding | Downside action | Value risk if absent |
|---|---|---|---|
| controlled accounts | account agreements and waterfall | preserve operating cash and debt service | cash leakage or interruption |
| customer contract | assignment, notice, cure and direct agreement | maintain service or transfer provider | termination and lost revenue |
| generation and grid | security, consent and continued-service rights | preserve dependable power | stranded campus and compute |
| land and campus | mortgage or lease security and access | maintain physical control | inability to operate or sell |
| compute and software | title, licences, serial register and vendor rights | continue, redeploy or sell equipment | weak recovery and service failure |
| operator and staff | transition plan, records and key services | appoint replacement operator | prolonged outage and customer remedies |
| cyber and data | access, backup, incident and transfer controls | secure transition and recovery | breach, legal exposure and lost trust |
Proposed enforcement record; execution depends on law, contracts and operating capability.
15 Apply the integrated credit decision
The board and credit committee should approve the integrated stack through staged gates. The initial development decision should confirm land, market, power route, customer strategy, preliminary design, development budget and sponsor risk capacity. Financial close should confirm the power, facility and equipment perimeters, executed contracts, funded sources, cost to complete, security, intercreditor terms and support. Each draw should confirm asset eligibility, progress, anti-double-counting and remaining sufficiency.
The decision paper should separate verified facts, specialist opinions, management assumptions and unresolved matters. It should contain the module register, entity structure, interconnection evidence, customer contracts, schedule, cost-allocation policy, sources and uses, cash waterfall, debt sizing, stress cases, covenants, reserves and downside transfer plan.
Six questions govern approval. Which assets and cash flows support each debt silo? Which customer commitments are enforceable and creditworthy? Has any cash, collateral, guarantee or reserve been counted more than once? Who bears delay and cost overrun at each interface? Does each facility amortise within supported cash, contract life and asset life? Does the consolidated stack survive a shared customer or delivery shock?
The approval should state maximum commitments, required equity, support, reserves, advance rates, covenants, permitted distributions and conditions precedent. It should identify unacceptable downside cases and the events that require refreshed approval. A positive strategic view of AI demand does not replace these transaction controls.
Practical execution controls
The sponsor should maintain one controlled capacity register. It should show dependable power, gross facility load, critical IT capacity, reserved capacity, contracted capacity, installed load, accepted service and remaining headroom by module. Units, measurement points and losses should reconcile. The register should identify the evidence and date supporting each value.
The project should maintain a clause-level contract model. Each revenue, cost, milestone, remedy and transfer assumption should point to an executed clause or a clearly labelled management assumption. Amendments and side letters should be version controlled. The model should not use commercial summaries when the executed language differs.
The integrated schedule should be updated at least monthly during construction and more frequently during commissioning. It should identify critical path, float, latest safe date, responsible party, evidence and consequence. A delay notice should show effects on power, facility, equipment deployment, customer delivery and every affected financing facility.
Cost reporting should distinguish committed, incurred, certified, paid, forecast and remaining amounts. Contingency should be allocated by risk. The independent monitor should state physical progress, schedule progress, cost to complete and contingency sufficiency. Delivered equipment should not inflate completion when upstream power and cooling remain unfinished.
Procurement controls should track reservation, purchase order, design approval, manufacture, shipment, title, delivery, storage, installation, commissioning and warranty. Deposits should be protected through refund rights, guarantees, letters of credit or other approved support where commercially available. Serial records should connect equipment to insurance and security.
Generation commissioning should include mechanical completion, synchronization, dependable-capacity testing, efficiency, emissions, controls, protection and operating procedures. Campus commissioning should include substations, cooling, water, fire, fibre, security and load-bank tests. Integrated testing should demonstrate the customer service under normal and relevant failure conditions.
Customer acceptance should use the contractual workload, software, measurement period, performance threshold and evidence. Internal rehearsals can identify defects and do not replace contractual acceptance. Any customer dependency should be documented, notified and linked to schedule relief or deemed acceptance if the contract provides it.
Power-cost reporting should reconcile generation output, fuel, grid imports, exports, storage, losses, demand charges, network charges and customer reimbursement. Timing differences should be included in working capital. A pass-through formula should be tested against actual invoices before commercial operation.
Dispatch governance should define the control room, forecast, nomination, outage, curtailment and emergency processes. The generation operator, campus operator and customer should understand how load is reduced when supply is constrained. The finance model should use the same priority and compensation rules.
The customer-credit file should identify obligor, parent, guarantor, security, financial capacity, strategic dependence, disputes and reciprocal relationships. It should be refreshed after material changes. The borrowing base should respond to deterioration before a payment default where the documents permit.
Collections should be monitored by invoice. The report should show amount, issue date, due date, deductions, dispute, payment and controlled-account receipt. Power reimbursements and service credits should reconcile. Late or disputed cash should receive reduced eligibility until resolved.
Service reporting should use the contractual availability method. Excluded events, maintenance, utility outages, generator outages and customer-caused events should be classified consistently. Estimated credits should enter forward cash tests before invoice adjustment.
Technology planning should identify equipment cohorts, warranty, vendor support, workload compatibility, maintenance, spares, refresh date and residual route. Debt should decline before the supported economic life. A refresh needed to maintain contracted service should have a funded source.
Insurance should be mapped to construction and operation. Builder's risk, delay in start-up, property, machinery breakdown, business interruption, cyber and liability cover can respond to different events. Limits, deductibles, exclusions, loss-payee rights and reinstatement should be tested against the modelled exposure.
Fuel supply should be modelled where dedicated generation depends on fuel. The project should assess transport, pressure, capacity, price, nomination, imbalance, interruption and storage. Dual-fuel or backup arrangements should be recognised only after technical, permitting and contractual evidence.
Grid-event reporting should capture curtailment, outage, voltage, frequency, ramp and protection behaviour. Large computational loads can create reliability concerns when they disconnect rapidly [11-13]. The campus should meet applicable modelling and ride-through requirements and provide data required by the system operator.
The quarterly lender pack should include the capacity register, schedule, cost report, power performance, customer acceptance, invoices, collections, service levels, equipment, incidents, insurance, reserves, covenants and forecasts. Each report should name its data source and accountable owner. Prior periods should remain available for trend review.
Model governance should preserve approved versions, assumptions, formulas and audit logs. Scenario inputs should remain separate from observed results. The model should reproduce debt, reserve and distribution tests from source evidence. Material changes should require review under a defined authority matrix.
Distribution conditions should include historical and forward coverage, funded reserves, no default, current power and service performance, and a compliant borrowing base. A cash sweep can accelerate repayment when contract term, customer credit, equipment support or power rights weaken.
The refinancing calendar should show debt maturities, contract expiries, customer renewal windows, generation maintenance, grid renewal, permit dates and equipment refresh. Preparation should begin while remaining contract term and asset condition can support new credit. A maturity after customer termination or equipment obsolescence creates concentrated refinancing risk.
The sponsor should maintain a stop-funding rule. Additional debt should stop when a required power, permit, contract, schedule, cost, equipment, acceptance, credit or liquidity condition falls outside the approved limit. The rule should identify cure authority, period and capital source.
Related-party contracts require separate review. An affiliate can develop the site, supply power, operate the campus, own equipment or purchase service. Pricing, priority, termination, security, transfer and conflicts should be documented. Circular cash and guarantees should be removed from the independent credit case.
The data room should be organised by common works and module. Core folders should cover corporate structure, land, permits, environment, power, shared infrastructure, module engineering, construction, customer contracts, operations, cybersecurity, insurance, finance, tax, accounting, security and transfer. Every material model input should link to evidence or a named assumption.
Independent advisers should state scope, assumptions, reliance and open matters. The engineer can review design, schedule, cost, completion and performance. The model auditor can test formulas, timing, tax, reserves and covenants. Counsel can assess contracts, security, permits and transfer. Environmental, insurance, tax, accounting and cybersecurity specialists should address their respective exposures.
| Gate | Required evidence | Financing decision | Failure response |
|---|---|---|---|
| development | land, route, permits, preliminary design and budget | approve limited development capital | pause commitments and resolve evidence gap |
| customer | executed capacity, payment, credit and remedies | recognise eligible future cash | exclude, haircut or require support |
| power | dependable generation and grid route with funded works | open matching construction tranche | delay compute and reduce supported capacity |
| construction | integrated schedule, fixed scope and cost to complete | continue certified draws | stop draw and call support |
| commissioning | asset and interface tests | release completion support in stages | cure, retest and retain support |
| acceptance | customer confirmation, invoice and collection | convert relevant debt to term | defer conversion and trap cash |
| operation | performance, reserves, covenants and reporting | permit distributions | sweep cash and remediate |
| downside | direct agreements, transfer consents and operator plan | approve residual reliance | shorten tenor and increase amortisation |
Proposed approval record; each gate requires project-specific evidence.
In the illustrative case, a 1.47 times minimum consolidated DSCR supports the proposed funding only within management's central assumptions. The combined downside falls to 0.86 times before reserves and support. The structure should therefore separate asset-specific debt, preserve sponsor completion support, trap cash under stress and prevent one collateral pool from consuming liquidity allocated to another without approved intercreditor action.
The integrated system should be financed after evidence demonstrates customer cash, dependable power, delivery readiness, asset eligibility and sufficient remaining funds. A diversified stack creates resilience only when debt maturities, security and cash allocation reflect real differences in risk. A disciplined structure makes every capital release a recorded decision tied to a defined collateral pool and an executable route to repayment.
Sources
- International Energy Agency, Energy and AI, Read the primary source
- International Energy Agency, Energy and AI executive summary, Read the primary source
- International Energy Agency, Energy demand from AI, Read the primary source
- International Energy Agency, Energy supply for AI, Read the primary source
- US Department of Energy, 2024 United States Data Center Energy Usage Report announcement, Read the primary source
- Lawrence Berkeley National Laboratory, 2024 United States Data Center Energy Usage Report, Read the primary source
- US Department of Energy, Powering America's AI Future Data Center Resource Hub, Read the primary source
- US Energy Information Administration, Annual Energy Outlook 2026, Read the primary source
- US Energy Information Administration, Data center power demand and generation analysis, Read the primary source
- US Department of Energy, Electricity Demand Growth Resource Hub, Read the primary source
- North American Electric Reliability Corporation, 2025 Long-Term Reliability Assessment, Read the primary source
- North American Electric Reliability Corporation, Large Loads Action Plan, Read the primary source
- North American Electric Reliability Corporation, 2025 State of Reliability Overview, Read the primary source
- PJM Interconnection, 2026 Long-Term Load Forecast, Read the primary source
- PJM Interconnection, Load Forecast Development Process, Read the primary source
- PJM Interconnection, 2026 Load Forecast Supplement, Read the primary source
- Electric Reliability Council of Texas, Large Load Integration, Read the primary source
- Electric Reliability Council of Texas, Planning Guide, Read the primary source
- Electric Reliability Council of Texas, PGRR115 Large Load Interconnection, Read the primary source
- Electric Reliability Council of Texas, NPRR1234 Large Load Requirements, Read the primary source
- Federal Energy Regulatory Commission, PJM Susquehanna Co-Location Proposal order, Read the primary source
- Federal Energy Regulatory Commission, Commissioner Christie concurrence on ER24-2172, Read the primary source
- Federal Energy Regulatory Commission, Large load co-location proceeding EL25-49, Read the primary source
- Federal Energy Regulatory Commission, Order 2023 Interconnection Final Rule explainer, Read the primary source
- Federal Energy Regulatory Commission, Order 2023-A explainer, Read the primary source
- World Bank, Power Purchase Agreements and Energy Purchase Agreements, Read the primary source
- World Bank, A Guide to Power Purchase Agreements, Read the primary source
- Power Africa, Understanding Power Purchase Agreements, Read the primary source
- World Bank, Structuring Power Purchase Agreements to Lower Investor Risk, Read the primary source
- International Finance Corporation, Performance Standards, Read the primary source
- International Finance Corporation, General Environmental Health and Safety Guidelines, Read the primary source
- International Finance Corporation, Telecommunications Environmental Health and Safety Guidelines, Read the primary source
- Equator Principles Association, Equator Principles EP4, Read the primary source
- CoreWeave, 2025 Annual Report on Form 10-K, Read the primary source
- CoreWeave, 2025 Annual Report, Read the primary source
- CoreWeave, May 2026 announcement of USD 3.1 billion HPC-backed delayed-draw term loan, Read the primary source
- Alpha Compute, April 2026 non-recourse GPU-backed financing disclosure, Read the primary source
- Duos Technologies, June 2026 GPU infrastructure and data-centre financing disclosure, Read the primary source
- Talen Energy, 2025 Annual Report on Form 10-K, Read the primary source
- Talen Energy, June 2025 Amazon power agreement announcement, Read the primary source
- Core Scientific, 2026 second-quarter report, Read the primary source
- Riot Platforms, 2026 phased AMD data-centre deployment materials, Read the primary source
- Galaxy Digital, 2025 Annual Report, Read the primary source
- IFRS Foundation, IFRS 15 Revenue from Contracts with Customers, Read the primary source
- IFRS Foundation, IFRS 15 issued standard, Read the primary source
- IFRS Foundation, IFRS 16 Leases, Read the primary source
- IFRS Foundation, IFRS 9 Financial Instruments, Read the primary source
- IFRS Foundation, IFRS 10 Consolidated Financial Statements, Read the primary source
- Office of the Comptroller of the Currency, Comptroller's Handbook Project Finance, Read the primary source
- National Institute of Standards and Technology, Cybersecurity Framework 2.0, Read the primary source
