
1. Frame the M&A decision
The board decision is whether a buyer can acquire control of a linked port and logistics platform at a price that remains defensible after concession obligations, maintenance, expansion and integration are fully funded. The decision extends beyond strategic fit. It asks whether rights transfer, earnings convert into cash, cargo remains durable, intermodal dependencies can be controlled and the combined group can finance the full investment programme through a correlated downside.
The mandate should define the target perimeter, countries, concessions, minority interests, target customers, permitted transaction structures, valuation range, leverage ceiling, currency policy, minimum liquidity and return thresholds. It should also define the buyer's value-creation thesis. Procurement savings, network effects, digital improvements and cross-selling belong in the investment case only when management identifies the mechanism, cost, timing, owner and evidence required to realise them.
The decision should contain stop conditions. Examples include an unassignable concession, an unresolved change-of-control consent, throughput dependent on one terminable customer, earnings that exclude recurring dredging or maintenance, inland access without enforceable capacity, expansion capex without land or permits, a currency mismatch without protection, or a downside case below the approved liquidity and debt-service thresholds. A stop condition is a governance control and does not predict that a target will fail.
2. Treat the platform as one operating system
A port transaction connects maritime access, terminal handling, customs, storage, inland transport, digital data, billing and final delivery. Each component may have a different owner, regulator, contract, currency and performance standard. Acquiring a profitable terminal without mapping these interfaces can leave the buyer with a scarce concession and a weak route to customers.
The World Bank's Container Port Performance Index benchmarks vessel time in port and shows why throughput alone is an incomplete operating measure [2]. The 2025 edition covers 403 ports, approximately 175,000 vessel calls and 247 million container moves; the accompanying analysis highlights round-the-clock crane operations and integrated digital platforms as differentiators [6]. UN Trade and Development likewise identifies congestion, longer handling times and operational reliability as material features of maritime performance [1].
The diligence model should map physical, contractual, cash and data flows. Cargo may move through a terminal, warehouse and inland depot. Rights may sit across a concession, lease, customer agreement and access protocol. Cash may be collected by several entities. Data may pass through customs, port-community and operator systems. The acquisition perimeter is coherent when these routes reconcile and the buyer can identify who controls each critical dependency.
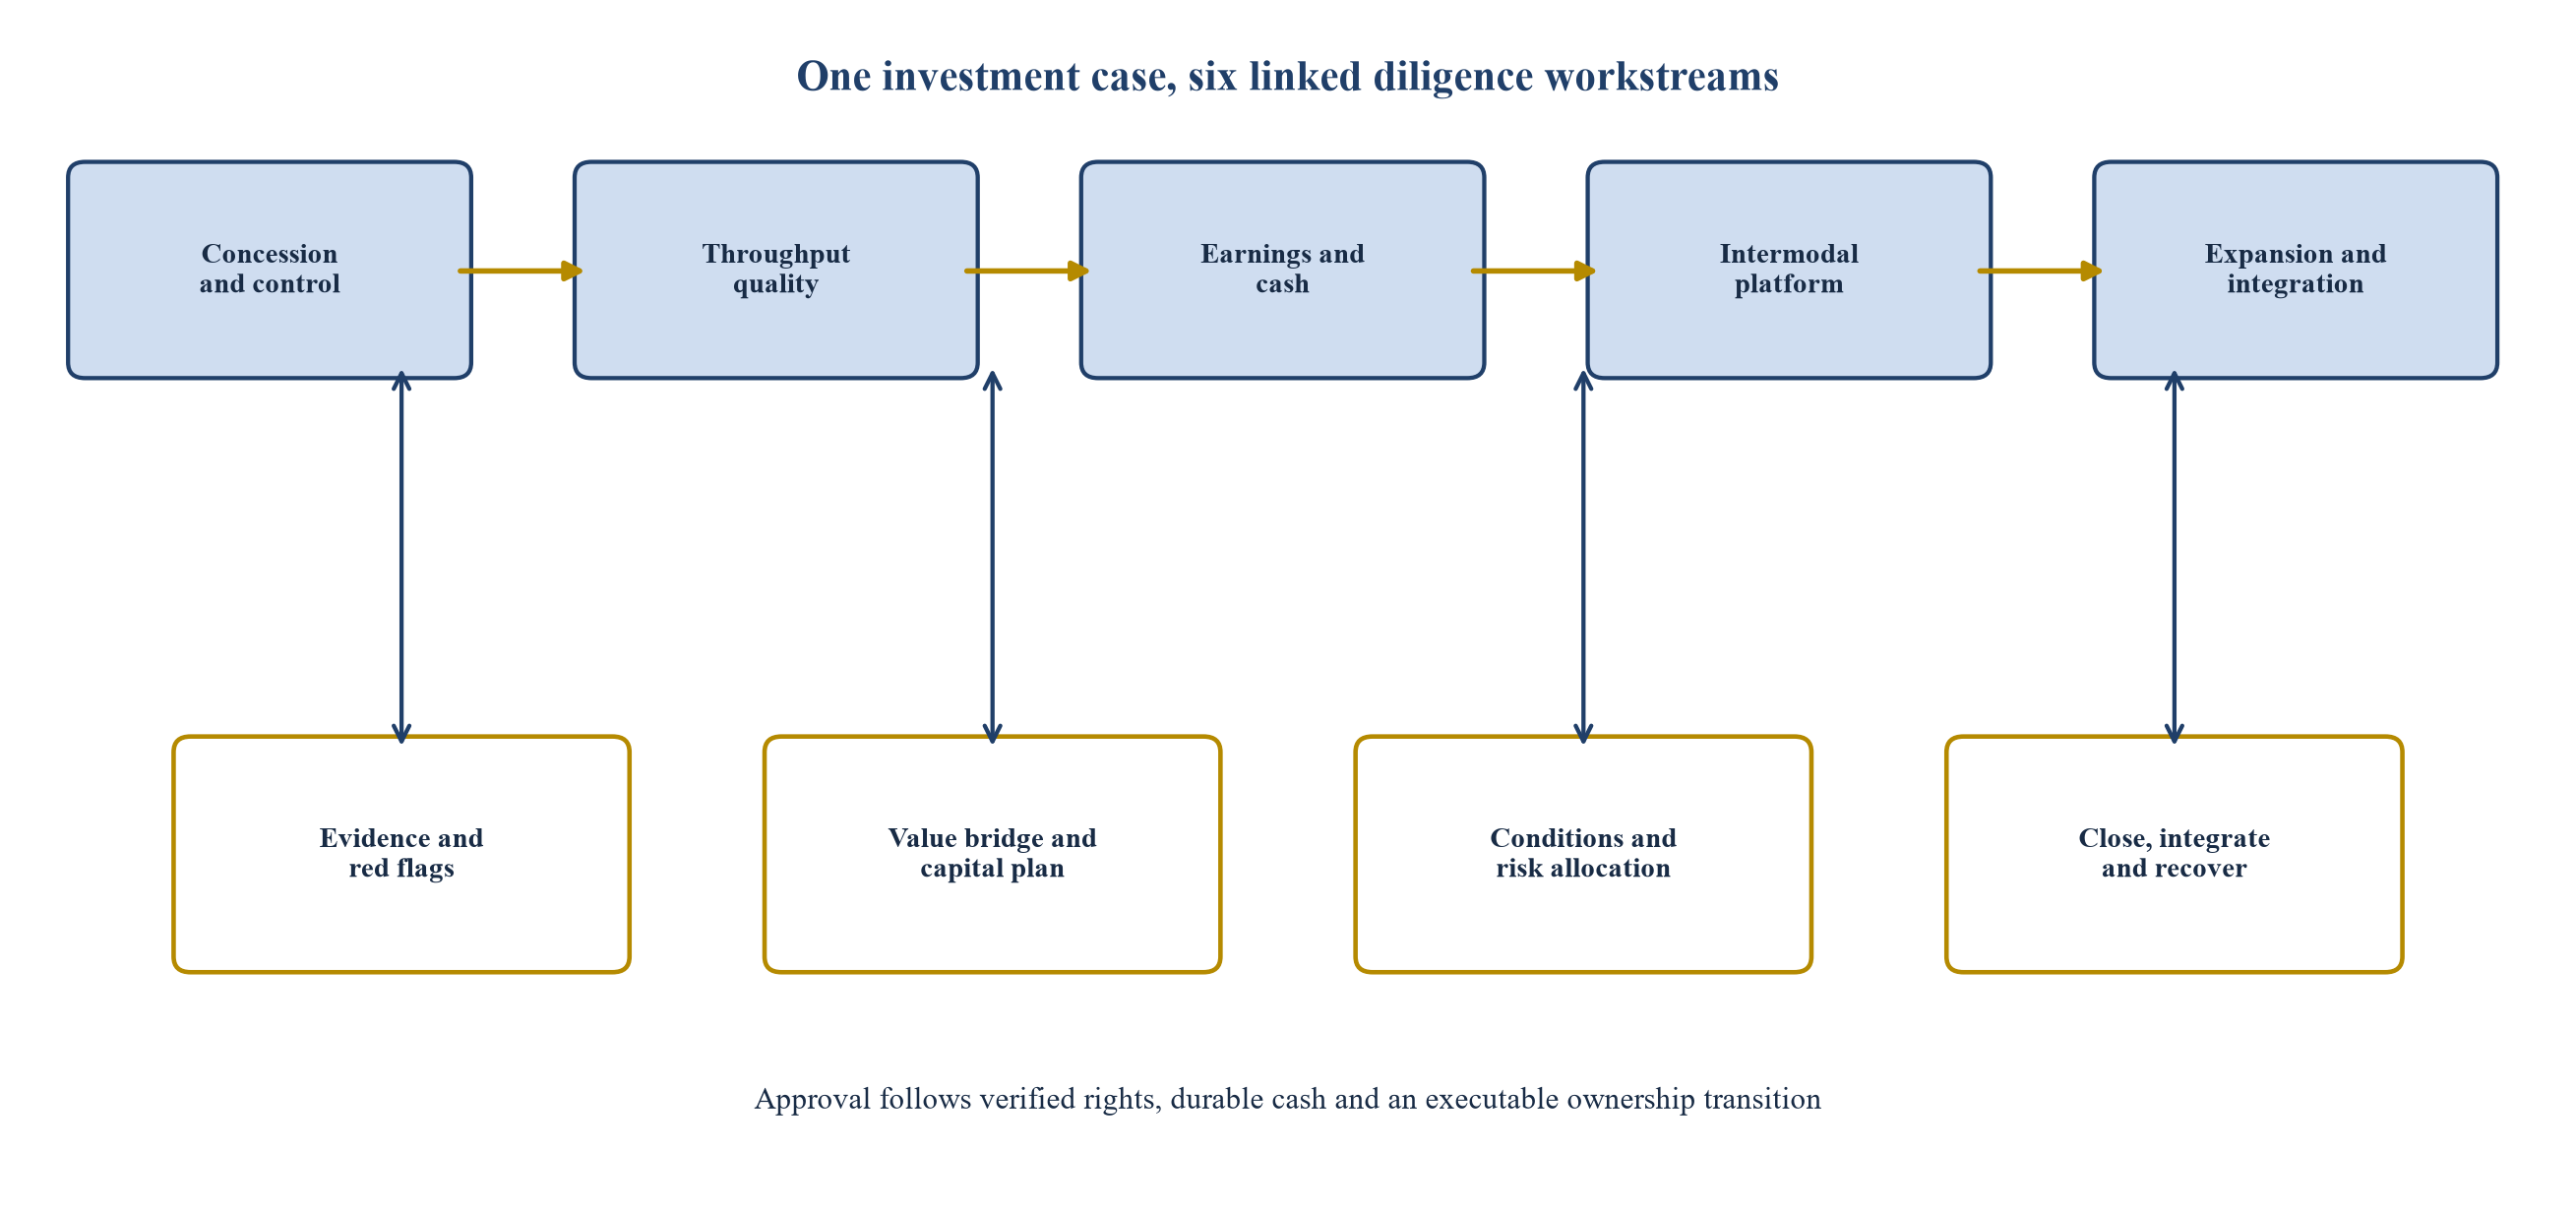
The framework connects rights, cargo, cash, intermodal dependencies, valuation and execution controls.
3. Define the investable perimeter
The project company should hold only assets, rights and obligations that can be governed and financed together. A perimeter that is too narrow may omit the inland dependency that determines cargo conversion. A perimeter that is too broad may combine unrelated public works, social infrastructure and speculative real estate with the cash-generating logistics assets.
The perimeter should be tested across ownership, access, revenue, control, construction and exit. For each asset, management should identify legal owner, operator, land right, customer, tariff basis, capital requirement, maintenance obligation, insurance, security availability and transfer restriction. Shared assets require an access protocol and cost-allocation method.
Perimeter discipline also applies to phases. Phase one should create a commercially coherent minimum operating corridor. Later phases should be options supported by measured demand. Debt for phase one should not rely on speculative later-phase earnings. Expansion may be funded through a committed accordion only after utilisation, service and coverage tests are met.
4. Separate strategic value from bankable cash
Corridors can reduce trade costs, improve resilience, support industrialisation and connect landlocked markets. Those benefits may support policy approval and public investment. They do not automatically produce cash available for debt service.
The Inter-American Development Bank identifies infrastructure quality, border processes, transport services and logistics institutions as connected constraints on regional competitiveness [3]. Its infrastructure atlas maps physical links that support integration across Latin America and the Caribbean [4]. Its port-centric development work explains how coordinated logistics investment can extend value beyond the quay into the surrounding production and distribution system [5]. These priorities strengthen the strategic case while leaving transaction value to be proven asset by asset.
The financial case should identify cash by payer, contract and collection route. Sources may include handling charges, storage, throughput commitments, lease income, rail or trucking fees, digital-service charges and availability payments. Every source should be tested for legal entitlement, volume basis, tariff change, currency, credit quality, collection evidence and termination rights.
5. Build a cargo-demand evidence hierarchy
Traffic forecasts often mix very different levels of certainty. The financing model should classify throughput as contracted, evidenced, contestable or speculative. Contracted cargo is supported by enforceable minimum-volume or take-or-pay commitments. Evidenced cargo is supported by historical movement, production, consumption or trade records. Contestable cargo may shift from another route based on price and service. Speculative cargo depends on future projects or uncommitted market growth.
The base debt case should use contracted and conservatively evidenced cargo. Contestable cargo can support an upside case or expansion gate. Speculative cargo should not support opening leverage. The demand report should reconcile cargo origin, destination, commodity, seasonality, containerisation, route, ship or rail capacity, customer decision rights and competing corridors.
Anchor customers can improve bankability, but concentration creates renewal and bargaining risk. The structure should test the anchor's credit, commitment period, termination rights, price adjustment, performance conditions, parent support and replacement market. The lender should receive periodic evidence that commitments remain effective.
6. Use observed performance as the operating baseline
Throughput volume alone does not demonstrate platform performance. The baseline should include vessel waiting, berth productivity, yard dwell, customs clearance, warehouse occupancy, truck turnaround, rail-cycle time, border delay, damage, service reliability and collection time.
The World Bank's Container Port Performance Index focuses on vessel time in port and warns that performance can be influenced by route changes, weather and geopolitical events beyond a terminal's control [2]. The 2023 Logistics Performance Index found that large delays often occur at ports, airports and multimodal facilities; it also reported that digitalisation can materially shorten port delays [6].
The operating baseline should distinguish controllable and external delay. Contracted service standards can govern controllable performance. Reserve, insurance, route-diversification and force-majeure mechanisms should address external disruption. Mixing the two can create either weak accountability or excessive operator risk.
7. Test concession change of control and financeability
The concession is often the core asset. Diligence should determine whether a direct or indirect change of control requires consent, triggers a re-tender, resets tariffs, accelerates investment obligations or permits termination. The review should reconcile the concession, amendments, port regulations, land rights, operating licences, shareholder agreements, financing documents and the target's actual compliance record.
The World Bank's port public-private partnership guidance identifies demand and revenue allocation as central structuring issues because user charges depend on actual throughput [7]. Its port reform materials also emphasise lifecycle cost, operating performance, financial-close risk and environmental and social obligations [8]. In an acquisition, these features influence both valuation and the conditions required before title or control can transfer.
The acquisition agreement should allocate responsibility for consents, historic breaches, investment arrears, tariff disputes, environmental liabilities and authority claims. Direct agreements should preserve lender notice, cure and step-in rights after the ownership transition. The valuation model should reflect remaining concession life, extension uncertainty, compensation rules and the capital required to satisfy committed investment milestones.
8. Align land, permits and access rights
Ports and warehouses require secure land, marine access, road or rail connections, utilities, environmental approvals, customs status and construction permits. A concession can be complete while a critical access right remains outside its perimeter.
The conditions-precedent register should identify each right, issuer, evidence, expiry, transferability and dependency. Land should be free of incompatible claims or accompanied by a funded and lawful resolution plan. Utility capacity should be evidenced by connection agreements. Road and rail interfaces should have access, dispatch and maintenance protocols.
Where the public authority retains responsibility for access works, completion should be tied to measurable milestones, long-stop dates and remedies. Lenders may require a completion support arrangement, delayed-draw mechanism or alternative route. The model should reflect the cost and time of temporary access rather than assuming immediate public delivery.
9. Integrate environmental and social bankability
Logistics infrastructure can affect coastal systems, fisheries, communities, labour, biodiversity, air quality and traffic safety. These issues are both impact matters and financing dependencies. A weak assessment can delay permits, construction, lender approval and insurance.
IFC's port terminal disclosure illustrates the depth of environmental and social review expected for significant port investment, including impact assessments, emergency response, labour processes, stakeholder engagement and site inspection [9]. The World Bank port module identifies environmental and social management systems, spill response and shore-power considerations among relevant mitigants [8].
The project should maintain a commitments register linking each obligation to owner, budget, schedule, evidence and lender reporting. Land acquisition and resettlement require particularly careful legal and social processes. The financial model should include mitigation, monitoring, remediation and contingency costs rather than treating them as off-model obligations.
10. Reconcile purchase price with expansion capital
An acquisition price can look affordable while the combined commitment exceeds the buyer's funding capacity. The value bridge should therefore show equity purchase consideration, assumed or refinanced debt, minority interests, pension and environmental liabilities, working-capital normalisation, transaction costs, mandatory maintenance, committed concession investment and discretionary expansion.
Latin American port systems continue to attract material investment. Brazil reported eight port auctions representing approximately BRL 10.3 billion of investment during 2025 [10], while national port throughput reached a reported 1.4 billion tonnes, 6.1 per cent above the prior year [11]. Colombia's infrastructure agency identifies a broad concession portfolio across eight port zones [12]. Peru's transport regulator publishes concession and operating statistics that can support asset-level benchmarking [13]. These public signals establish an active infrastructure context; they do not establish the value or availability of any target.
Each capital phase should have a scope, budget, completion test, utilisation threshold and funding source. Mandatory safety, maintenance and concession work belongs in committed capital. Expansion should proceed against verified demand and permits. Strategic options can remain equity-funded until the evidence supports debt or a separate joint venture.
| Value layer | Core diligence question | Minimum evidence | Deal response |
|---|---|---|---|
| Control rights | Can ownership and security transfer lawfully? | Concession, consents, shareholder rights and direct agreements | Condition precedent or structure change |
| Existing operations | Are earnings supported by durable throughput and service? | Customer, cargo, tariff, operating and collection evidence | Normalise EBITDA and working capital |
| Maintenance | What spend sustains current service and compliance? | Asset condition, dredging, equipment and lifecycle plan | Deduct from cash and committed capital |
| Expansion | What spend supports evidenced growth? | Land, permits, contracts, utilisation and cost plan | Stage through performance gates |
| Integration | What must change after close? | Systems, people, TSA, cyber, procurement and reporting plan | Fund and govern a 180-day programme |
The gate descriptions are a proposed governance framework and require transaction-specific calibration.
11. Build the completion architecture
Completion should be defined across construction, operations and interfaces. Physical completion alone may not establish commercial completion. The project may need testing, customs approval, systems integration, trained staff, safety certification, road or rail readiness and initial customer acceptance.
The completion package should include fixed or bounded construction contracts, performance security, insurance, independent engineer certification, cost-to-complete testing, contingency, delay liquidated damages and sponsor support. Interface completion should be demonstrated through end-to-end cargo trials from vessel or origin to inland delivery.
Debt drawdown should follow verified expenditure and completion progress. Retention and reserve mechanisms should protect unfinished work. A delayed component should trigger an updated cost-to-complete and liquidity test. Completion support should terminate only after agreed technical, operating and financial tests are met.
12. Allocate interface risk explicitly
Interface risk appears when one party's performance depends on another party's system, asset or approval. Examples include berth availability, customs release, warehouse receipt, rail dispatch, truck access, border clearance and customer delivery.
The contract matrix should identify the event, responsible party, evidence, service level, compensation, cure, escalation and lender consequence. Each interface should have one accountable owner and a shared operating protocol. Duplicate responsibility can leave gaps because each party assumes the other will act.
The model should quantify the cash effect of interface failures. Port congestion may extend dwell and reduce throughput. Customs delay may increase storage revenue while harming customer service and working capital. Rail unreliability may shift cargo to more expensive trucking. The financing case should use the net effect, including penalties, additional operating cost and lost future cargo.
13. Choose the revenue model
Corridor revenue can be user-paid, availability-based or hybrid. User-paid structures expose the project to volume, mix and collection. Availability payments can reduce demand risk but create public-credit, performance-deduction and fiscal-appropriation risk. Hybrid structures can combine a minimum service payment with variable cargo revenue.
The choice should reflect who controls demand, whether tariffs are regulated, the public authority's fiscal capacity, customer credit and the asset's strategic role. A public guarantee should address a clearly defined obligation. Broad guarantees can transfer commercial risk without improving operating discipline.
Tariffs should be indexed to relevant costs and currencies where legally permitted. The contract should specify review timing, caps, floors, pass-through items and dispute resolution. The financial model should test delayed tariff adjustment and collection leakage.
14. Contract anchor customers without trapping the platform
Anchor customers can support initial utilisation, financing and operating design. Their contracts should define committed volume, minimum revenue, capacity reservation, service levels, credit support, indexation, term, termination and remedies.
The platform should preserve multi-user access and the ability to serve new cargo. Exclusive rights can improve anchor commitment while limiting growth and creating regulatory concerns. Capacity allocation should be transparent and consistent with the concession.
The financing model should show anchor revenue separately from spot and growth revenue. It should test customer default, early termination and volume underperformance. Replacement assumptions should reflect actual customer conversion time and route competition. Debt sizing should not treat an unenforceable letter of intent as contracted revenue.
15. Finance warehouses as operating assets
Warehouses can provide lease income, handling revenue, inventory visibility and cargo retention. Their bankability depends on location, customs status, tenant commitments, fit-out, utilities, inventory type, insurance and alternative use.
The model should distinguish bonded, temperature-controlled, general and specialised facilities. Each has different construction, energy, compliance and tenant risks. Temperature-controlled logistics may justify higher revenue but requires resilient power, maintenance and product-loss controls. The acquisition model should test tenant duration, energy intensity, product-loss exposure and alternative use rather than applying a single warehouse multiple.
Warehouse financing can use project debt, real-estate debt, equipment facilities or tenant-backed structures. The chosen route should match lease term, operating risk and residual value. Debt maturity should not assume a lease renewal that has not been contracted.
16. Finance inland terminals and connectivity
Inland terminals can reduce port dwell, consolidate customs processing and extend the gateway into landlocked markets. They require cargo density, land, road or rail access, customs recognition, equipment, information systems and reliable dispatch.
Inter-American Development Bank research links port-centric investment to inland logistics, trade facilitation and the wider productive system [5]. Brazil's national waterway statistics provide an official operating baseline for public and private terminals [16]. The buyer should combine these external benchmarks with target-specific dispatch, access and customer data.
The project should decide whether inland assets sit inside the port concession, a separate project company or a contracted interface. Separate ownership can attract specialised capital but requires durable access and revenue-sharing agreements. The base case should include actual transfer cost and border time.
17. Make digital systems a financing control
Digital port-community, customs, warehouse and transport systems can improve visibility and reduce delay. They also become operational dependencies and sources of cyber, data and vendor risk.
Public port reporting increasingly supports corridor-performance monitoring and asset comparison [17]. UN Trade and Development identifies automation, artificial intelligence and digital port management as tools for reducing waiting time and improving cargo tracking [18].
The digital architecture should connect booking, gate, customs, inventory, dispatch, billing and cash evidence. Lenders should receive reconciled operating data rather than management estimates. The contracts should address data ownership, service levels, cybersecurity, continuity, audit, interoperability and exit. A digital investment should have measurable service and cash outcomes.
18. Address currency and convertibility
Revenue, operating costs, capital expenditure and debt may use different currencies. A corridor may collect local-currency fees while equipment and debt service are denominated in dollars or euros. Convertibility and transfer restrictions can prevent otherwise profitable cash from reaching lenders.
The financing model should separate accounting revenue from available debt-service cash. It should map collection accounts, permitted conversion, taxes, reserves, dividend rules and transfer approvals. Local-currency debt can reduce mismatch when market capacity and tenor are sufficient. Indexed tariffs, blended debt, hedging and reserve structures can address residual exposure.
The downside case should combine currency weakness with delayed tariff adjustment and lower cargo. These stresses are often correlated. The project should define liquidity actions before covenant breach, including expenditure deferral, equity cure, reserve use and temporary distribution lock-up.
19. Match transaction structure to the risk layers
The buyer can use a share acquisition, asset acquisition, concession-level investment, joint venture, minority investment or staged control structure. The choice affects consent, tax, historic liabilities, security, consolidation, minority protection and the ability to fund expansion. A clean legal form does not remove operating dependency; the structure should follow the evidence and the buyer's control requirements.
Seller rollover and contingent consideration can bridge valuation uncertainty when the seller retains operating influence and the measurement rules are auditable. Earn-outs require precise definitions for throughput, EBITDA, capex, related-party charges and exceptional events. Minority structures require reserved matters, information rights, funding obligations, deadlock and exit mechanisms. Acquisition debt should rely on controlled cash rather than expected synergies.
Asset-level finance can ring-fence equipment or expansion where rights, cash and security are separable. Working-capital facilities should cover genuine receivables and operating cycles. Development or climate-linked capital may support eligible resilience or public-interface expenditure, subject to programme criteria and additionality. Each instrument should address a diagnosed risk and preserve the buyer's recovery options.
| Decision need | Candidate structure | Evidence required | Primary protection |
|---|---|---|---|
| Full operating control | Share or asset acquisition | Transferability, liabilities, consents and cash control | Warranties, indemnities, conditions and security |
| Valuation uncertainty | Seller rollover or earn-out | Auditable metrics and governance | Caps, definitions, set-off and dispute process |
| Regulatory sensitivity | Joint venture or staged control | Reserved matters and approval pathway | Step-up rights, deadlock and exit |
| Expansion ring-fence | Asset-level or project finance | Rights, contracts, cost and collection | Controlled accounts and completion tests |
| Equipment and working capital | Equipment line or revolving facility | Asset title, receivables and utilisation | Asset security and borrowing base |
The allocation is illustrative and does not represent available financing terms or investor appetite.
20. Construct the hypothetical acquisition case
The illustrative transaction assumes a GCC strategic buyer acquires 65 per cent of a multi-country Latin American platform with port-terminal, warehousing and inland-logistics operations. The illustrative enterprise value is USD 780 million. Total committed capital is USD 800 million: USD 480 million of cash purchase consideration, USD 60 million of refinancing and transaction costs, USD 180 million of expansion capex, USD 40 million of integration and digital investment, and USD 40 million of liquidity and contingency.
The assumed sources are USD 300 million of buyer equity, USD 260 million of acquisition debt, USD 120 million of seller rollover, USD 80 million of asset-level finance and USD 40 million of deferred or contingent consideration. These figures are management scenarios, not a valuation, financing proposal or evidence of available capital.
The platform handles an illustrative 1.45 million twenty-foot equivalent units at close and 1.90 million in year five. The largest customer represents 18 per cent of revenue and the five largest represent 46 per cent. The central case assumes year-three EBITDA of USD 122 million, maintenance and committed capex of USD 38 million, cash available for debt service of USD 84 million and debt service of USD 54 million. Tariffs, costs, tax, currency, volume and synergy assumptions are hypothetical.
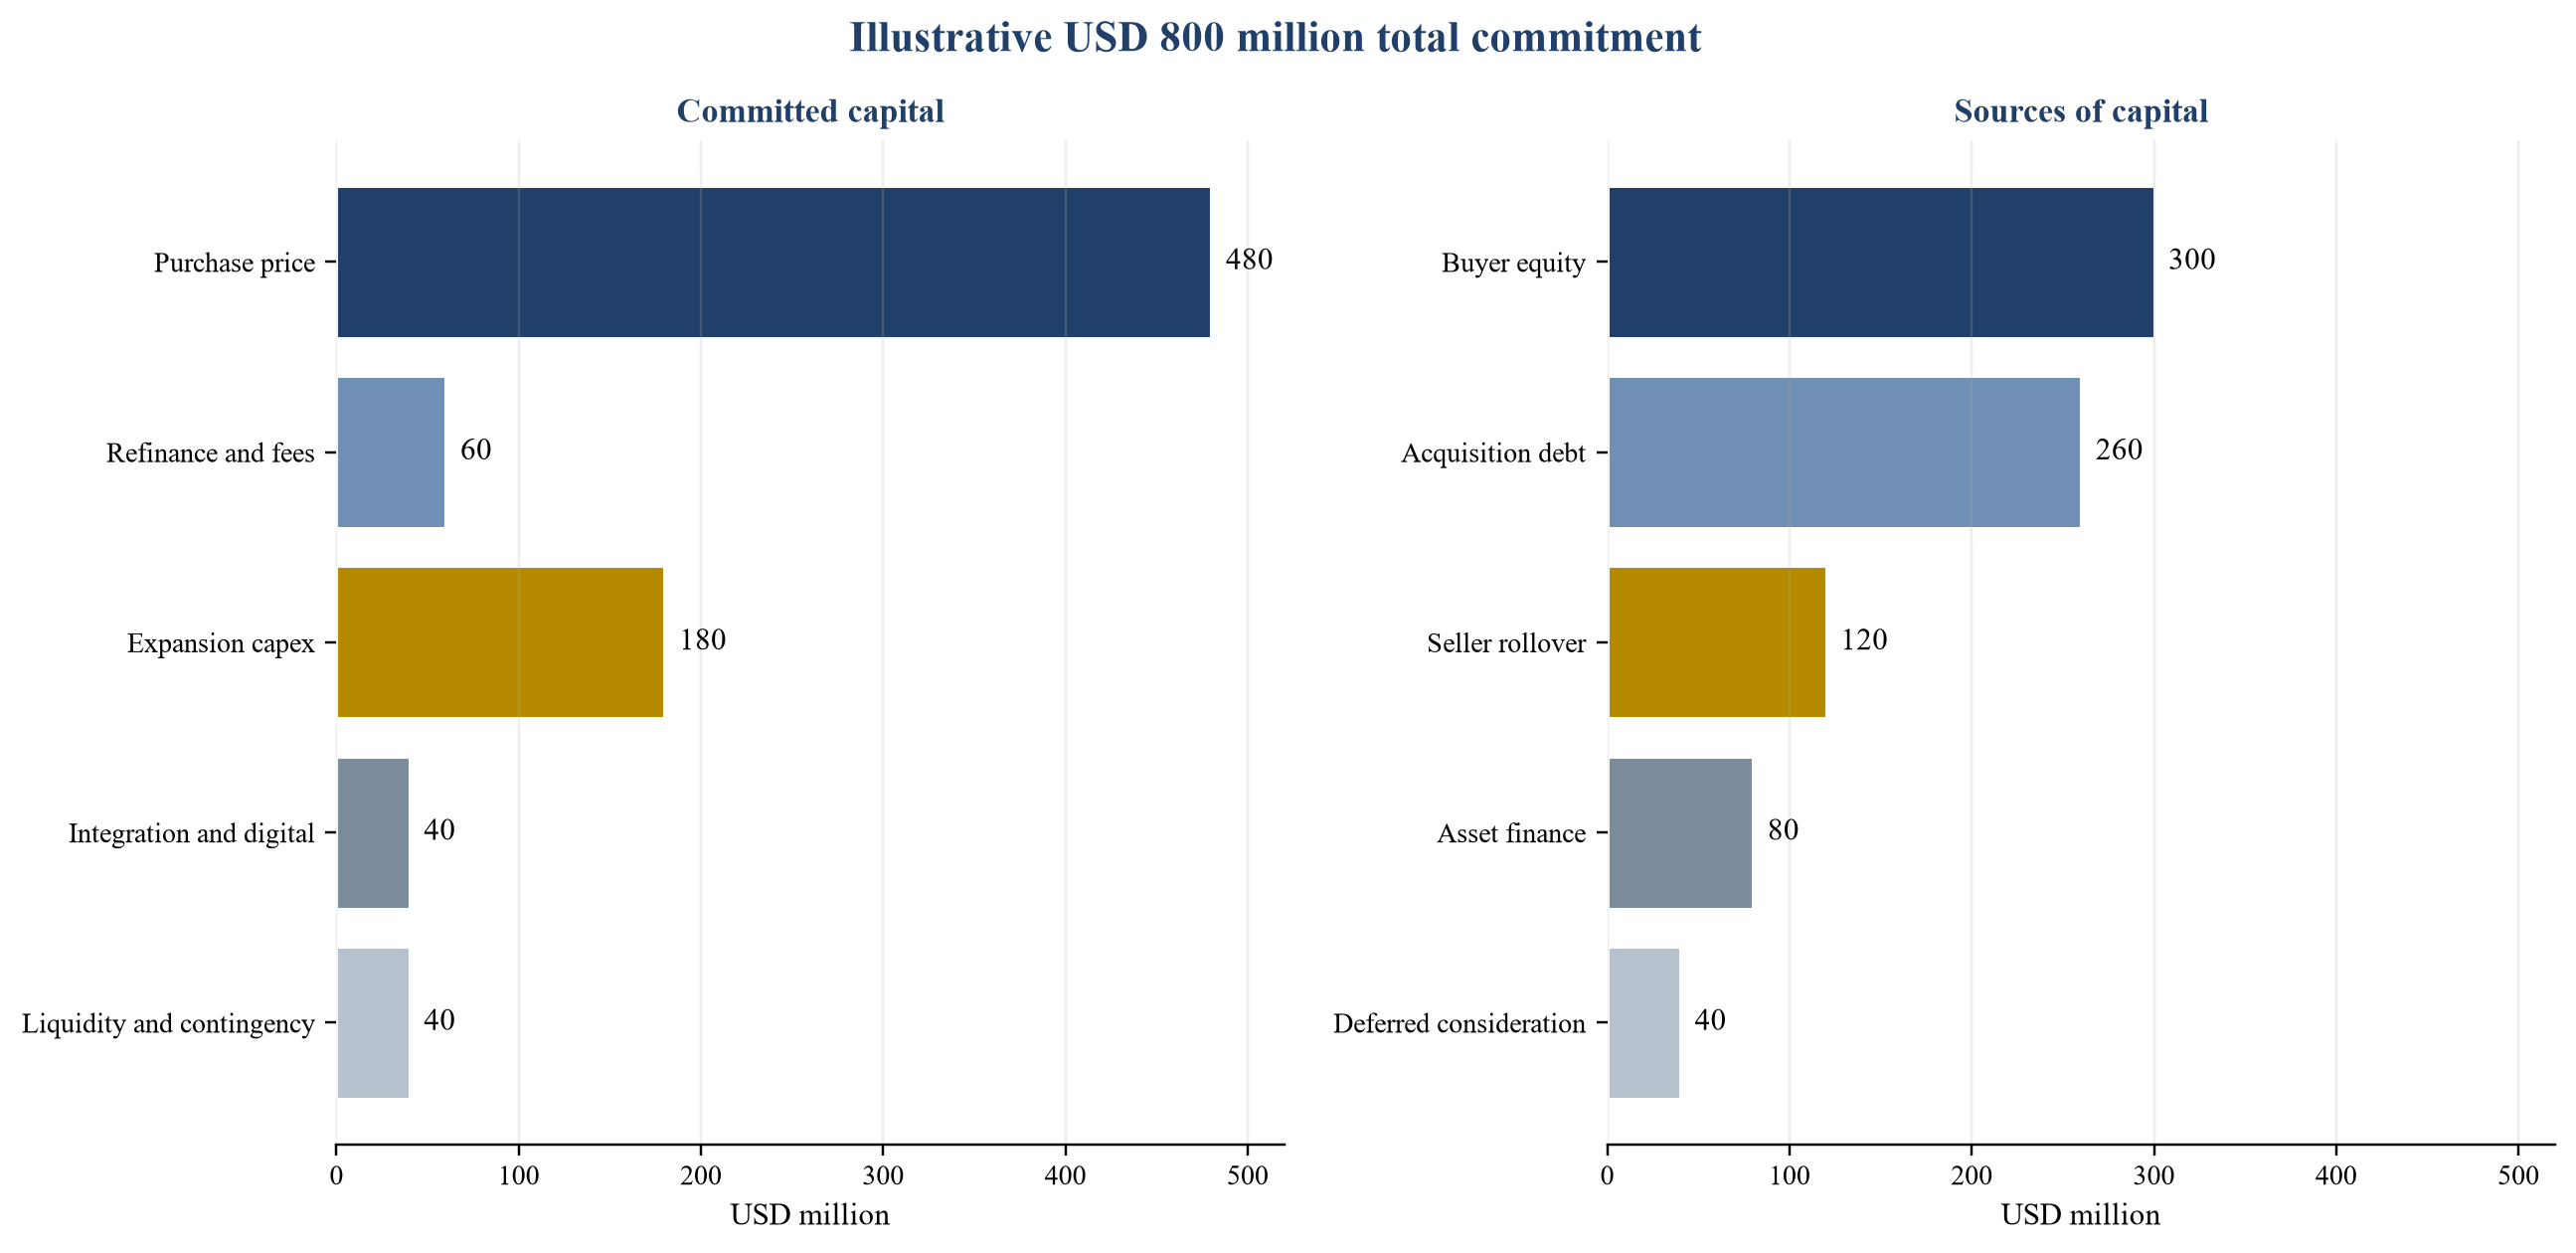
All amounts are USD millions and are illustrative management assumptions.
21. Size acquisition debt to resilient cash flow
Debt should be sized to the minimum of controlled cash-flow capacity, concession life, security enforceability, market capacity and stress resilience. Headline EBITDA can overstate capacity when it excludes maintenance, dredging, lease payments, restricted cash, minority leakage or expansion needed to retain the concession.
The central case produces year-three cash available for debt service of USD 84 million against USD 54 million of debt service, equivalent to 1.56 times. A lower-throughput case produces 1.34 times. A tariff and currency case produces 1.18 times. A correlated downside combining throughput reduction, tariff pressure, currency weakness and higher capex produces 1.00 times before remedial action. These outputs are hypothetical.
The financing structure should include liquidity, a debt-service reserve, maintenance controls, distribution lock-up, cash sweep and cure regime. Covenants should use clearly defined cash available for debt service and debt-service concepts. The model should prevent double counting of seller rollover, reserve releases, contingent consideration or asset-level facilities.
22. Test correlated downside scenarios
Scenario design should reflect how transaction risks interact. A route disruption can reduce vessel calls, increase congestion and raise cost. Currency weakness can increase imported equipment and debt service while tariffs adjust slowly. Construction delay can postpone revenue and increase interest during construction.
The downside model should test at least completion delay, cost overrun, lower throughput, anchor loss, tariff delay, operating-cost increase, currency weakness, border delay and refinancing stress. The severe case should combine plausible correlated events rather than apply isolated sensitivities.
The action plan should link each threshold to a response. Responses may include deferring expansion, using contingency, drawing reserves, requiring equity, renegotiating service levels, activating alternate inland capacity, increasing collection control or suspending distributions. A scenario without an executable response is only a diagnostic.
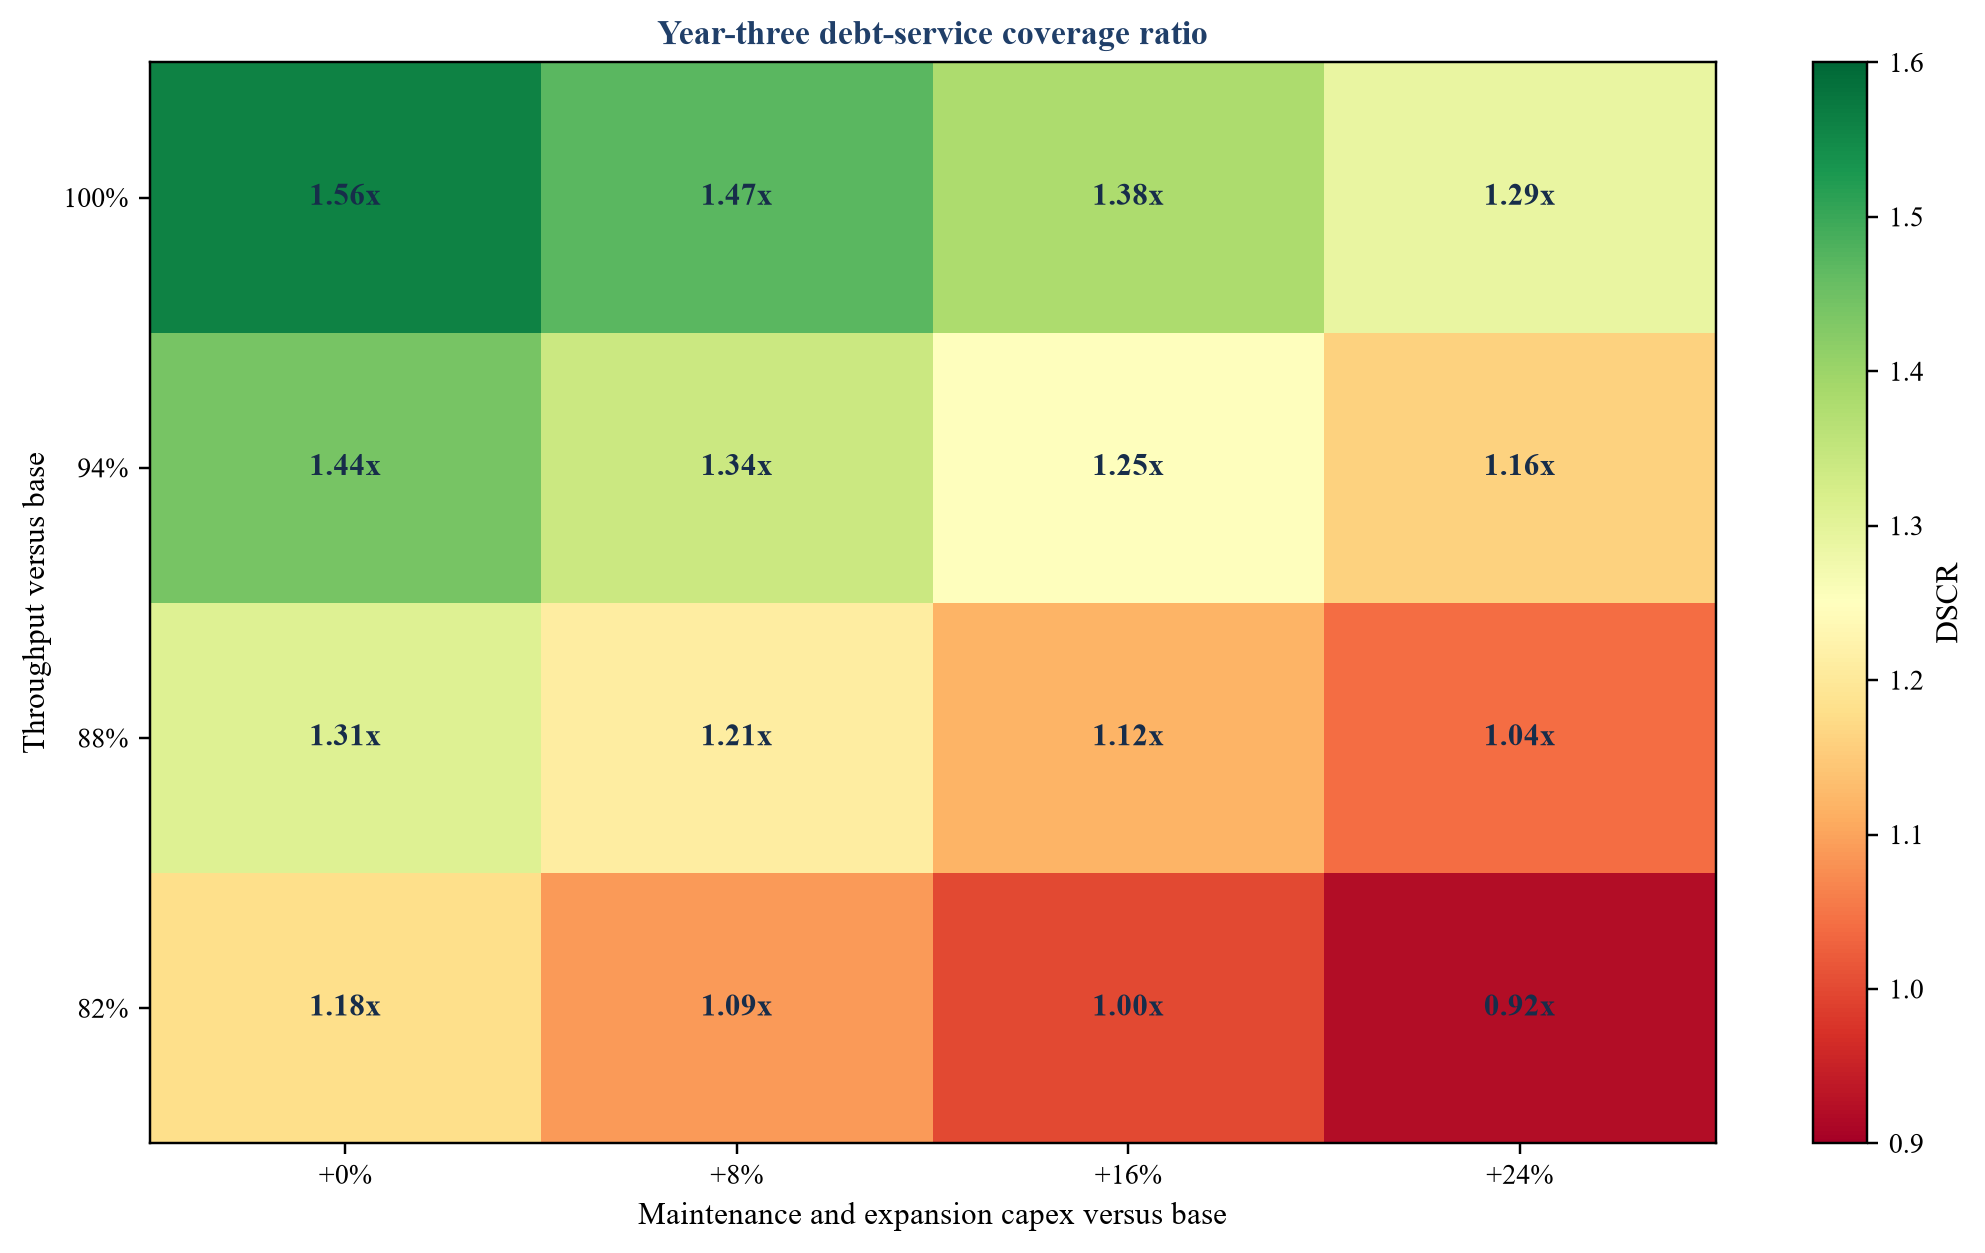
Ratios are illustrative management assumptions and do not represent a credit opinion.
23. Allocate political and public-interface risk
Political and public-interface risks include concession change, expropriation, transfer restriction, delayed public works, tariff intervention, customs policy and permit withdrawal. The structure should allocate each risk to the party able to manage it or support it.
Tools can include direct agreements, change-in-law protection, termination compensation, political-risk insurance, partial risk guarantees, sovereign or sub-sovereign support, escrow and development-finance participation. Each tool has eligibility, pricing, exclusions, claims and tenor constraints. Availability should be verified before the capital structure relies on it.
The project should distinguish a government undertaking from a legally enforceable and budgeted payment obligation. Fiscal approval, appropriation, debt limits and public procurement may affect enforceability. Local legal advice and public-finance diligence are essential.
24. Design controlled accounts and cash governance
Cash governance should follow the operating and financing perimeter. Customer receipts should enter controlled accounts with an agreed waterfall for taxes, operating cost, maintenance, debt service, reserves, permitted capital expenditure and distributions.
Where several operating entities collect cash, the structure should define sweep timing, currency conversion, leakage controls, intercompany charges and insolvency risk. The lender should receive reconciliations from operating records to invoices, bank receipts and the debt-service account.
Reserve use should be rule-based. A debt-service reserve can bridge temporary volatility but should not support a structurally weak case. Maintenance reserves should reflect actual lifecycle plans. Distribution should stop when coverage, completion, reserve or compliance tests fail.
25. Build data and assurance into the financing documents
Corridor assets generate large volumes of operational data. The financing package should specify the data fields, source systems, frequency, reconciliation and assurance that support borrowing, covenants and expansion.
The monthly dashboard should include throughput by customer and cargo type, vessel and truck time, dwell, warehouse occupancy, border time, service failures, invoicing, collection, operating cost, capital expenditure, reserve balances and coverage. Customer commitments and concession compliance should be reported separately.
Independent technical and model assurance should focus on the points that change credit capacity. Excessive reporting can obscure the critical indicators. Lenders and sponsors should agree a concise data dictionary and exception process before first drawdown.
26. Price climate and resilience investment
Ports and corridors face sea-level, storm, flooding, heat, drought, landslide and route-disruption risks. Resilience should be integrated into design, insurance, maintenance and financing rather than added after construction.
UN Trade and Development reports that climate and geopolitical disruption at maritime chokepoints can lengthen routes, raise costs and create congestion [18]. Its 2024 review calls for climate-proofed infrastructure, early-warning systems, alternative routes and balanced contractual allocation of weather-related risk.
The project should identify critical assets, service thresholds, recovery time, alternate capacity and resilience capital. Eligible resilience expenditure may attract development or climate-linked finance. The financial benefit should be measured through avoided downtime, reduced repair cost, lower insurance exposure or protected revenue. Unsupported resilience benefits should remain outside the base case.
27. Plan refinancing from the start
Construction and early ramp-up risk can require expensive or short-tenor capital. Once completion, throughput and collections are proven, the project may refinance into longer-tenor bank, bond or institutional debt.
The refinancing plan should define evidence thresholds, timing, prepayment cost, hedging treatment, reserve release, security transition and gain allocation. It should also test a market-closure scenario. A project should remain viable if refinancing is delayed.
The concession should permit refinancing and security transfer subject to reasonable approvals. Lenders may require direct agreements and continuity of step-in rights. Sponsor distributions should not assume refinancing proceeds before the transaction is executable.
28. Protect multi-user and public value
Port and logistics platforms often receive exclusive or scarce rights. Governance should preserve service quality, non-discriminatory access, transparent tariffs, safety, local capability and investment obligations.
Multi-user rules should define capacity allocation, related-party transactions, customer prioritisation and dispute resolution. Performance standards should be measurable and compatible with lender cure rights. Public reporting can improve accountability without disclosing commercially sensitive information.
Local procurement, employment and supplier development can support public value when requirements are realistic and funded. Obligations should be specified, measured and included in the cost model. Ambiguous commitments can create disputes and unplanned expenditure.
29. Use a transaction risk heat map
The risk heat map should combine likelihood, financial consequence, evidence confidence and control maturity. High-consequence risks with weak evidence deserve priority even when management considers their likelihood low.
The heat map should cover demand, anchor customers, concession, land, completion, interface, operating cost, currency, convertibility, climate, environmental and social matters, public support, cyber, refinancing and recovery. Each risk should have an owner, action, deadline, evidence and escalation threshold.
Risk scores are decision aids. They do not replace the cash model or legal analysis. The board should receive both the score and the underlying exposure.
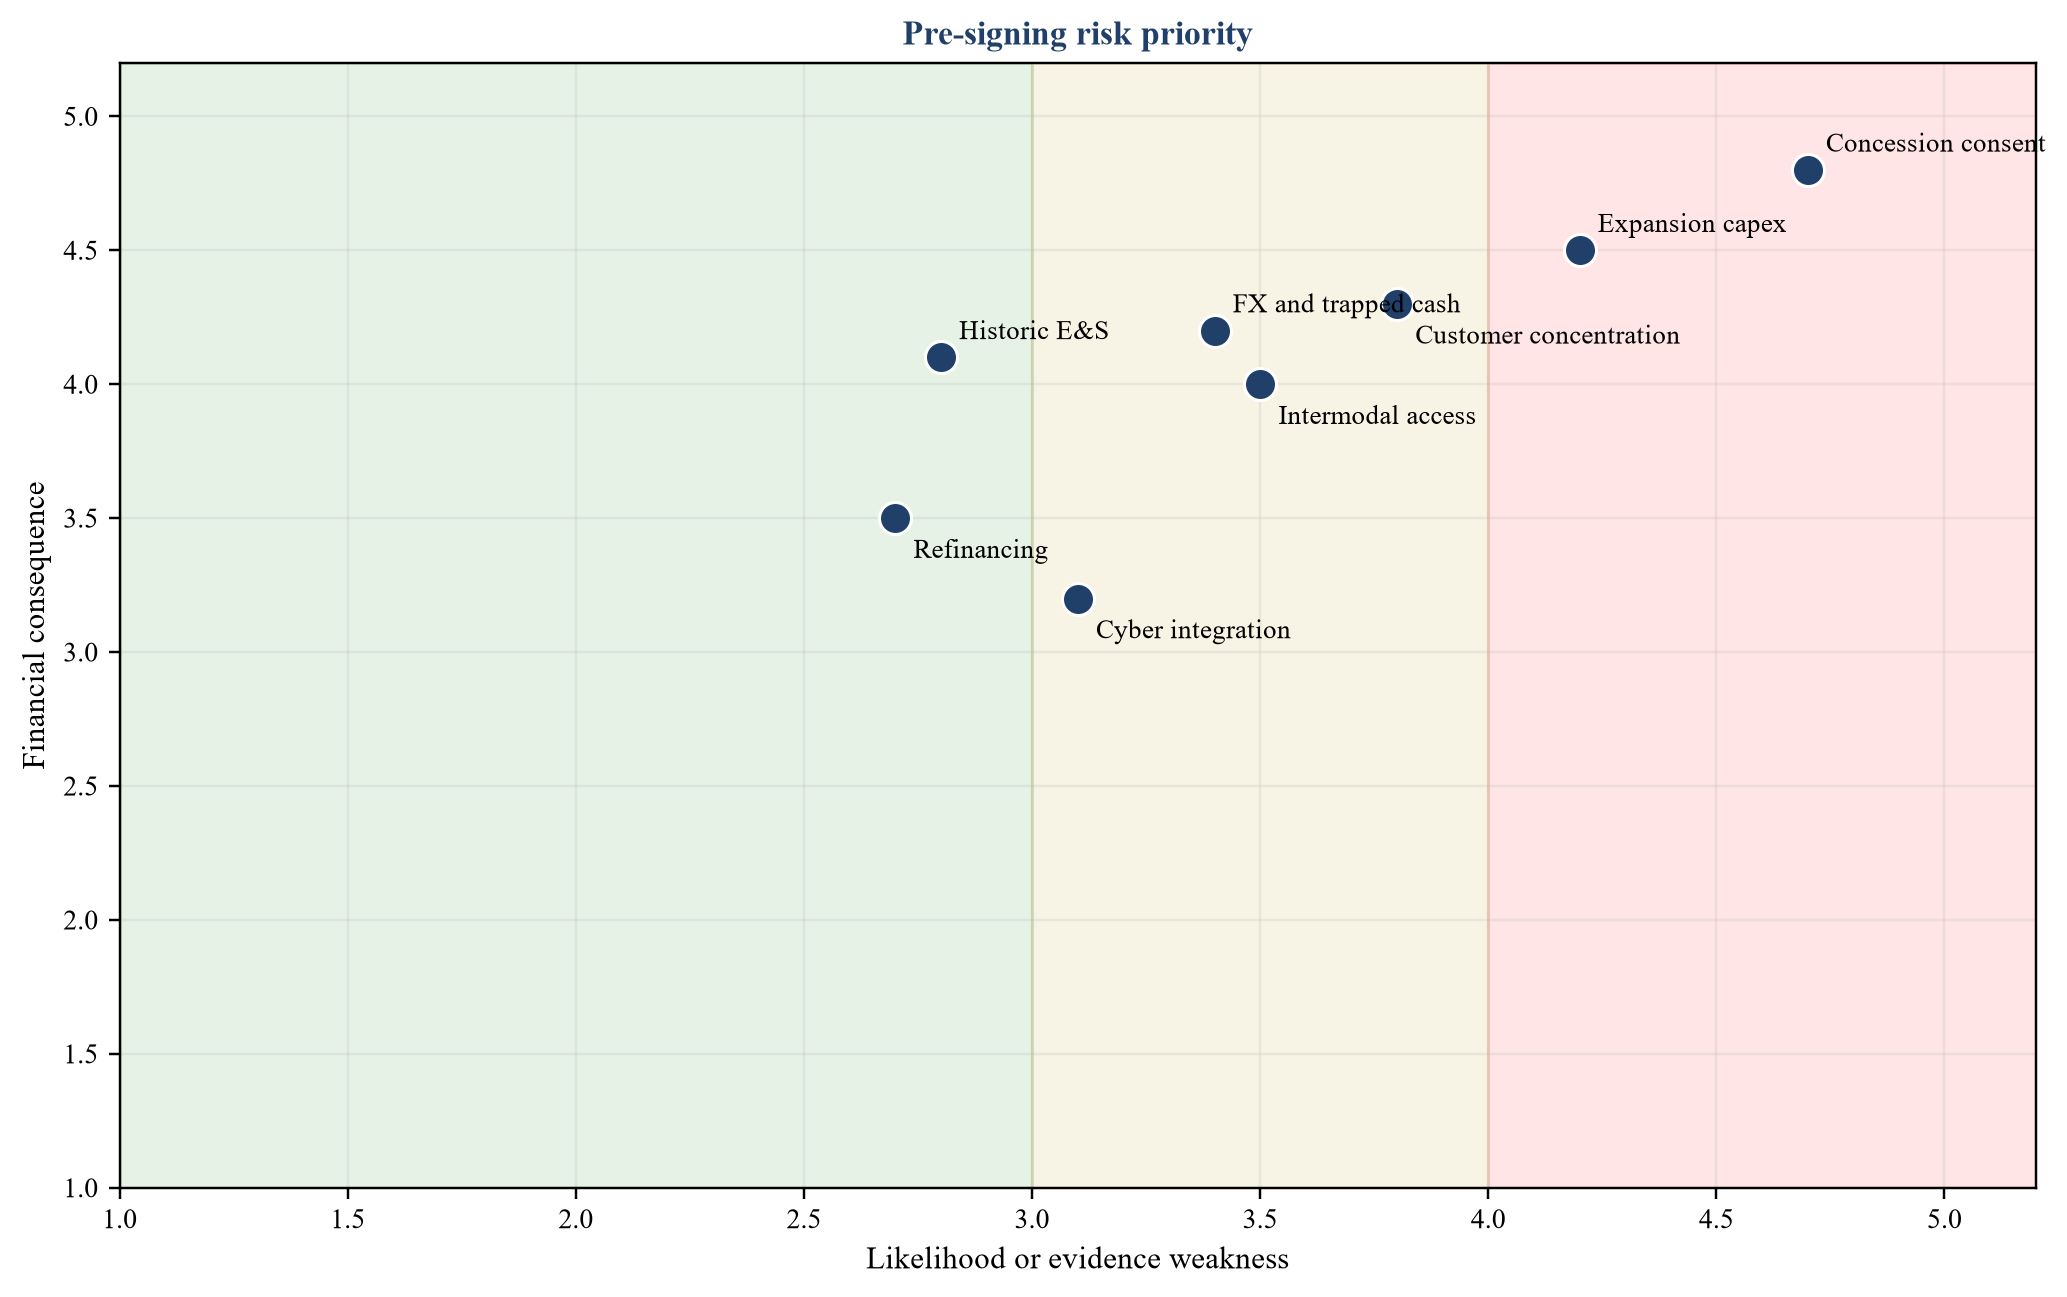
Positions are hypothetical and show how evidence confidence changes transaction priority.
| Risk | Likelihood | Consequence | Evidence confidence | Primary control |
|---|---|---|---|---|
| Throughput below base | Medium | High | Medium | Anchor commitments, phased expansion and cash sweep |
| Inland interface delay | Medium | High | Medium | Access agreement, alternate trucking and completion gate |
| Concession or tariff change | Low | High | Medium | Direct agreement, change-in-law and termination protection |
| Currency and transfer stress | Medium | High | Medium | Local debt, indexed tariff, reserves and political-risk support |
| Construction overrun | Medium | High | High | Fixed scope, contingency, security and sponsor support |
| Climate disruption | Medium | High | Medium | Resilient design, insurance, warning and recovery plan |
| Data or cyber outage | Medium | Medium | Medium | Segregation, backup, incident response and manual fallback |
| Refinancing unavailable | Medium | Medium | High | Amortisation, extension options and retained liquidity |
Scores and responses are hypothetical management assumptions for the worked case.
30. Establish decision gates
The programme should use formal gates for development, commercial readiness, financial structure, construction, operations and expansion. Each gate should define evidence, decision owner, unresolved matters and conditions for proceeding.
Gate one confirms the mandate and perimeter. Gate two confirms rights, demand and interfaces. Gate three approves the financing case and risk allocation. Gate four authorises financial close and first drawdown. Gate five confirms technical and commercial completion. Gate six authorises expansion or refinancing.
The investment committee should see the base case, correlated downside, funding plan, evidence gaps, conditions and recovery path. Approval should state which assumptions may change without renewed consent. This creates a controlled bridge from strategic ambition to funded execution.
31. Execute the first 180 days
The first thirty days should reconcile the asset perimeter, concession, land, traffic evidence, anchor customers, capital scope, operating interfaces and public obligations. Management should establish a controlled data room and a single issues register.
Days thirty-one to ninety should develop the traffic and cash model, technical scope, environmental and social plan, contract matrix, support package and lender information memorandum. Independent advisers should challenge demand, cost, schedule, legal rights and model logic.
Days ninety-one to one hundred and eighty should secure indicative terms, negotiate key contracts, close evidence gaps, finalise approvals, complete documentation and test operating reporting. Financial close should occur only when conditions precedent and funding sources reconcile.
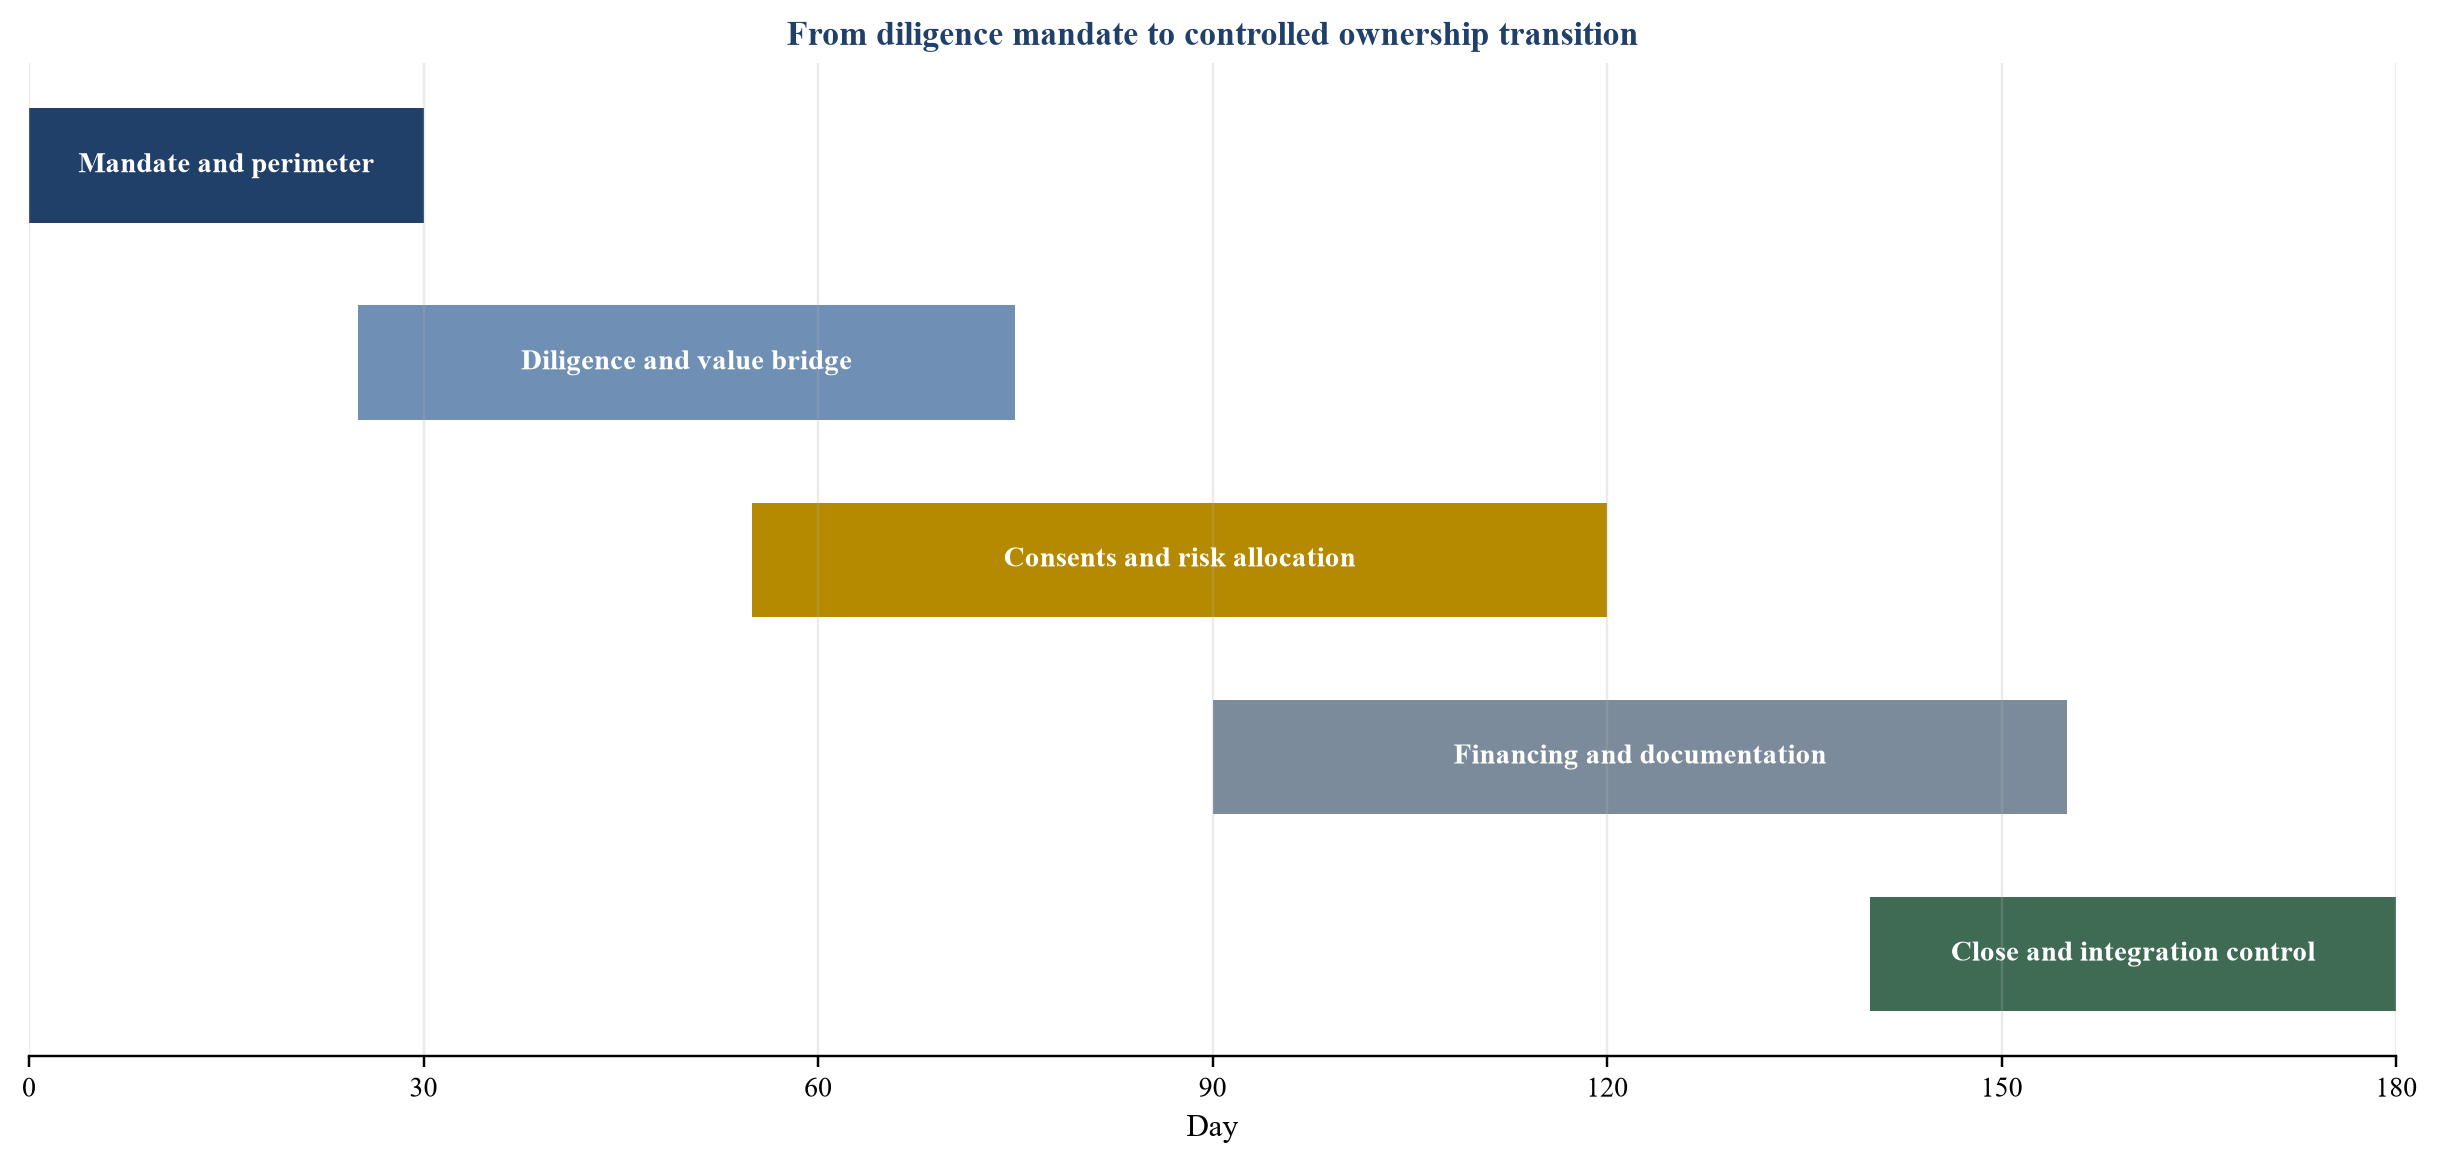
Timing is a hypothetical management assumption and should be rebuilt for each transaction.
32. Apply the M&A decision checklist
Before approval, management should confirm that the platform has a defined perimeter, enforceable rights, sufficient concession life, secured land, an integrated operating map, a credible cargo hierarchy, bankable anchor contracts, phased capital expenditure, controlled construction, clear tariffs, currency protection, public-interface remedies, environmental and social plans, digital continuity, controlled accounts, reserves, downside liquidity and a recovery route.
The checklist should show evidence quality and ownership. A document labelled final may still be inadequate if it is unsigned, expired, conditional or inconsistent with the model. The closing data room should contain the executed and reconciled evidence used by the board and lenders.
A platform becomes financeable when rights, cargo, operations and capital reinforce one another. The discipline is to finance the minimum coherent system, prove performance and expand against evidence.
| Test | Approval question | Minimum evidence | Stop condition |
|---|---|---|---|
| Perimeter | Are all critical assets and interfaces controlled? | Asset, rights and interface map | Critical dependency outside executable control |
| Demand | Is opening debt supported by durable cargo? | Contracted and evidenced throughput | Base case relies on speculative cargo |
| Concession | Do rights outlast debt and permit security? | Executed concession and direct agreement | Inadequate tenor, tariff or step-in protection |
| Completion | Can the full route reach commercial operation? | Cost-to-complete, permits and interface testing | Unfunded gap or missing access right |
| Cash | Can revenue be collected and transferred? | Contracts, accounts, currency and waterfall | Material leakage or trapped cash without remedy |
| Downside | Does the structure retain liquidity and control? | Correlated stress model and action plan | Coverage or liquidity below approved floor |
| Sustainability | Are impacts, resilience and obligations funded? | ESMS, permits, resilience plan and budget | Unresolved material impact or unfunded commitment |
| Exit | Can lenders recover or refinance? | Security, step-in, cure and refinancing plan | Recovery depends on unsupported future value |
Each test requires project-specific evidence and professional advice where applicable.
33. Translate the framework into capital-provider decisions
The same corridor produces different decisions for sponsors, governments, development institutions, commercial lenders and long-term investors. A credible financing process gives each party a defined risk layer and an evidence-based reason to accept it. Sponsors should carry development, integration and early commercial risk because they control the project definition and negotiating strategy. Their equity should fund the work required to convert strategic interest into executable rights, contracts and designs. Equity cannot substitute for unresolved authority, inaccessible land or a revenue model that lacks lawful collection rights.
The public authority should focus support on obligations that arise from public control or public benefit. These can include concession certainty, access rights, customs and border coordination, defined tariff processes, connecting infrastructure, resettlement obligations, targeted viability support and transparent compensation when a public action impairs the project. Support should be conditional, measurable and limited to the approved policy purpose. An open-ended revenue promise can weaken operating discipline and create a contingent liability that is difficult to govern. A defined payment mechanism, evidence standard, cap and termination route makes the obligation more financeable and more accountable.
Development-finance institutions can address risks that commercial debt cannot efficiently carry during the early operating period. Their role may include longer tenor, subordinated or blended capital, political-risk mitigation, environmental and social discipline, local-currency solutions, technical assistance and mobilisation of other lenders. The instrument should solve a diagnosed financing constraint. Concessional capital should have a stated additionality case, a measurable development purpose and a route to crowd in commercial capital as the corridor demonstrates performance. The World Bank, Inter-American Development Bank and IFC examples reviewed in this paper show that corridor investment commonly combines physical assets, institutional coordination and operating improvement [3] [8] [11] [19] [20].
Commercial lenders should size debt to controlled cash rather than total strategic value. Their underwriting should test concession life, completion coverage, contracted cargo, collection mechanics, currency mismatch, reserve policy, information rights, security and step-in feasibility. A lender should be able to explain how an adverse operating event becomes a measurable covenant response, a funded cure, a restructuring action or an enforcement route. If the answer depends entirely on sponsor goodwill or future public support, the control architecture remains incomplete.
Institutional investors can enter when construction exposure, demand uncertainty and operating interfaces have reduced to a level consistent with their mandate. Refinancing can replace higher-cost development capital after completion, a stable operating record, audited reporting and demonstrated cash transfer. The transaction should preserve adequate maintenance, resilience and expansion funding. Extracting cash too early can create a superficially attractive distribution while weakening the asset that supports the remaining capital.
Anchor customers also participate in the capital structure through commitments that improve revenue visibility. Their contracts should reflect genuine service value and operating flexibility. Capacity reservations, minimum-volume commitments, deposits, dedicated facilities and service-level remedies can support financing when the customer has authority, credit quality and a credible logistics requirement. Concentration limits, transfer rights, replacement mechanisms and performance conditions protect the platform from becoming dependent on one relationship.
The final approval memorandum should reconcile these decisions in one sources-and-uses table, one risk-allocation matrix, one cash waterfall and one conditions schedule. It should identify the party responsible for each unresolved item, the evidence required, the deadline and the consequence of failure. This turns a broad transaction thesis into a controlled transaction. It also gives the board a basis for refusing capital that carries the wrong currency, maturity, security, control or return expectations for the risk being financed.
Sources
- UN Trade and Development, Review of Maritime Transport 2025, including the port performance and trade facilitation chapter. Read the primary source
- World Bank and S&P Global Market Intelligence, Container Port Performance Index 2025. Read the primary source
- Inter-American Development Bank, Logistics in Latin America and the Caribbean: Opportunities, Challenges and Courses of Action. Read the primary source
- Inter-American Development Bank, Atlas of Integration Infrastructure in Latin America and the Caribbean. Read the primary source
- Inter-American Development Bank, Port-Centric Development: Strategic Logistics Investments. Read the primary source
- World Bank, Port Performance Varies Across the Globe Amid Continuing Shocks, 22 September 2025. Read the primary source
- World Bank PPP Resource Center, Public-Private Partnerships in Ports. Read the primary source
- World Bank PPP Resource Center, Ports Module and risk-allocation guidance. Read the primary source
- International Finance Corporation, Performance Standards on Environmental and Social Sustainability. Read the primary source
- Brazil Ministry of Ports and Airports, 2025 auction results and announced port investment, 2026. Read the primary source
- Brazil Ministry of Ports and Airports, Brazilian ports handled 1.4 billion tonnes in 2025, 2026. Read the primary source
- Colombia Agencia Nacional de Infraestructura, port-mode concession projects. Read the primary source
- Peru OSITRAN, Statistical Bulletin, December 2025. Read the primary source
- Panama Canal Authority, Annual Report 2025. Read the primary source
- Panama Canal Authority, 2025 operational and financial results. Read the primary source
- Brazil National Waterway Transport Agency, Statistical Yearbook 2025. Read the primary source
- Brazil National Waterway Transport Agency, Management Report 2025. Read the primary source
- UN Trade and Development, Shipping data and seaborne trade statistics, 2025. Read the primary source
- World Bank, Logistics Performance Index 2023. Read the primary source
- Colombia Agencia Nacional de Infraestructura, 2024 management report. Read the primary source
- Colombia Agencia Nacional de Infraestructura, public hearing for a proposed 20-year port concession, 2025. Read the primary source
- Brazil Ministry of Ports and Airports, historical port-auction pipeline, 2024. Read the primary source
- Brazil Ministry of Ports and Airports, Tecon Santos 10 public-hearing notice, 2025. Read the primary source
- Brazil Ministry of Ports and Airports, port lease process and public documentation. Read the primary source
- UN Trade and Development, Review of Maritime Transport 2025, chapter 4 PDF. Read the primary source
- World Bank, Container Port Performance Index 2025 annex. Read the primary source
