
Introduction
Launch-company acquisitions combine aerospace engineering, regulated operations, government procurement and project-like cash flow. The buyer is purchasing a system that must manufacture a vehicle, secure a site and range window, integrate a payload, obtain approval, launch safely, place the payload into the contracted orbit and collect cash. Weakness in any stage can defer revenue, absorb capital and damage the target's access to customers or regulators.
The valuation question is therefore narrower than the addressable market for access to space. It asks how much cash a specific target can produce from missions it can lawfully, technically and operationally deliver. The answer requires evidence for cadence, mission reliability, backlog quality, unit economics, remaining development and the buyer's ability to control risk after closing.
1. Define the acquisition thesis
The transaction team should write the acquisition thesis as a set of measurable claims. Examples include acquiring an operational launch service, securing sovereign launch access, integrating launch with spacecraft manufacturing, obtaining propulsion or avionics intellectual property, entering a government procurement channel or accelerating a buyer's vehicle programme. Each claim needs a value mechanism, evidence standard, owner and failure case.
The thesis should identify which cash flows belong to the target on a stand-alone basis and which arise only after integration. Customer revenue, contract margin and working capital belong in the operating case when supported by target evidence. Procurement savings, shared range infrastructure, constellation demand and cross-selling are buyer synergies. Separating them prevents the seller from being paid twice for value created by the buyer.
2. Separate company value from programme value
A launch company can contain an operating vehicle, a vehicle in development, propulsion assets, test facilities, launch-site rights, mission software, payload-integration capability and government qualifications. These assets mature at different rates and should not be valued through one revenue multiple. The operating service can be valued from accepted missions and cash generation. A development programme requires completion cost, schedule and probability adjustments.
Technology option value should be tied to an identified future decision. A reusable stage, larger vehicle or responsive-launch capability can create value if the technical path, customer requirement, funding plan and expected economics are credible. An idea without those components remains an opportunity narrative. The buyer should preserve options through staged funding and governance instead of capitalizing the full forecast at closing.
3. Reconstruct verified flight history
The diligence team should rebuild every attempted flight, static-fire campaign and integrated test from primary evidence. Record vehicle configuration, authorised activity, launch site, scheduled window, actual event, payload, target orbit, achieved result, anomaly, customer acceptance and corrective action. CAA licence registers and operator notices provide a public starting point; telemetry, test reports, customer certificates and regulator correspondence provide transaction-level evidence. [2][3][8]
Evidence should be grouped by configuration and operating site. A suborbital test, captive carry, stage firing or flight using an earlier propulsion and avionics stack does not establish orbital service maturity. A successful demonstration establishes technical progress while commercial value depends on repeatability, payload acceptance, schedule performance and the cost of delivering the result. The valuation model should state the exact evidence population used for each reliability or maturity conclusion.
4. Measure cadence as repeatable throughput
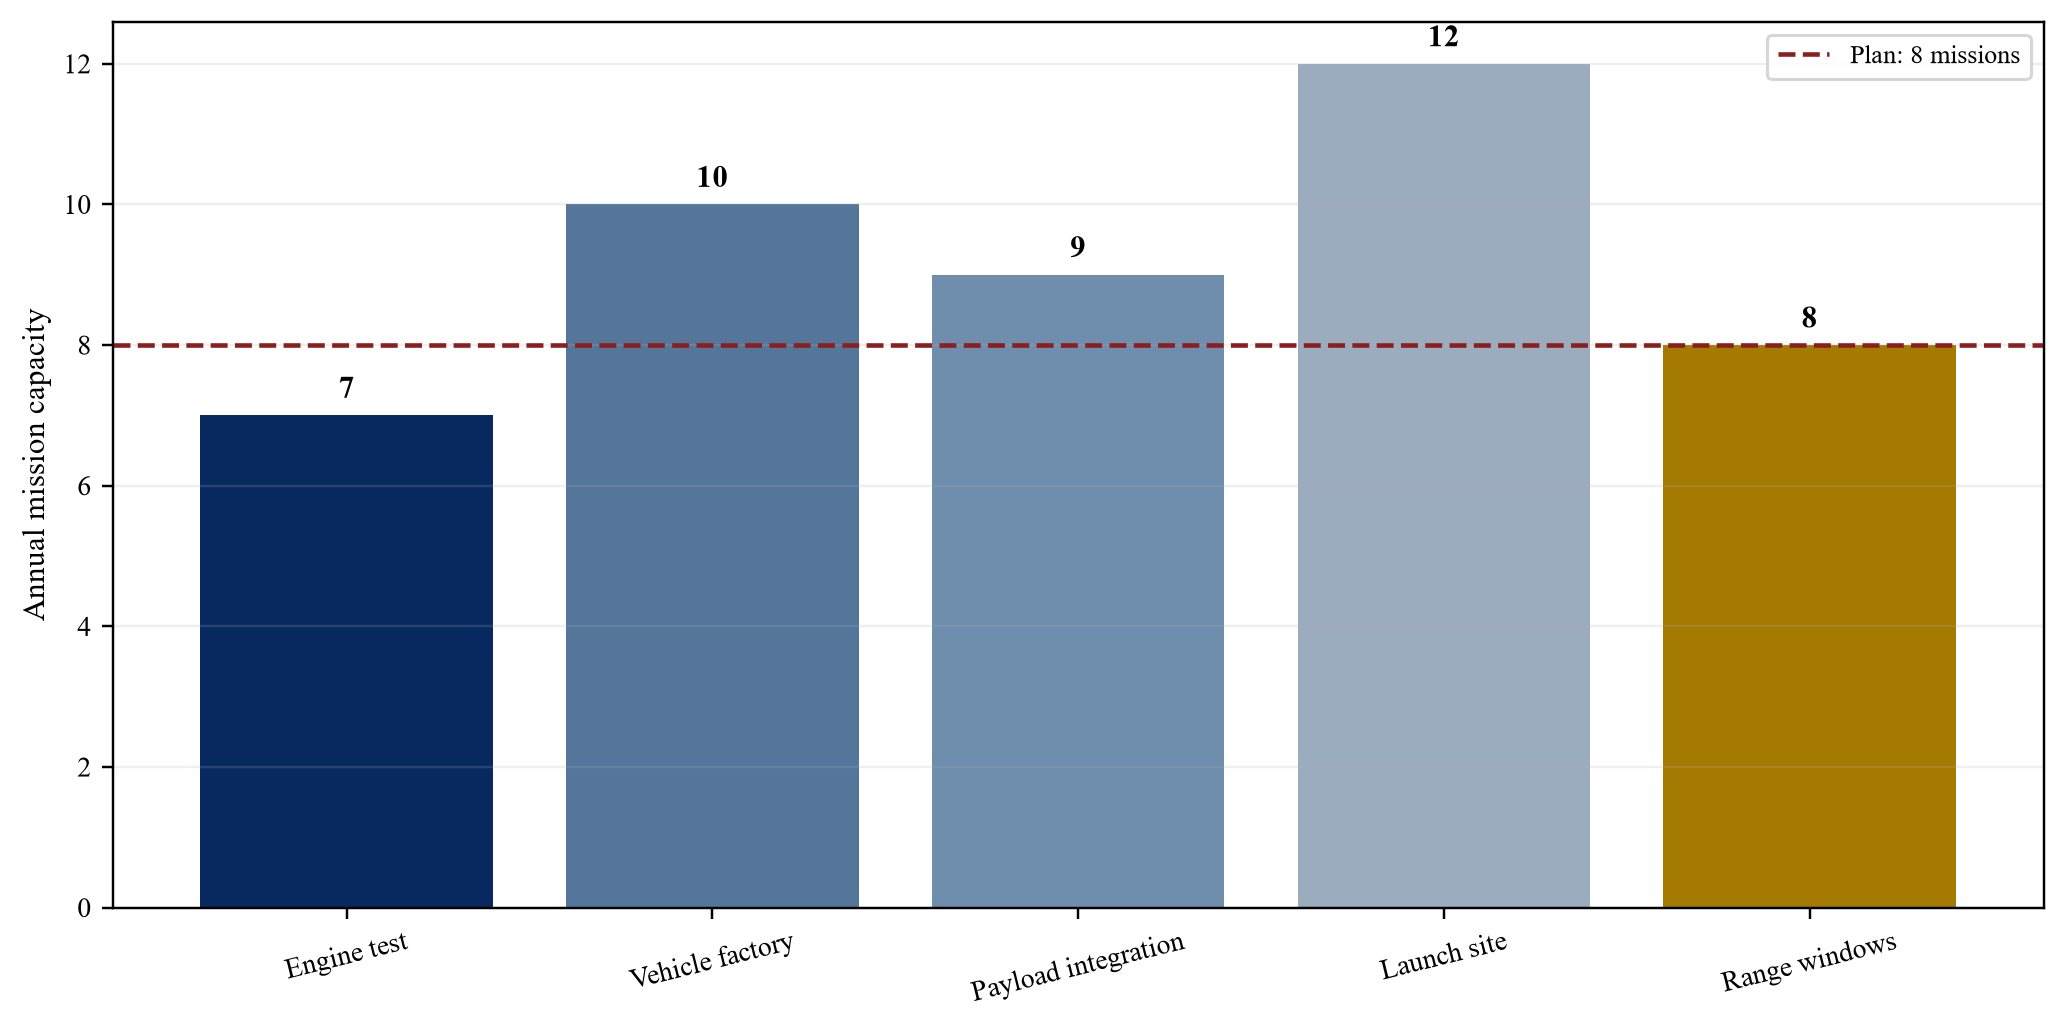
Cadence is the number of completed and accepted missions the full operating system can sustain. It depends on vehicle production, engine supply, test capacity, payload readiness, range access, licensing, launch-site operations, weather, mission engineering and customer decisions. A launch calendar that ignores these constraints is a sales plan rather than a capacity model.
Measure scheduled-to-actual variance, turnaround time, work in process, manufacturing cycle, engine-test throughput, launch-site occupancy and causes of delay. Separate target-controlled delay from customer, range and weather delay. Both affect cash timing, while remediation differs. Cadence receives valuation credit after repeated delivery across representative missions, sites and operating conditions.
5. Underwrite reliability and learning
Mission reliability is both a technical probability and a commercial condition. Customers may require mission assurance, insurance, specific flight heritage or additional oversight. The CAA licensing framework requires safety evidence for the authorised activity, while the Pathfinder Launch Lessons Learned report shows the number of public and private interfaces involved in a launch from UK soil. Regulatory permission and one completed campaign still require transaction-level testing of the vehicle configuration and operating system. [2][8][10]
The buyer should inspect failure-mode analysis, qualification evidence, non-conformance records, telemetry, supplier escapes and closure of corrective actions. Learning has economic value when it produces fewer defects, less rework, shorter cycle times or better mission performance. Experience measured only as elapsed calendar time or cumulative engineering hours should not receive the same credit.
6. Classify backlog by enforceability
Backlog should be reconstructed contract by contract. Record signed value, funded amount, customer options, deposits, termination rights, refund rights, launch windows, price escalation, performance conditions, cancellation payments, assignment restrictions and change-of-control consent. The buyer should reconcile this schedule with the general ledger, deferred revenue, invoices, cash receipts and customer confirmations.
The register should distinguish launch-service commitments from engineering, payload-integration, grant and development income. It should also separate minimum customer obligations from options, forecast missions and maximum framework values. This contract-level definition prevents a broad commercial pipeline from being presented as committed launch revenue.
7. Verify government backlog
Government opportunity ranges from policy intent and market engagement to an awarded contract with appropriated funds and a named mission. The diligence team should obtain the notice, tender, award, executed contract, modifications, call-off orders, funding evidence, statement of work, delivery schedule, termination provisions and performance record. Contracts Finder and Find a Tender can corroborate procurement status; the executed instrument and customer confirmation determine economic treatment. [16][17][18]
Sovereign demand also depends on payload readiness, security requirements, mission assurance, compatible orbit, procurement timing and launch-policy choices. The UK Space Strategy describes assured access as a national capability and targets frequent domestic orbital activity by 2030. These goals establish strategic relevance. They do not identify a particular operator's funded orders. The base valuation should include only demand supported by executable contracts, while policy-linked opportunities remain probability-weighted scenarios. [4][5]
8. Distinguish frameworks from funded orders
A framework establishes contractual machinery for later competitions or call-offs. It may identify qualified suppliers, pricing rules, a maximum value and ordering terms. It does not ordinarily prove that the authority will order the maximum or allocate any specific share to one supplier. The buyer should distinguish guaranteed minimums, funded call-offs, exercisable options, non-binding pipeline and maximum programme value. [16][17]
The same discipline applies to grant-supported demonstrations and letters announcing government support. A grant can fund capability development without creating launch-service revenue. A memorandum can document cooperation without obligating missions. Valuation should follow enforceable scope, funding, acceptance conditions, customer readiness and expected contribution margin. Strategic eligibility can be recorded as an option with a separate probability and remaining bid cost.
9. Test commercial customer quality
Commercial customers vary in credit, mission readiness and financing. A launch contract with a funded satellite programme and completed payload can have greater conversion probability than an agreement with an early-stage constellation still raising capital. Diligence should examine the customer's financing, spacecraft production, regulatory approvals, spectrum position, insurance and launch dependency.
The contract schedule should include customer deposits, milestones and cancellation behaviour. Customer interviews can test launch-date priority, switching alternatives and willingness to accept a different vehicle or window. Revenue scenarios should avoid assuming every customer is ready when the target is ready. A launch company can appear supply-constrained while a material portion of its manifest remains customer-constrained.
10. Map deposits and cancellation rights
Deposits provide evidence of commitment only after their legal and accounting treatment is understood. The buyer should identify whether each amount is refundable, credited against launch price, forfeitable after a date, secured, held in escrow or subject to performance conditions. Cash already spent on vehicle production can create a future delivery obligation without providing future liquidity.
Cancellation clauses should be modelled under customer delay, target delay, mission failure, licensing delay and force majeure. The economic result may include refund, termination fee, replacement flight, priority rebooking or damages cap. These outcomes affect both backlog value and working capital. The quality of a manifest is partly the quality of its cancellation economics.
11. Normalize pricing and mission mix
Headline price per launch can obscure mission-specific services. Price may include payload processing, range support, mission design, separation systems, special studies, schedule priority, responsive-launch capability, insurance or orbital transfer. Normalize each mission to a standard configuration and separately value mission-unique work.
The transaction model should therefore reconcile quoted price with the signed statement of work and the accounting ledger. It should identify whether revenue belongs to launch, integration, engineering, site services or reimbursable items. A consistent mission bridge allows the buyer to compare price, scope, cost and cash contribution across customers and vehicle configurations.
12. Build per-launch unit economics
The buyer should construct cost per accepted mission from bill of material, engine and stage production, direct labour, test, consumables, freight, integration, launch-site operations, range charges, mission-unique engineering, insurance, allocated support and expected rework. Separate recurring cost, fixed operating cost and programme development.
Margin should be reconciled at mission and cohort level. A target may report improving unit cost while shifting development labour, overhead or launch-site expense elsewhere. The model should compare management's standard cost with purchase orders, payroll, inventory movements and actual mission closeouts. Cash contribution matters because revenue recognition can precede or follow mission delivery.
13. Model fixed-cost absorption
Launch businesses carry facilities, engineering, range, safety and programme-management costs that do not move proportionally with missions. Higher cadence can improve absorption if the additional flights use available capacity and do not require another site, factory or shift structure. The model should therefore represent capacity in steps rather than assume a smooth cost curve.
At each cadence level, identify headcount, engine-test slots, stage flow, integration bays, pad occupancy, maintenance windows and supporting capital. A ten-mission plan that needs a second production line should include its completion cost and ramp loss. Fixed-cost absorption creates value after the system passes its next bottleneck.
14. Underwrite engine and vehicle supply
Supply diligence should trace propulsion, structures, avionics, valves, tanks, composite materials, separation systems and controlled components to qualified sources. Record lead times, minimum orders, sole-source exposure, export classification, quality history, tooling ownership, intellectual-property rights and change-of-control provisions.
The buyer should test whether the forecast cadence can be supported by released purchase orders and supplier capacity. A target can hold a large manifest while lacking engines or long-lead components for the scheduled year. Supplier substitution can require redesign, qualification and regulator engagement. Inventory should be assessed for configuration obsolescence and recoverability after programme changes.
15. Assess launch-site and range access
Spaceport access is a package of legal rights, physical capacity, services and scheduling rules. Diligence should inspect the site agreement, pad or integration-area rights, permitted vehicle envelope, range-control allocation, ground-support interfaces, maintenance responsibilities, emergency response, utilities, security, storage, fees, priority rules and termination rights. The CAA licence register confirms regulatory status; it does not confirm the target's commercial access or priority. [2][3][9]
The operating plan should translate annual licensed capacity into usable windows. Weather, trajectory, maritime and airspace coordination, environmental conditions, other operators, maintenance and payload delays can reduce utilisation. The UK Space Strategy states that SaxaVord is approved for up to thirty launches per year. A buyer should use that figure as a site-level regulatory capacity boundary, then evidence the target's contracted share and achievable cadence independently. [4][5]
16. Review manufacturing capacity
Factory capacity should be demonstrated through routing, cycle time, yield and work-in-process. The buyer should walk the production line and reconcile serial numbers, material status, non-conformance, labour bookings and stage completion. Prototype facilities often require different controls to support repeatable production.
Capacity should be modelled at the constraint, which may be engine test, tank production, avionics acceptance, final integration or site logistics. Overall floor area provides limited evidence. The buyer should require a funded debottlenecking plan, supplier commitment and quality controls before valuing the higher cadence case.
17. Test schedule realism
An integrated master schedule should connect engineering release, supplier delivery, manufacturing, qualification, licensing, site readiness, payload availability, range windows and customer milestones. Each critical path needs an accountable owner and evidence of duration. Schedule reserve should reflect maturity and historical variance.
The transaction model should preserve date-specific cash effects. A launch delayed across a fiscal period can change revenue recognition, milestone receipts, working capital and covenant compliance. Multiple missions relying on the same unresolved qualification test should be treated as correlated rather than independent.
18. Evaluate licences and regulatory approvals
The CAA regulates UK commercial spaceflight under the Space Industry Act 2018 and the Space Industry Regulations 2021. Separate permissions can apply to launch or return operations, spaceports and range-control services. The buyer must determine which entity holds each permission, what vehicle, location and activity it covers, and which changes require regulatory engagement. [1][2][3][8]
The legal data room should contain licences, applications, safety cases, assessment-of-environmental-effects materials, security evidence, financial-responsibility arrangements, monitoring records and regulator correspondence. Counsel should assess change of control, key personnel, ownership, insurance and licence-condition consequences. A licensed spaceport and a licensed operator remain separate links in the delivery chain; the transaction case should model both.
19. Review mishaps and corrective actions
Incident diligence should cover flight failures, test events, pad damage, near misses, safety occurrences and material quality escapes. The UK's Pathfinder Launch Lessons Learned report describes coordination and regulatory learning from the first orbital launch attempt from UK soil. Transaction diligence requires the underlying technical record: telemetry, causal analysis, corrective actions, independent review, requalification and acceptance by the responsible authority. [10]
Regulatory closure does not by itself establish economic closure. A corrective action may increase mass, reduce payload, extend inspection, change a supplier or consume future test inventory. The buyer should update mission performance, cadence, unit cost, insurance and liquidity for every material action. Shared causes across vehicle, site and range should be treated as correlated risks.
20. Verify sovereign demand
Sovereign value arises when domestic launch improves the availability, timing, security or resilience of missions that government is prepared to procure. The 2026 UK Space Strategy presents assured access as a national-security requirement and combines domestic polar and sun-synchronous capability with trusted international partnerships. It also describes planned support for SaxaVord, subject to due diligence. [4][5][6]
The buyer should translate that policy into evidence at operator level. Required evidence includes funded missions, framework eligibility, payload readiness, service specifications, mission-assurance requirements, security accreditation and realistic procurement dates. A strategic premium belongs in buyer-specific synergy only when the acquirer can capture it through identifiable contracts, avoided delay, protected downstream revenue or a funded capability requirement.
21. Review investment screening and export controls
Space and launch transactions can engage the National Security and Investment Act 2021. Government guidance explains that acquisitions in defined sensitive areas can require mandatory notification and that completing a notifiable transaction without approval can make it void and expose parties to penalties. Counsel should map the target's activities, control rights, assets, ownership and timetable before signing. [19][20]
Launch vehicles, propulsion, guidance, software and technical data can also be controlled under UK strategic export rules and international collaboration arrangements. Diligence should classify items and technology, identify licences and end users, restrict access through clean teams and review foreign-person participation. The purchase agreement and integration plan should preserve required licences, security measures and operational separation.
22. Assess intellectual-property control
The buyer should map patents, trade secrets, source code, design files, test data, manufacturing know-how, government rights, university licences, employee assignments and supplier licences. Ownership of a vehicle design can be less valuable if the target lacks rights to essential tooling, software or technical data.
Government funding can introduce data-rights regimes that differ by contract. Open-source components and commercial software require licence review. The integration plan should protect restricted data while allowing the buyer to operate, improve and support the acquired system. Technology value should be reduced where rights are incomplete, disputed or dependent on a departing individual.
23. Test insurance and liability
The Space Industry Act framework addresses operator liability, indemnification and insurance. The buyer should inspect licence conditions, insurance policies, exclusions, deductibles, aggregation, customer indemnities, cross-waivers, government indemnification terms and claims history. Coverage should be tested against the actual vehicle, site, payload, trajectory and mission profile. [1][11][12]
Liability allocation affects both enterprise value and closing structure. A low-probability event can exceed annual premium and impair access to a site or licence. The model should include premium, deductible, uninsured exposure, replacement mission cost and cash timing. The transaction documents should allocate pre-closing incidents, disclosure failures and known remediation through warranties, indemnities, escrow and specific covenants.
24. Model working capital and cash conversion
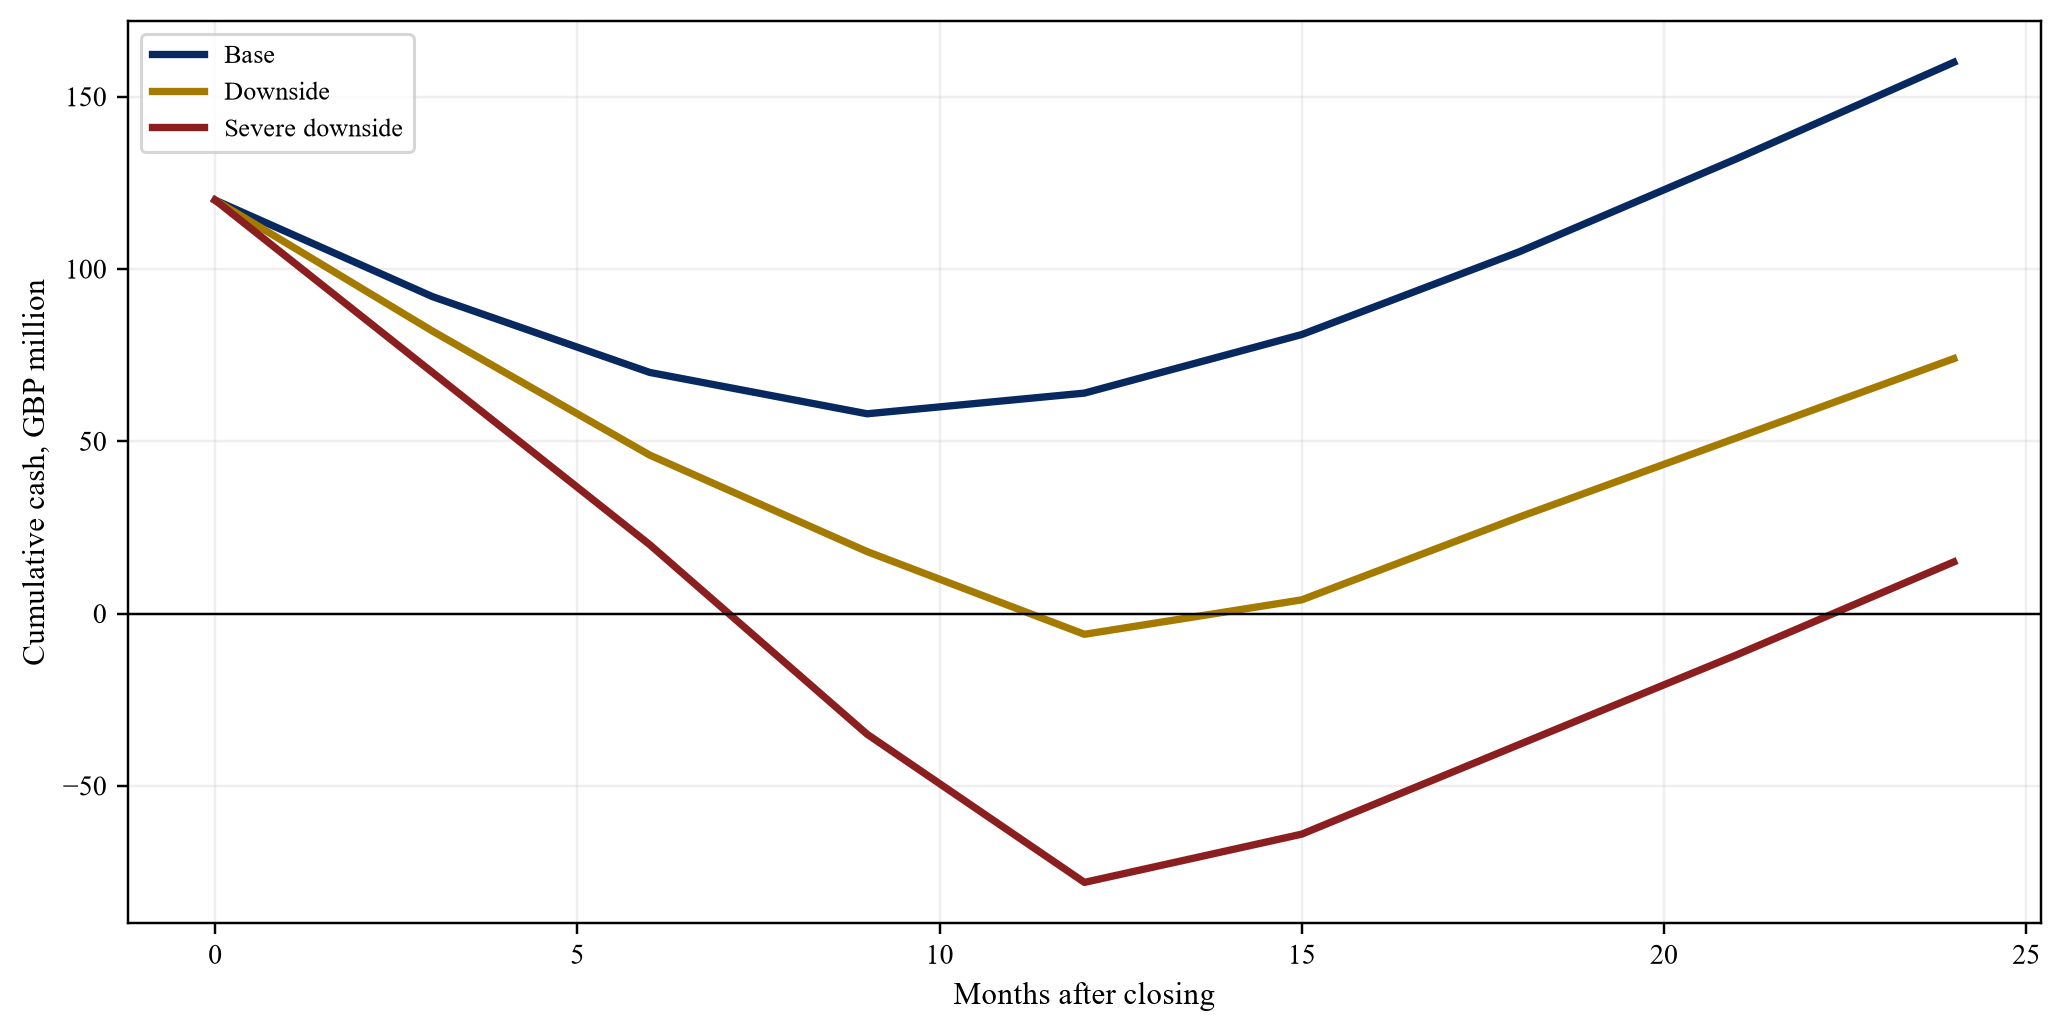
Cash conversion depends on deposits, milestone billing, long-lead purchases, inventory build, payroll, customer acceptance and refund exposure. The buyer should construct a mission-level cash curve from signing through launch and final acceptance. Aggregate annual EBITDA can hide a liquidity trough before a high-cadence period.
Deferred revenue should be reconciled with delivery obligations. Customer cash spent on development may leave the buyer responsible for future launches. Payables extended beyond supplier terms can flatter liquidity and threaten supply. Completion funding belongs in the purchase-price bridge or committed financing plan.
25. Fund remaining development and completion
Remaining development capital should be estimated through an engineering-based cost-to-complete, not a percentage of historic spend. Work packages should cover design closure, hardware, testing, qualification, software, sites, licences, mission assurance, contingency and working capital. The estimate should identify dependencies and schedule confidence.
GAO's Technology Readiness Assessment Guide and UK Space Agency's Systems Engineering Handbook provide useful structures for evaluating maturity, evidence and system integration. They do not determine transaction value. The acquirer should connect maturity gaps to specific spend, milestone, probability and commercial consequence. [19][20]
26. Value government relationships carefully
Government relationships create value through lawful capabilities: qualification, delivery performance, cleared facilities, secure systems, procurement eligibility and trusted execution. Policy references, meetings and announcements provide context while funded orders, accepted deliverables and repeat awards provide stronger economic evidence. The buyer should map each relationship to an institutional process rather than an individual.
Sovereign-access value should be calculated from an identifiable benefit to the buyer, such as an executable mission pipeline, avoided overseas-launch delay, protected satellite revenue or access to a funded programme. The value should remain in synergy when it depends on the buyer's assets, procurement position or integration. A separate probability should reflect policy change, budget timing, competing providers and allied launch alternatives.
27. Value technology options separately
A target may offer options in reusability, medium-lift vehicles, in-space transport, hypersonics, defence responsiveness, manufacturing services or propulsion sales. Each option should be framed as a staged decision with remaining spend, time, technical evidence, customer evidence and strategic fit.
The buyer can use a probability-weighted present value or real-options framework. Both require disciplined assumptions. Base enterprise value should not include a full forecast for every concept. Consideration can be linked to qualification, flight, funded order or margin milestones so that seller proceeds rise as evidence improves.
28. Apply evidence-weighted valuation
The valuation should triangulate mission contribution, discounted cash flow, comparable companies, precedent transactions, replacement cost and strategic option value. Multiples require normalization for vehicle maturity, service mix, backlog definition, capital intensity, government concentration and accounting policy. A space-systems company with launch operations is not directly comparable to a pure launch provider.
Fair-value and impairment standards provide general principles for market-participant assumptions, cash-generating units and identifiable intangibles. Transaction teams should apply the relevant accounting framework with advisers and auditors. [28][29][30]
29. Construct the hypothetical transaction
The hypothetical target owns a small-launch vehicle programme and has contracted access to a licensed UK spaceport. It reports GBP 240 million of stated backlog. Contract review identifies GBP 75 million of firm funded orders, GBP 70 million of framework or ceiling capacity, GBP 55 million of customer options and GBP 40 million of letters of intent or unsupported pipeline. Applying illustrative weights of 85%, 25%, 35% and 10% produces GBP 104.5 million of economic backlog before delivery cost.
The base operating case increases cadence from two missions in Year 1 to eight in Year 4. Fully absorbed cost per accepted mission declines from GBP 22 million to GBP 12 million as vehicle production, test utilisation, launch operations and fixed support improve. The case assumes an average realised mission price of GBP 18 million in Year 1 and GBP 20 million in Year 4, with mission mix and service scope explaining the change. These figures are hypothetical.
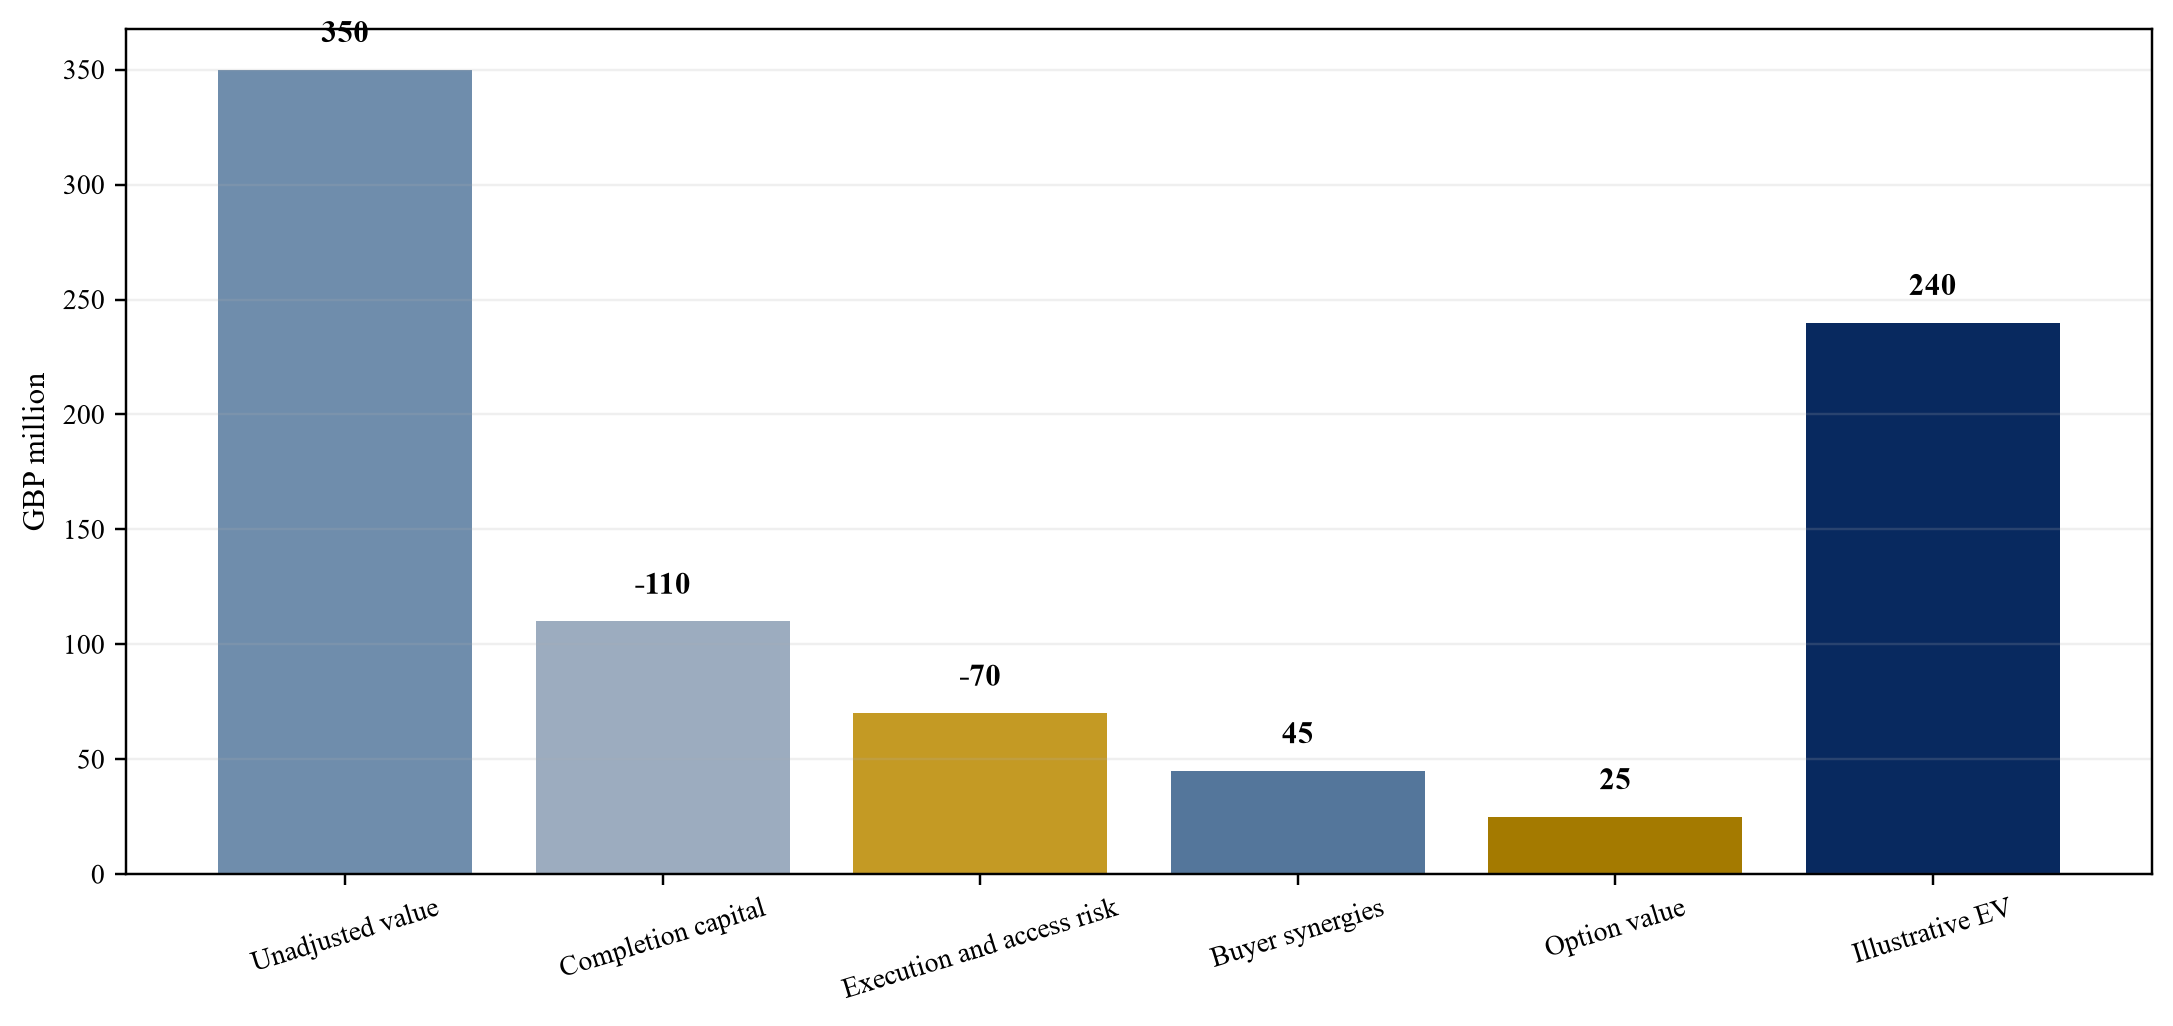
An unadjusted present value of GBP 350 million is reduced by GBP 110 million of remaining development and completion capital and GBP 70 million of execution, spaceport-access, customer-readiness and compliance risk. It is increased by GBP 45 million of buyer-specific sovereign and industrial synergies and GBP 25 million of probability-weighted technology option value. The resulting illustrative enterprise value is GBP 240 million. No identified company, contract, licence or forecast is represented.
30. Stress cadence cost and backlog
The first sensitivity holds economic backlog at GBP 104.5 million and varies Year 4 cadence. At four missions, fixed site, range and engineering costs remain thinly absorbed and terminal value falls sharply. At six missions, contribution improves while the programme still carries concentration risk. At eight missions, the base case reaches its planned operating point. A ten-mission case requires fresh evidence for manufacturing, windows, payload readiness and working capital.
The second sensitivity reduces evidence-weighted backlog by 20% and increases remaining completion capital by 25%. The combined downside affects revenue timing, liquidity and value more than either input alone. The board should examine a severe case in which a flight anomaly delays two missions, triggers corrective-action spend and causes customer cancellation. Financing must cover the trough without depending on unsigned orders.
31. Structure consideration and protection
Closing consideration can reflect verified operating assets and funded backlog. Deferred consideration can follow named milestones such as licence approval, successful flight, required reliability, funded order, customer acceptance or gross margin. Milestones should be objective, within defined control and protected against deliberate diversion of resources.
Representations should address backlog, contracts, licences, export controls, security, intellectual property, product performance, incidents and financial records. Escrow, indemnity, warranty insurance and specific covenants can allocate identified risk. The buyer should also reserve sufficient capital to complete the plan; reducing price without funding completion can still destroy the asset.
32. Plan integration before signing
Integration planning should protect mission delivery from Day One. The buyer should define authority for flight safety, engineering change, customer commitments, government communication, supplier release, cash control and incident response. Critical personnel and cleared teams need retention and governance that preserves lawful independence where required.
The integration plan should sequence systems, finance, procurement and commercial changes around launches. Disrupting configuration control or supplier approvals near a mission can create disproportionate risk. Synergies should have owners, costs, timing and customer safeguards. The first objective is continuity of safe contracted service.
33. Define the acquisition decision
The investment committee should receive a concise decision record. It should state the acquisition thesis, verified flight and cadence evidence, risk-adjusted backlog, unit economics, completion capital, regulatory conditions, downside liquidity, transaction protections, integration readiness and value range. Open matters should have owners and closing conditions.
Approval should specify which claims are accepted and which remain conditional. The decision can distinguish closing value, milestone value and strategic option value. This structure preserves upside while preventing aspirational manifest and technology narratives from entering the base price without evidence.
Conclusion
Launch-company valuation becomes tractable when the transaction team follows the evidence chain from customer mission to accepted launch and collected cash. Cadence requires a repeatable production, regulatory and range system. Reliability requires configuration-specific flight and corrective-action evidence. Government backlog requires funded orders and executable scope. Technology options require staged capital and explicit probability.
The proposed framework converts those principles into a diligence schedule, unit-economic model, downside case and transaction structure. Buyers can use price, milestones, escrow, indemnities and committed completion capital to align consideration with evidence. Sellers can increase value by producing a clean flight record, enforceable backlog schedule, reconciled mission economics and a credible path through the next operating constraint.
The most useful diligence output is a common evidence model used by engineers, commercial teams, finance, legal advisers and the investment committee. It should preserve the provenance of every material assumption and show how a change in mission readiness, licensing, cadence, reliability or customer funding affects cash and value. This discipline supports faster decisions because disagreements become specific and testable. It also gives the post-closing team a practical control system for capital allocation, customer commitments and integration. A launch transaction can then be priced around what the system has demonstrated, funded around what remains to be completed and protected against the events that could interrupt safe delivery.
Appendix A. Flight and cadence checklist
Reconstruct every mission by configuration, site, scheduled window, actual date, payload, target orbit, achieved result, customer acceptance and anomaly. Reconcile the operating forecast with vehicle work in process, engine-test capacity, supplier releases, site windows, licence scope and payload readiness.
The schedule should show the source and review date for each fact. Flight evidence should distinguish regulatory outcome, customer outcome and internal engineering outcome because the three can differ. A payload can reach an orbit outside its original tolerance, a vehicle can complete a test objective without completing a customer mission, and a regulator can require additional action after an event. Record each conclusion in the terms used by the responsible authority or customer. For cadence, calculate the interval between completed missions, planned-to-actual variance, pad occupancy, rework and the proportion of delay controlled by the target. Reconcile the next twelve months of missions with serialized hardware and customer payload status.
Appendix B. Backlog checklist
For every agreement, record funded amount, contract ceiling, minimum guarantee, task order, option, deposit, cancellation right, launch window, price escalation, change-of-control consent, customer readiness and expected gross margin. Confirm material balances with customers and accounting records.
The contract schedule should connect legal rights to accounting and cash. For each line, include recognized revenue, deferred revenue, billed receivable, collected cash, remaining performance obligation and estimated fulfilment cost. Identify agreements that share one customer financing event, satellite factory or regulatory approval because apparent diversification may be illusory. Government entries should show appropriation, obligation and issued order separately. Commercial entries should record the customer's payload, financing, licence and launch-alternative status. The buyer should require written explanations for every difference among stated backlog, accounting backlog, funded order value and the risk-adjusted economic schedule.
Appendix C. Technical and regulatory checklist
Review configuration control, qualification, telemetry, failure analysis, corrective actions, software, cyber security, intellectual property, export classification, licences, environmental approvals, site agreements, insurance and government security. Link each issue to cost, schedule and transaction protection.
Configuration control should establish which drawings, software, materials and processes produced each flight article. The qualification matrix should distinguish analysis, component test, subsystem test, integrated test and flight evidence. For each open waiver or deviation, identify approving authority, affected missions and expiry. The regulatory schedule should show current approval, pending action, responsible counsel and the operating consequence of delay. Export-control diligence should limit access before sensitive data enters the deal room. Cyber review should cover development environments, mission systems, supplier access and incident response. Every red item should result in a priced remediation, a closing condition, a covenant or a specific decision to accept the exposure.
Appendix D. Financial checklist
Build mission-level revenue, cash collection, recurring cost, fixed cost, development spend, working capital and replacement obligations. Reconcile management forecasts with source records. Present base, downside and severe-downside liquidity with committed funding.
The model should preserve both calendar timing and vehicle cohort. Revenue and cash should follow contract milestones, including refunds and replacement-flight obligations. Cost should follow purchase orders, labour routing, test slots and site activity. Development work should be separated from recurring production even when the same engineers perform both. Forecast improvements require a named mechanism such as yield, labour learning, supplier pricing or asset utilization. Each mechanism should have a starting observation, target, implementation cost and accountable owner. The acquisition bridge should show debt, cash, leases, customer deposits, provisions and cost to complete. Liquidity should include minimum operating cash and covenant headroom rather than only ending cash.
Appendix E. Transaction checklist
Separate stand-alone value, buyer synergy and technology option value. Define closing conditions, regulatory filings, representations, escrow, indemnities, milestone consideration, retention and integration governance. Assign each material risk to a contract term or funded operating response.
The definitive agreement should identify the evidence date for backlog and major operational representations. Between signing and closing, ordinary-course covenants should govern new launch contracts, price concessions, customer refunds, supplier commitments, engineering changes, incidents and regulator communication. The buyer should decide how milestone consideration is treated when a customer or regulator delays an event outside seller control. Integration governance should name the authority for flight safety and engineering release, preserving technical independence from short-term financial pressure. Retention should focus on roles and documented knowledge transfer. A closing checklist should confirm that committed completion funding, insurance and operating liquidity are available on Day One.
The board paper should include a one-page claim register. Each material value claim should point to its contract, flight record, cost schedule or independent confirmation. The register should state who verified the claim, when it was verified, what remains open and which valuation line depends on it. This makes the acquisition decision auditable and helps the integration team preserve the assumptions that justified the price.
Appendix F. Decision figures and tables
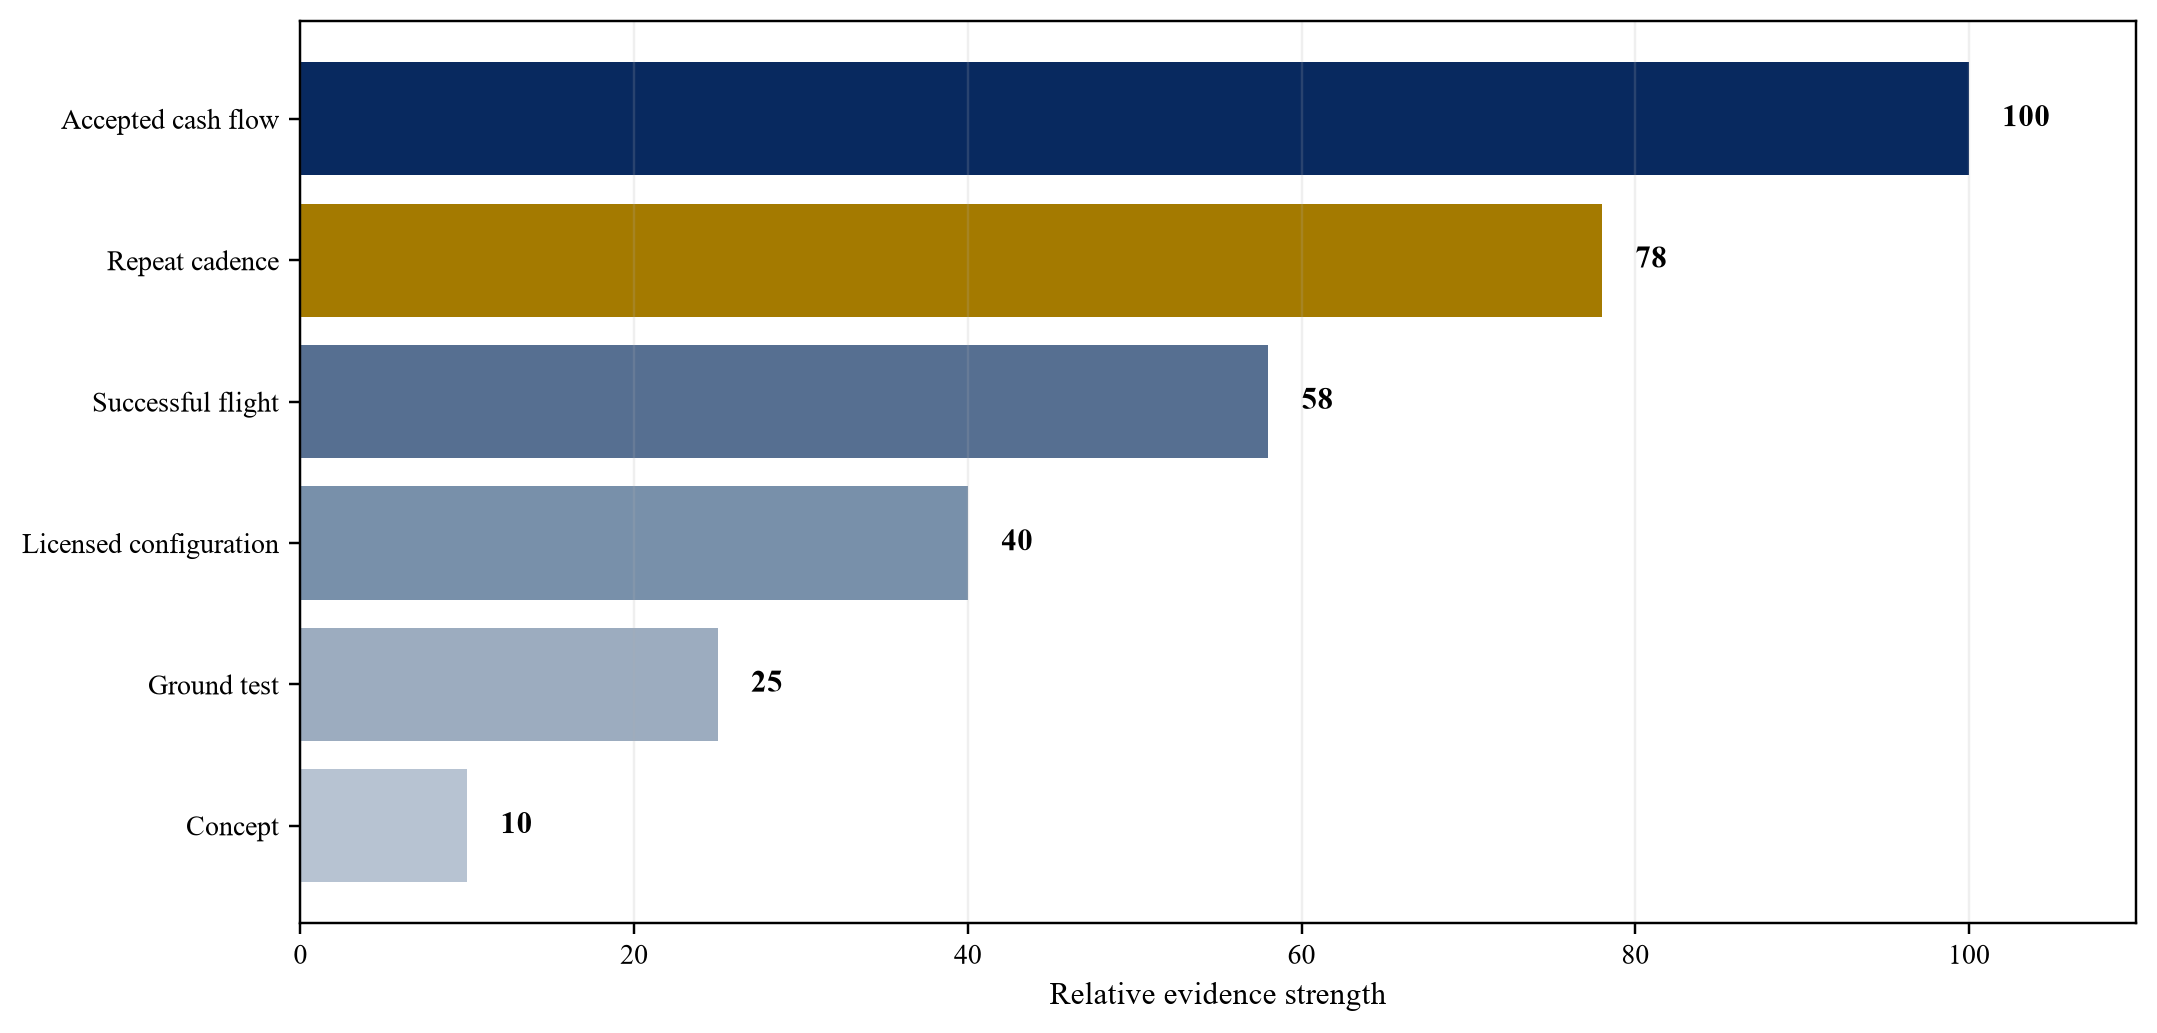
Proposed transaction framework; higher levels require stronger verification.
| Category | Required evidence | Base-case treatment |
|---|---|---|
| Funded firm order | executed order, funding and mission scope | include with delivery probability and margin |
| framework or framework ceiling | base vehicle and minimum guarantee | include only minimum and issued orders |
| Customer option | exercisable terms and customer readiness | scenario probability outside contracted base |
| Letter of intent | non-binding expression and conditions | pipeline only |
| Internal forecast | sales estimate without customer obligation | exclude from backlog |
Proposed evidence treatment.
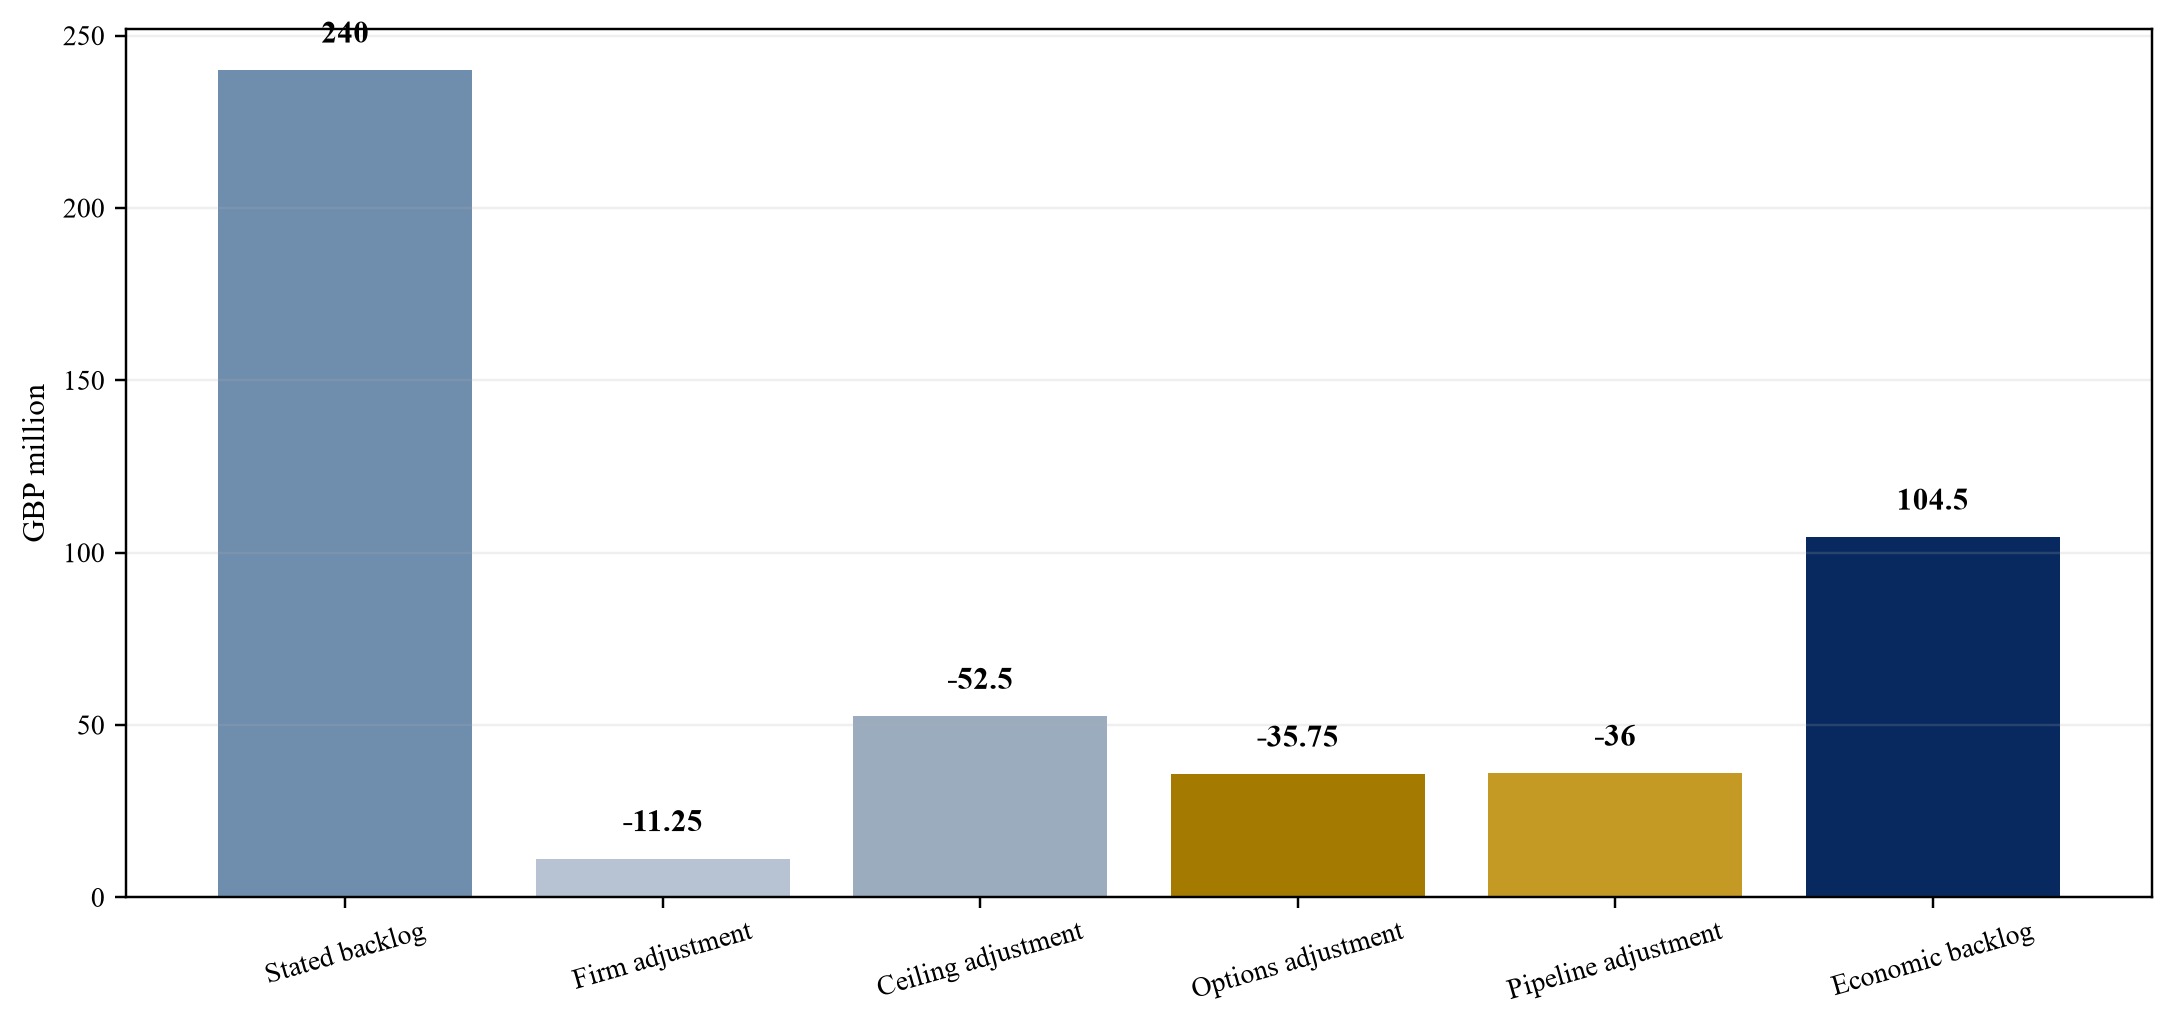
Wholly hypothetical; GBP million.
| Instrument | What it proves | What it does not prove |
|---|---|---|
| Framework appointment | eligibility and ordering mechanism | future call-offs up to the ceiling |
| Guaranteed minimum | binding minimum obligation | full programme share |
| Funded call-off | defined scope and committed funding | automatic follow-on work |
| Option | contractual right to order | exercise or appropriation |
| Public announcement | agency intent and context | executed terms and collected cash |
Proposed contract review.
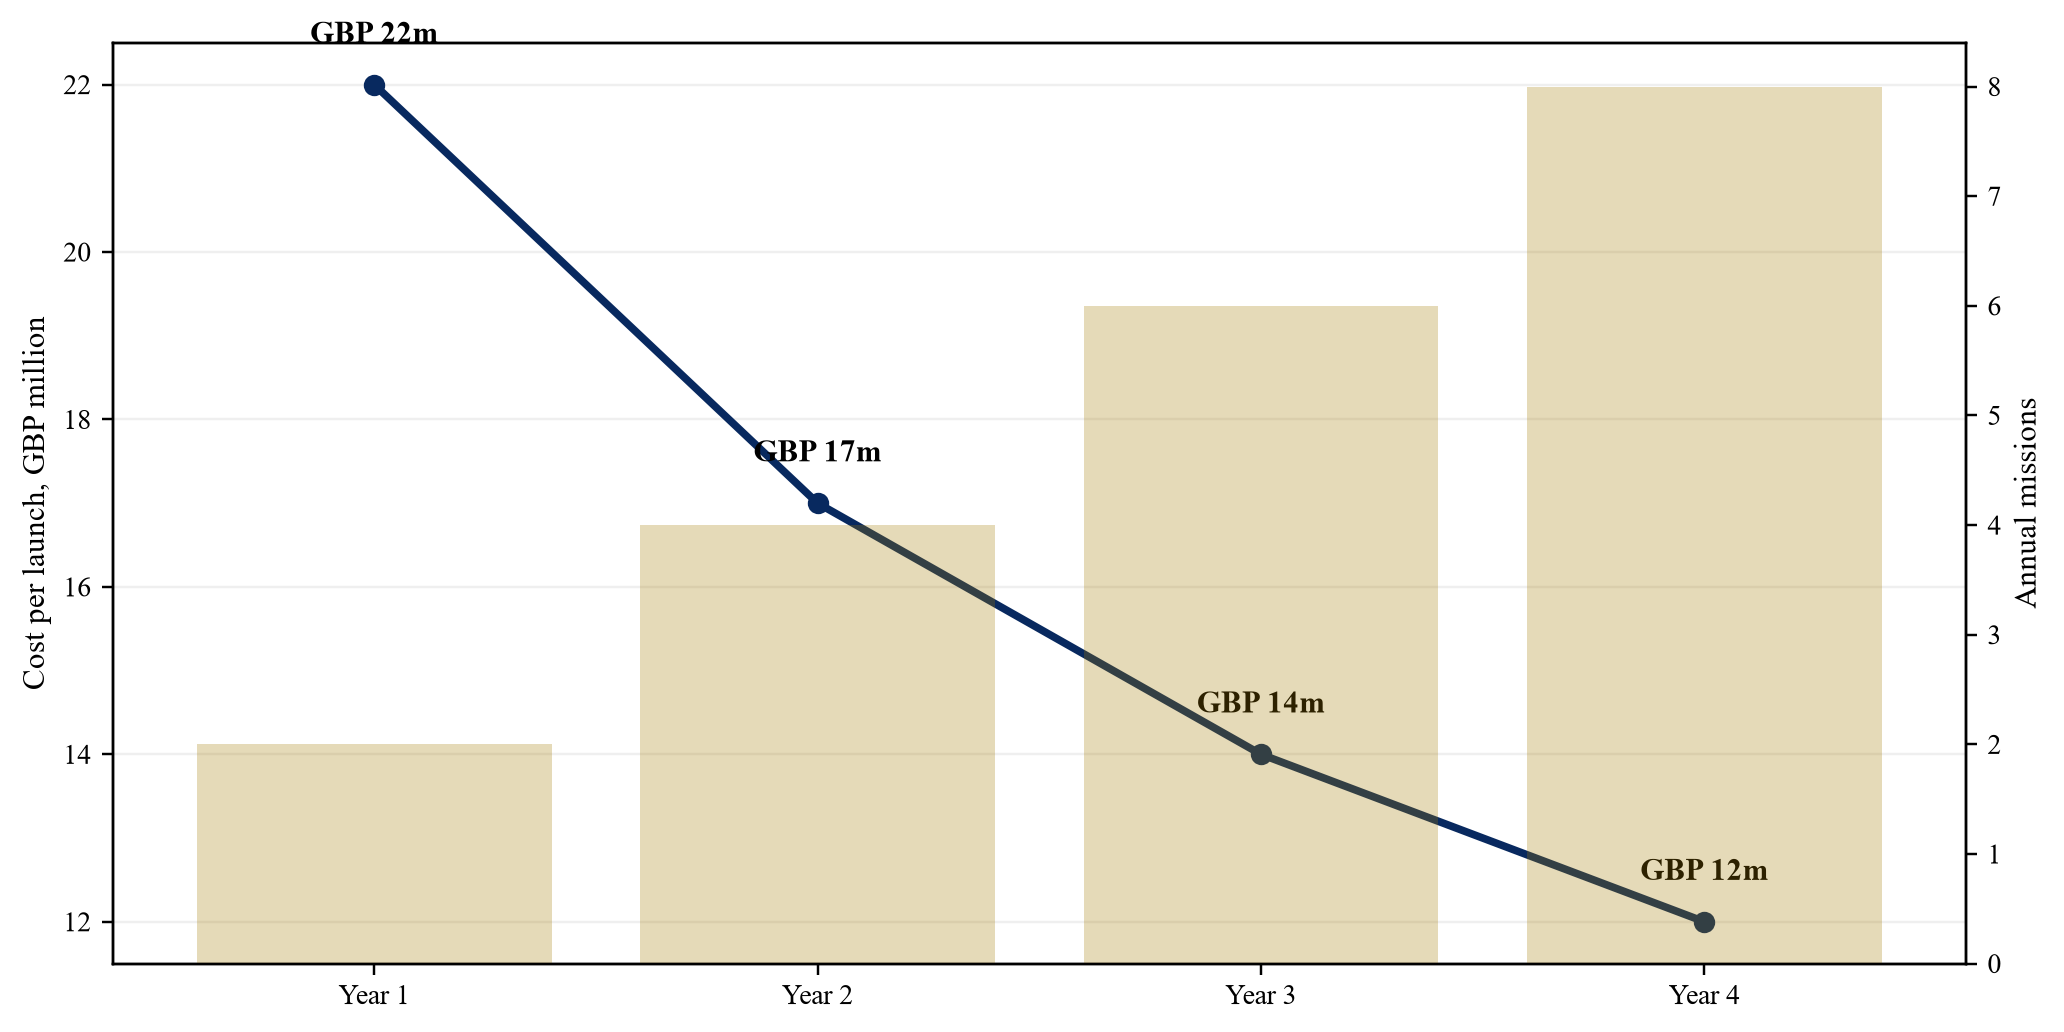
Wholly hypothetical annual missions and GBP million fully absorbed cost per launch.
| Cost component | Year 1 | Year 4 | Evidence |
|---|---|---|---|
| Vehicle hardware and engines | 11.0 | 7.0 | purchase orders and build records |
| Direct labour and test | 4.0 | 2.0 | payroll and routing |
| Range and launch operations | 3.0 | 1.5 | site and service agreements |
| Mission engineering and integration | 2.0 | 0.8 | mission closeout |
| Allocated fixed support | 2.0 | 0.7 | capacity and cost ledger |
Hypothetical cost build for diligence.
Wholly hypothetical missions per year by principal operating constraint.
| Area | Principal question | Evidence |
|---|---|---|
| CAA permissions | which operator site range and activities are covered | licences and correspondence |
| Mishap history | are corrective actions verified and costed | investigation and return-to-flight record |
| Export control | who may access hardware software and data | classification and licences |
| NSI Act | does ownership or control trigger notification or review | counsel analysis and filing record |
| Security | can cleared programmes continue after closing | facility and personnel approvals |
Proposed workstream.
Wholly hypothetical; GBP million.
| Uncertainty | Structure | Verification event |
|---|---|---|
| Licence scope | closing condition | approved configuration and site |
| Development completion | milestone consideration | qualification and successful flight |
| Backlog conversion | earnout | funded order and collected cash |
| Reliability | escrow or milestone | defined mission-success record |
| Compliance | representation and indemnity | clean regulatory and export review |
Proposed allocation of evidence risk.
Wholly hypothetical cumulative cash after acquisition in GBP million.
| Criterion | Investable evidence | Red flag |
|---|---|---|
| Cadence | repeat missions supported by capacity | calendar without bottleneck proof |
| Reliability | configuration-specific flight and closure | pooled or incomplete success record |
| Backlog | funded executable orders | ceilings and letters presented as revenue |
| Economics | reconciled mission cash contribution | unsupported cost curve |
| Completion | funded work packages and schedule | percentage uplift without engineering basis |
| Control | licences security and integration plan | unresolved change-of-control dependency |
Proposed approval framework.
| Decision item | Required conclusion | Owner |
|---|---|---|
| Strategic thesis | defined stand-alone and synergy value | deal sponsor |
| Technical evidence | accepted configuration and maturity | chief engineer |
| Commercial evidence | risk-adjusted backlog and customer readiness | commercial lead |
| Financial case | value range completion funding and downside liquidity | chief financial officer |
| Regulatory clearance | CAA export control NSI Act and security path | general counsel |
| Integration | Day-One continuity and milestone governance | integration lead |
Proposed board output.
Sources
- UK Parliament, Space Industry Act 2018. Read the primary source
- UK Civil Aviation Authority, Getting started with licensing. Read the primary source
- UK Civil Aviation Authority, Licences granted and registers of space objects. Read the primary source
- UK Government, UK Space Strategy. Read the primary source
- UK Government, UK Space Strategy Technical Delivery Annex. Read the primary source
- UK Government, New space strategy will bolster UK defences against threats from space. Read the primary source
- UK Space Agency, Annual Report and Accounts 2025 to 2026. Read the primary source
- UK Government, Spaceflight activities rules and regulations. Read the primary source
- UK Civil Aviation Authority, Spaceport licensing. Read the primary source
- UK Space Agency, Pathfinder Launch Lessons Learned report. Read the primary source
- UK Government, Guidance on liabilities insurance and charging for spaceflight activities. Read the primary source
- UK Parliament, Space Industry Regulations 2021. Read the primary source
- UK Space Agency, Size and Health of the UK Space Industry 2024. Read the primary source
- UK Space Agency, UK space sector factsheet. Read the primary source
- UK Government, National Space Strategy in Action. Read the primary source
- UK Government, Find a Tender service. Read the primary source
- UK Government, Contracts Finder. Read the primary source
- UK Parliament, Procurement Act 2023. Read the primary source
- UK Government, National Security and Investment Act guidance on acquisitions. Read the primary source
- UK Parliament, National Security and Investment Act 2021. Read the primary source
- UK Government, UK strategic export controls. Read the primary source
- UK Parliament, Export Control Order 2008. Read the primary source
- Competition and Markets Authority, Merger Assessment Guidelines. Read the primary source
- IFRS Foundation, IFRS 13 Fair Value Measurement. Read the primary source
- IFRS Foundation, IAS 36 Impairment of Assets. Read the primary source
- IFRS Foundation, IAS 38 Intangible Assets. Read the primary source
- HM Treasury, The Green Book. Read the primary source
- UK Ministry of Defence, Defence Space Strategy. Read the primary source
- European Space Agency, Boost Commercial Space Transportation Services and Support. Read the primary source
- UK Government, Space Industrial Plan. Read the primary source
