
1. Define the de-risking dividend
The de-risking dividend is the economic value created when verifiable project risks fall after construction and initial operations. It can appear through a lower credit spread, longer tenor, smoother amortisation, reduced reserve requirements, release of sponsor support, broader lender access or a lower probability of financial distress. The value exists only when new financing terms improve the project after transaction costs and retained risks.
World Bank guidance explains that construction lenders usually require higher pricing because completion can be late, over budget or technically deficient, while operations-phase lenders can price a project after material development risks have reduced [1]. Rating methodologies also analyse construction and operations through different risk modules [2][3]. The financing committee should therefore document the specific evidence that supports a new credit view.
The decision should be stated as a choice among executable routes: retain or amend bank debt, refinance with operating-phase bank debt, place long-dated institutional debt, issue a project bond, or combine these sources. Each route must be compared on all-in cost, resilience, flexibility, execution certainty, governance burden and lifecycle fit.
A lower headline coupon does not prove that value has been captured. Fees, hedge termination, reserve funding, consent payments, tax, gain-sharing and new restrictions can absorb the apparent benefit. The board needs a reconciled value bridge from risk release to cash benefit and from cash benefit to stakeholder allocation.
2. Use a four-gate refinance system
The Construction-to-Operations Refinance System uses four approval gates. Gate One confirms that completion risk has closed to the standard required by the project contracts and prospective financiers. Gate Two proves that operating cash flow is sufficiently stable and explainable. Gate Three establishes that the proposed terms convert risk reduction into durable financing value. Gate Four tests whether the transaction preserves resilience and allocates value lawfully.
Gate One requires acceptance certificates, performance tests, permits, insurance, defect arrangements, contractor security and resolution of material claims. Gate Two examines availability, output, demand, tariff application, collections, operating costs, maintenance, working capital and cash flow available for debt service.
Gate Three covers route selection, lender or investor appetite, rating analysis where relevant, legal structure, hedging, reserves, covenants, tax, accounting and execution. Gate Four compares the executed proposal with credible alternatives, tests severe downside cases, confirms public-authority and contractual consents, and calculates any required refinancing-gain sharing.
Each gate should identify the required evidence, owner, decision authority and stop condition. A project can pass physical completion while failing the operating-evidence gate. A financially attractive structure can fail the resilience gate if it removes too much liquidity or relies on refinancing at maturity.
3. Build a risk-release ledger
The risk-release ledger is the core evidence record. It lists each material construction risk, the original allocation, the evidence of closure, any surviving exposure and the financing consequence. The ledger prevents the board from treating commercial operation as a single event that removes every pre-completion risk.
The project company should map design, site, permit, interface, procurement, cost, schedule, contractor, testing, grid or network connection, environmental, commissioning and performance risks. Each item should link to the contract, certificate, report, claim register, insurance position and independent technical conclusion that supports its status.
Some risks close. Some migrate. A construction-delay risk may end at acceptance, while a performance shortfall can become an operating-cost, availability or warranty risk. A cost overrun can disappear from the build budget yet leave higher debt, deferred maintenance or a contractor dispute. The ledger should show these transitions explicitly.
Prospective financiers can then identify which risk premium has a project-specific basis for reduction. Pricing should not be attributed to completion when the change arises from benchmark rates, market liquidity, sovereign conditions or lender competition. This separation makes the de-risking dividend auditable.
4. Define completion through objective tests
Completion is a contractual and technical state. The project company should reconcile physical completion, provisional acceptance, technical completion, commercial operations and final acceptance across the engineering contract, concession, offtake agreement, operations contract, insurance programme and financing documents.
The evidence should cover performance and reliability tests, output or availability, environmental and safety conditions, permits, punch-list items, liquidated damages, defects, warranties, spare parts, operating manuals, staff readiness and handover of data. World Bank guidance stresses that completion tests should be measurable and tied to the performance capacity required for operations [4].
Independent technical review should state the remaining risk in financial terms where possible. Open items should have an owner, remedy, security, deadline and downside allowance. A material unresolved defect can affect debt capacity even when it does not prevent the asset from operating.
The refinancing should use the strictest relevant completion requirement or explain why another standard is appropriate. A waiver given to meet a financing date can transfer construction uncertainty into the operating capital structure and weaken the expected dividend.
5. Prove the operating record
The operating record should explain how the asset converts physical performance into cash available for debt service. The minimum period depends on the asset, revenue model and seasonality. A contracted availability project may require a shorter observation period than a merchant asset with volatile demand or commodity exposure.
Monthly evidence should cover output, availability, demand, price or tariff, billing, collections, operating expenditure, maintenance, working capital, insurance claims and counterparty performance. Actual results should reconcile to management accounts, bank accounts and the original financing model.
The analysis should separate recurring performance from temporary support. Sponsor advances, deferred maintenance, payment holidays, one-off compensation and favourable working-capital movements can inflate reported coverage. Normalisation should be documented and independently reviewed where it affects debt sizing.
Ramp-up should have an exit criterion. The project may be operational while still below steady-state performance. A refinancing executed during ramp-up should identify which improvements are observed, which are contracted and which remain management assumptions.
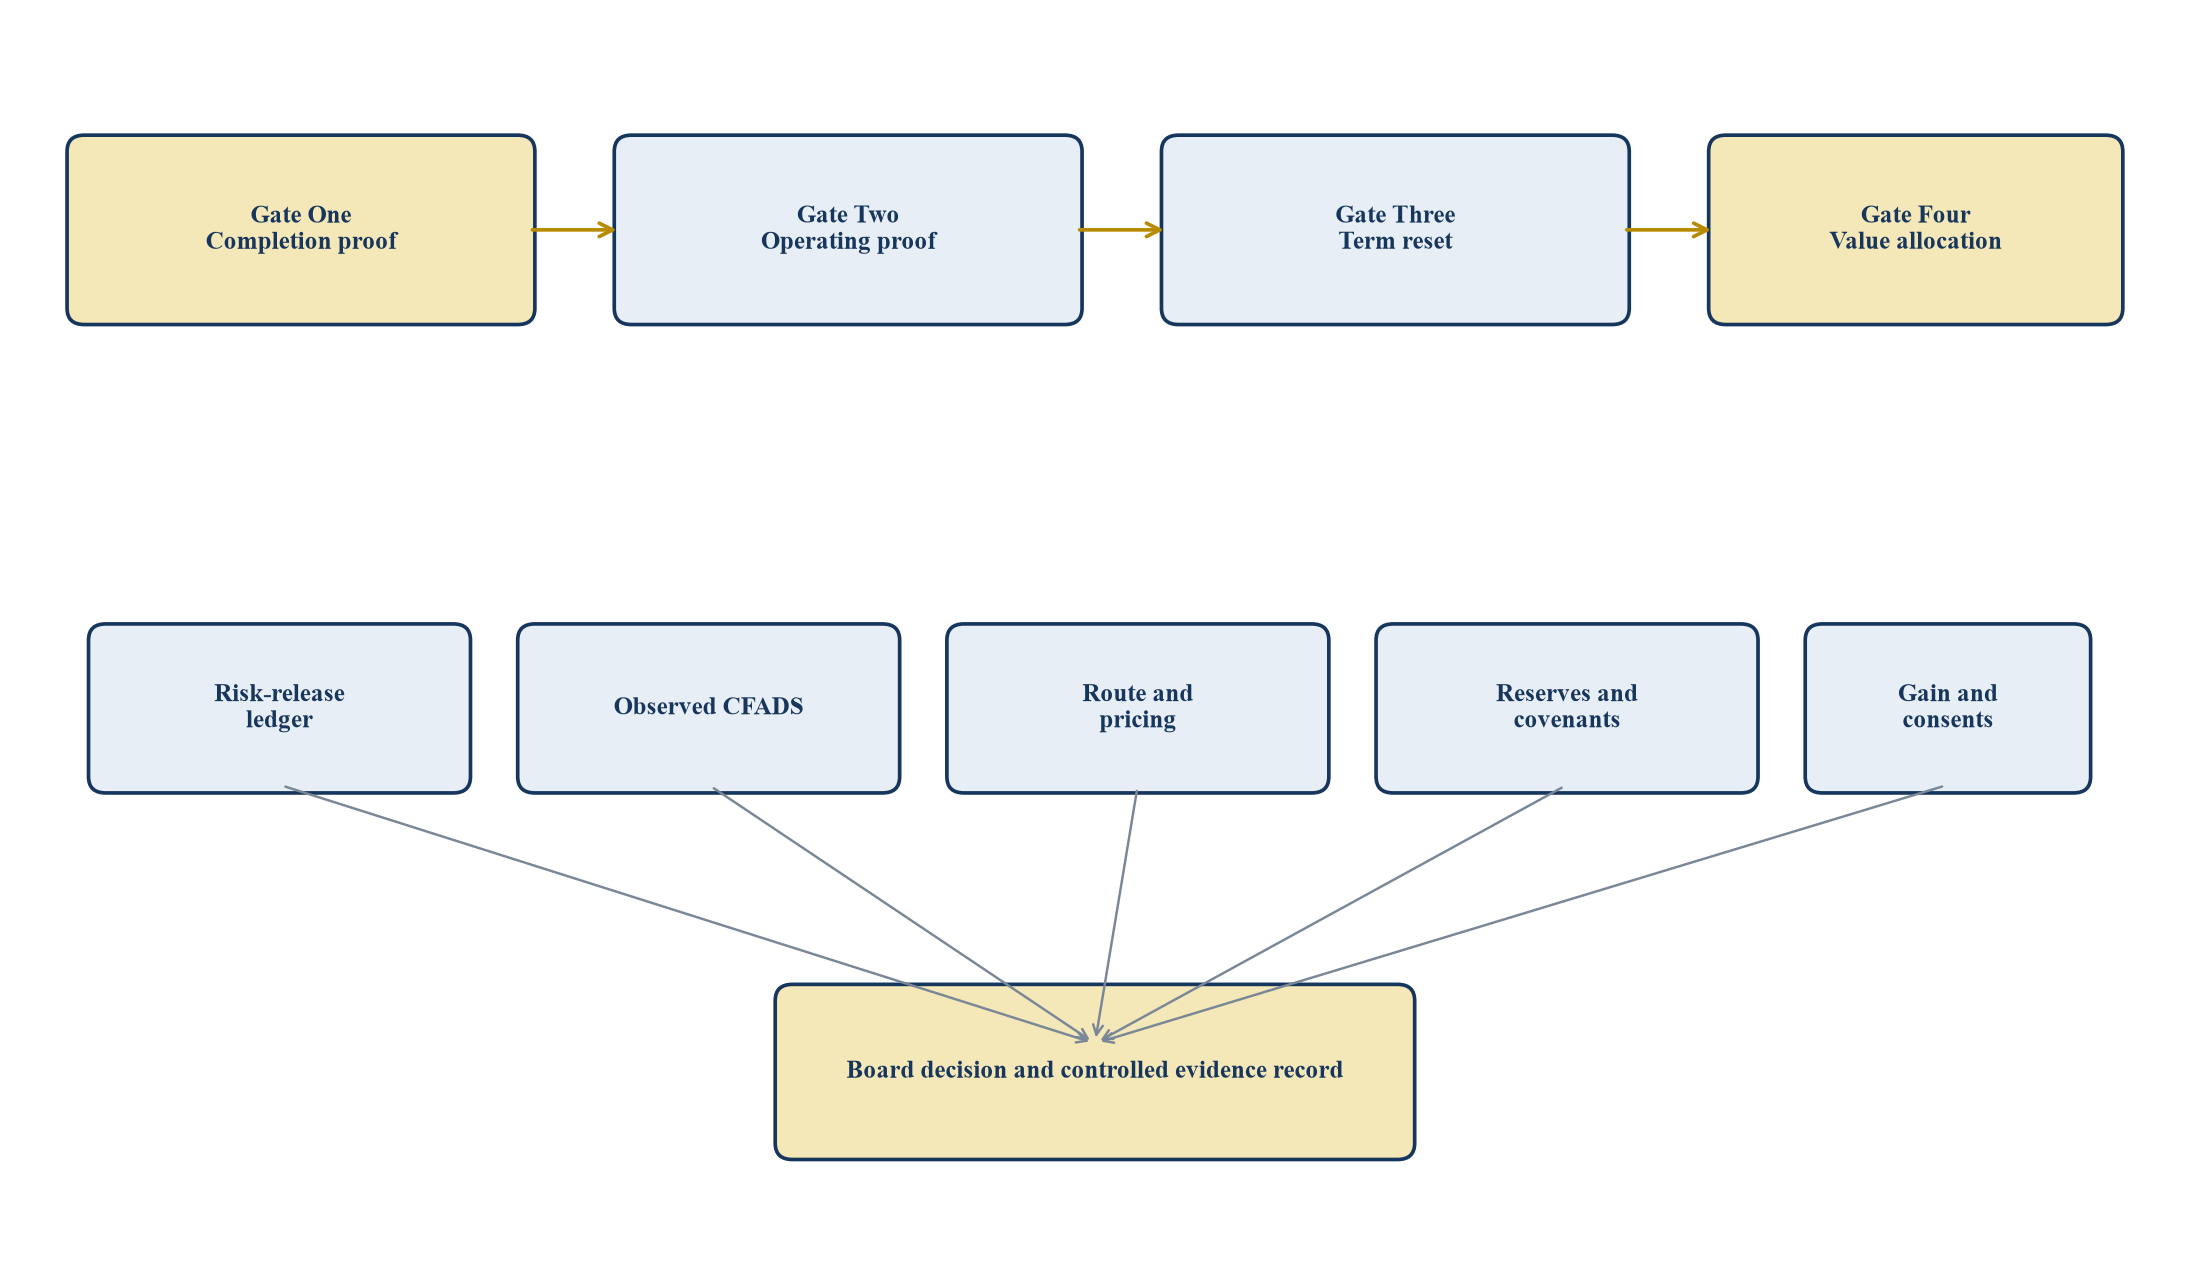
The proposed architecture requires evidence of risk closure and operating stability before financing terms and value allocation are approved.
6. Reconstruct the construction capital stack
The existing financing should be rebuilt from first draw to the proposed repayment date. The schedule should show commitments, drawdowns, capitalised interest, fees, repayments, hedges, reserves, sponsor support, guarantees, waivers and contingent obligations.
This reconstruction identifies the real payoff requirement and the protections that disappear at refinancing. The outstanding principal can understate break costs, accrued interest, swap termination, undrawn fees, reserve replacement, claims and security-release costs. It can also overstate the amount that needs long-term financing when excess cash or released contingencies are available.
The review should distinguish mandatory take-out from elective refinancing. A hard mini-perm, soft mini-perm, bridge-to-bond facility and fully amortising construction loan create different deadlines and bargaining positions. The cost of retaining the existing debt should include margin step-ups, cash sweeps and refinancing obligations.
The capital stack history also shows which parties carried construction risk and how they were paid for it. The board should understand whether the proposed refinancing releases lender capital, sponsor guarantees, contingent equity or trapped cash, because each release has an economic beneficiary.
7. Separate project risk release from market movement
The observed change in financing cost can arise from several sources. Benchmark rates may move, credit spreads may change across the market, sovereign or sector risk may reprice, lender liquidity may improve, and the project may establish stronger evidence. Only the last component is the project-specific de-risking dividend.
The finance team should build a pricing bridge from the original construction financing to the proposed operating financing. It should show benchmark movement, market spread movement, project completion, operating evidence, structural changes, tenor, amortisation, liquidity and transaction-specific negotiation.
The bridge does not require false precision. It requires consistent definitions and documented evidence. Comparable financings, lender feedback, rating analysis and alternative proposals can help estimate the contribution of each component. Ranges should be used when the components cannot be isolated exactly.
This separation matters for governance and contractual gain sharing. A concession authority may treat market gains differently from project-development gains. Sponsors should avoid claiming completion value that was created by falling benchmark rates or public support.
8. Calculate cash flow available for debt service
Cash flow available for debt service should be constructed from operating drivers. The model should connect output or availability, price, indexation, collection, operating cost, tax, maintenance, working capital and reserve movements.
Definitions must match the proposed documents. EBITDA, operating cash flow and cash flow available for debt service are different measures. The model should state permitted adjustments and the treatment of insurance proceeds, compensation, lifecycle expenditure, restricted cash and extraordinary items.
Historical cash flow should reconcile to accounts and bank statements. Forecast improvements should have a contractual, operational or regulatory basis. The model should retain a clear boundary between observed data, approved budgets and management scenarios.
Debt capacity should be constrained by the weakest relevant test: economic resilience, lender or rating capacity, legal limits, concession terms, market capacity and the sponsor's governance standard. Refinancing every available dollar can consume the value created by de-risking.
9. Size the operating debt
The model should calculate annual and minimum debt-service coverage, loan-life coverage, project-life coverage, leverage, reserve adequacy and debt tail. These measures should be tested under central, lender, rating and severe cases.
Operating-phase debt should reflect the asset's remaining life and maintenance burden. A longer tenor can reduce annual debt service while increasing total interest and limiting future flexibility. A shorter tenor can preserve optionality while creating refinancing exposure.
The board should identify which assumption controls debt capacity. For an availability asset, operating cost and deduction risk may dominate. For a demand asset, volume and tariff can drive coverage. For a resource or merchant project, price, basis and curtailment can matter more than completion.
Debt sizing should leave a defensible resilience buffer. The buffer is part of the de-risking dividend because it converts improved credit quality into lower distress risk rather than immediate distributions.
10. Choose the operating-phase route
The route comparison should include amended bank debt, new bank term debt, institutional loans, private placements and project bonds. Hybrid structures can combine bank liquidity with long-dated institutional capital.
Bank debt can provide amendment flexibility, revolving facilities and relationship support. Institutional loans can offer long tenor and bespoke documentation. Private placements can provide execution discretion and concentrated investor dialogue. Public project bonds can broaden funding and create market access while requiring ratings, disclosure and continuing surveillance.
The comparison should use common cash-flow assumptions and a common valuation date. Each route should show net proceeds, all-in financing cost, tenor, amortisation, reserves, hedging, covenants, consents, execution probability, prepayment flexibility and recurring governance cost.
| Gate | Required evidence | Decision owner | Stop condition |
|---|---|---|---|
| Completion proof | Certificates, tests, permits, defects, claims and independent technical conclusion | Board and technical committee | Material construction exposure remains unallocated or unquantified |
| Operating proof | Reconciled performance, collections, CFADS, maintenance and counterparty record | Investment and finance committees | Cash flow remains unstable or depends on temporary support |
| Term reset | Route comparison, lender feedback, rating case where relevant, covenants and reserves | Financing committee | No executable structure creates a defensible net benefit |
| Value allocation | Downside resilience, consents, gain sharing, distributions and retained-risk analysis | Board | Leverage or value extraction weakens lifecycle resilience |
The evidence and stop conditions require transaction-specific legal, technical, financial and regulatory review.
11. Design reserves and liquidity
Reserves should respond to the project's actual interruption risks. A debt-service reserve can cover temporary revenue or operating disruption. Major-maintenance, lifecycle, tax, insurance and working-capital reserves may be required separately.
The design should specify target size, permitted form, funding date, draw conditions, replenishment priority, permitted investments and replacement rules. Cash, letters of credit and surety products have different accessibility, counterparty and repayment characteristics.
Liquidity should be modelled through the payment waterfall. A reserve funded at closing can reduce net proceeds; a reserve built from future cash flow can weaken early protection. A letter of credit can reduce trapped cash while adding renewal and bank-counterparty risk.
The committee should examine correlated draws. An operating failure can reduce revenue, increase cost, trigger maintenance and require reserve replenishment at the same time.
12. Preserve the security package
Project-bond investors rely on ring-fenced cash flows, assets, contracts, accounts and shares. The refinancing should confirm that security can be transferred, recreated or released and retaken without a gap.
The legal review should cover asset ownership, concession rights, assignment restrictions, account control, share pledges, direct agreements, step-in rights, enforcement, insolvency, intercreditor terms and perfection requirements in every relevant jurisdiction.
S&P identifies a bankruptcy-remote limited-purpose entity and a security package over project cash flows and assets as critical attributes of project-finance debt [7]. The bond structure should preserve these fundamentals unless the rating and investor case explicitly supports another approach.
Closing mechanics should sequence payoff, security release, new security perfection, reserve funding and bond settlement. A detailed funds flow and conditions-precedent tracker reduces execution risk.
13. Reconcile concession and public-authority rights
PPP and concession projects often require authority consent to refinancing, security changes, lender replacement, hedging or distributions. The project company should identify every consent, notice, review period and information requirement.
Global Infrastructure Hub guidance notes that refinancing can change pricing, tenor, leverage, reserves, guarantees, security, repayment, lender identity and covenants. The authority should assess financial integrity, value for money and contingent liabilities [8].
The contract may require refinancing gains to be shared. The calculation can depend on a defined base case, discount rate, excluded transactions and the form of benefit. The issuer should model the gain-share before launching the transaction.
Authority approvals should be on the critical path. Delayed consent can cause missed market windows, committed-cost leakage or failed hedging. Governance should identify who owns the relationship and escalation.
14. Treat the rating as a structured workstream
A rating is an independent credit opinion based on methodology, evidence and committee judgement. The issuer should appoint a rating-workstream leader and maintain a response log for information requests, assumptions and sensitivities.
The rating case should test construction residuals, operations, revenue, counterparties, country and currency risk, debt structure, liquidity, recovery and refinancing risk. It should reconcile to the financing model while preserving methodology-specific adjustments.
The committee should examine rating headroom. A structure that achieves a target rating only through a narrow assumption or temporary support can be vulnerable to downgrade. The model should show which variables drive category migration.
Rating feedback can lead to structural change. The issuer should maintain decision authority over leverage, amortisation, reserves and covenants rather than allowing the target rating to become an unexamined objective.
15. Select the financing route
The principal routes include public bond, private placement, loan refinancing and hybrid structures. A public bond can provide scale and investor breadth; a private placement can offer confidentiality, execution control and negotiated terms; bank debt can preserve amendment flexibility.
ICMA's infrastructure-financing guide compares bank loans, private placements and public bonds, including mechanics, credit review, enhancement, investor base, marketing, pricing and disclosure [9]. The route should be chosen through a weighted decision matrix.
Criteria can include tenor, amount, currency, rating, disclosure, liquidity, execution timetable, amendment process, investor concentration and recurring reporting cost. The weights should reflect the project's strategy and not be adjusted to favour a preferred product.
A dual-track process can preserve competition. It requires careful control of confidential information, adviser roles, fees and decision dates.
16. Build a credible investor proposition
Investors need a clear explanation of the asset, contracts, cash-flow drivers, risks, mitigants, governance and debt structure. The presentation should make the credit legible without oversimplifying uncertainty.
The investor proposition should explain why construction risk has reduced, how operating evidence supports the model, which risks remain and how the structure protects debt service. It should also explain the sponsor's continuing economic interest and operating capability.
Institutional investors often value long-duration assets that match liabilities, while they require reliable information, fair pricing and credible partners. World Bank PPP guidance notes that poorly prepared projects can fail to attract pension capital even where infrastructure bonds offer duration and spread [10].
Marketing should record questions, concerns and indicated demand. Repeated investor concerns can reveal structural weaknesses that require action before pricing.
17. Use credit enhancement selectively
Credit enhancement can improve rating or investor access through subordinated debt, guarantees, contingent facilities, reserve support or anchor investment. It also creates cost, conditions, counterparty exposure and possible control rights.
The EIB describes funded subordinated tranches and unfunded first-demand guarantees as forms of project-finance credit enhancement. Its framework requires ring-fenced project assets and assesses viability, procurement, concession, credit, financial and legal issues [11].
The committee should compare the incremental funding benefit with the full enhancement cost and restrictions. The model should show economics with and without support, together with the rating and market-access effect.
Enhancement should address a specific weakness. Broad support can mask an unresolved operating or structural problem and leave the project exposed when support expires.
18. Align currency and hedging
The refinancing should map revenue, operating cost, capital expenditure, debt service and reserves by currency. Bond denomination should follow economic cash flow and investor access rather than presentation convenience.
Foreign-currency debt can create convertibility, transfer, basis and collateral risk. The World Bank's work on exchange-rate risk describes a Colombian infrastructure refinancing that combined local and foreign-currency tranches to align financing with concession cash flows [12]. This example illustrates matching principles rather than a universal structure.
Existing swaps may carry break gains or costs. Replacement hedges can require collateral, ratings triggers and termination payments. The committee should model these amounts at several market dates.
Hedge governance should specify counterparty limits, permitted instruments, collateral, replacement, reporting and authority. A hedge should reduce identified risk without introducing an unmanaged liquidity obligation.
19. Evaluate sustainable-finance eligibility
Operational infrastructure can qualify for green, social, sustainability or other labelled financing when the use of proceeds, project evaluation, proceeds management and reporting meet the relevant framework.
ICMA's Green Bond Principles support financing and refinancing of eligible projects and emphasise transparency, disclosure, proceeds tracking and reporting. The 2025 edition also references enabling activities and updated guidance [13].
The issuer should establish eligibility from evidence rather than from the asset's broad sector label. It should define financed assets, look-back period, allocation process, exclusions, external review and impact metrics.
A label should not weaken credit analysis. Bondholders remain exposed to project cash flow and structure. Misaligned claims can create legal, reputational and market risk.
20. Measure the de-risking dividend
The dividend should be measured as the present value of financing and support improvements after all transaction costs and adverse changes. The calculation should include interest, fees, amortisation, hedging, reserves, guarantee releases, contingent equity, tax, accounting effects and gain sharing.
The hypothetical case assumes USD 900 million of construction debt and an USD 860 million operating refinancing. The existing all-in cash rate is 7.00 percent. The proposed operating debt begins at 5.40 percent, amortises over seventeen years and incurs USD 25.8 million of transaction, break and consent costs. The refinancing also releases USD 18 million of excess construction reserves, while USD 12 million is retained in operating reserves. These are management assumptions for illustration only.
On opening principal, the 1.60 percentage-point rate difference equals USD 13.76 million of first-year gross interest reduction. That figure is not the dividend. The model must deduct fees, incorporate the amortisation schedules, test benchmark and spread sensitivity, and value changes in reserve, guarantee and refinancing risk.
The board should receive both a project-value result and a cash-liquidity result. A positive net-present-value outcome can still create near-term cash pressure if fees and reserve funding occur before savings. The transaction should also be evaluated after any public-sector or contractual sharing mechanism.
21. Test the dividend under downside cases
The hypothetical model compares four cases. The central case assumes USD 108 million of annual cash flow available for debt service and the proposed 5.40 percent operating debt. The ramp-up case assumes a ten percent cash-flow reduction for two years. The operating-shock case assumes a twenty percent reduction for one year and a seven percent persistent reduction thereafter. The market-delay case assumes refinancing occurs twelve months later at an all-in rate 0.75 percentage points higher.
The central case produces the strongest coverage and net benefit. The ramp-up case tests whether refinancing is premature. The operating-shock case tests the reserve, lock-up and cure architecture. The market-delay case shows the value of readiness and the cost of an execution window moving against the project.
The model should also test a lower debt amount, faster amortisation and larger reserve. A smaller refinancing can produce a lower immediate distribution while preserving more of the de-risking dividend as credit resilience. The board should compare those alternatives rather than assume maximum proceeds are optimal.
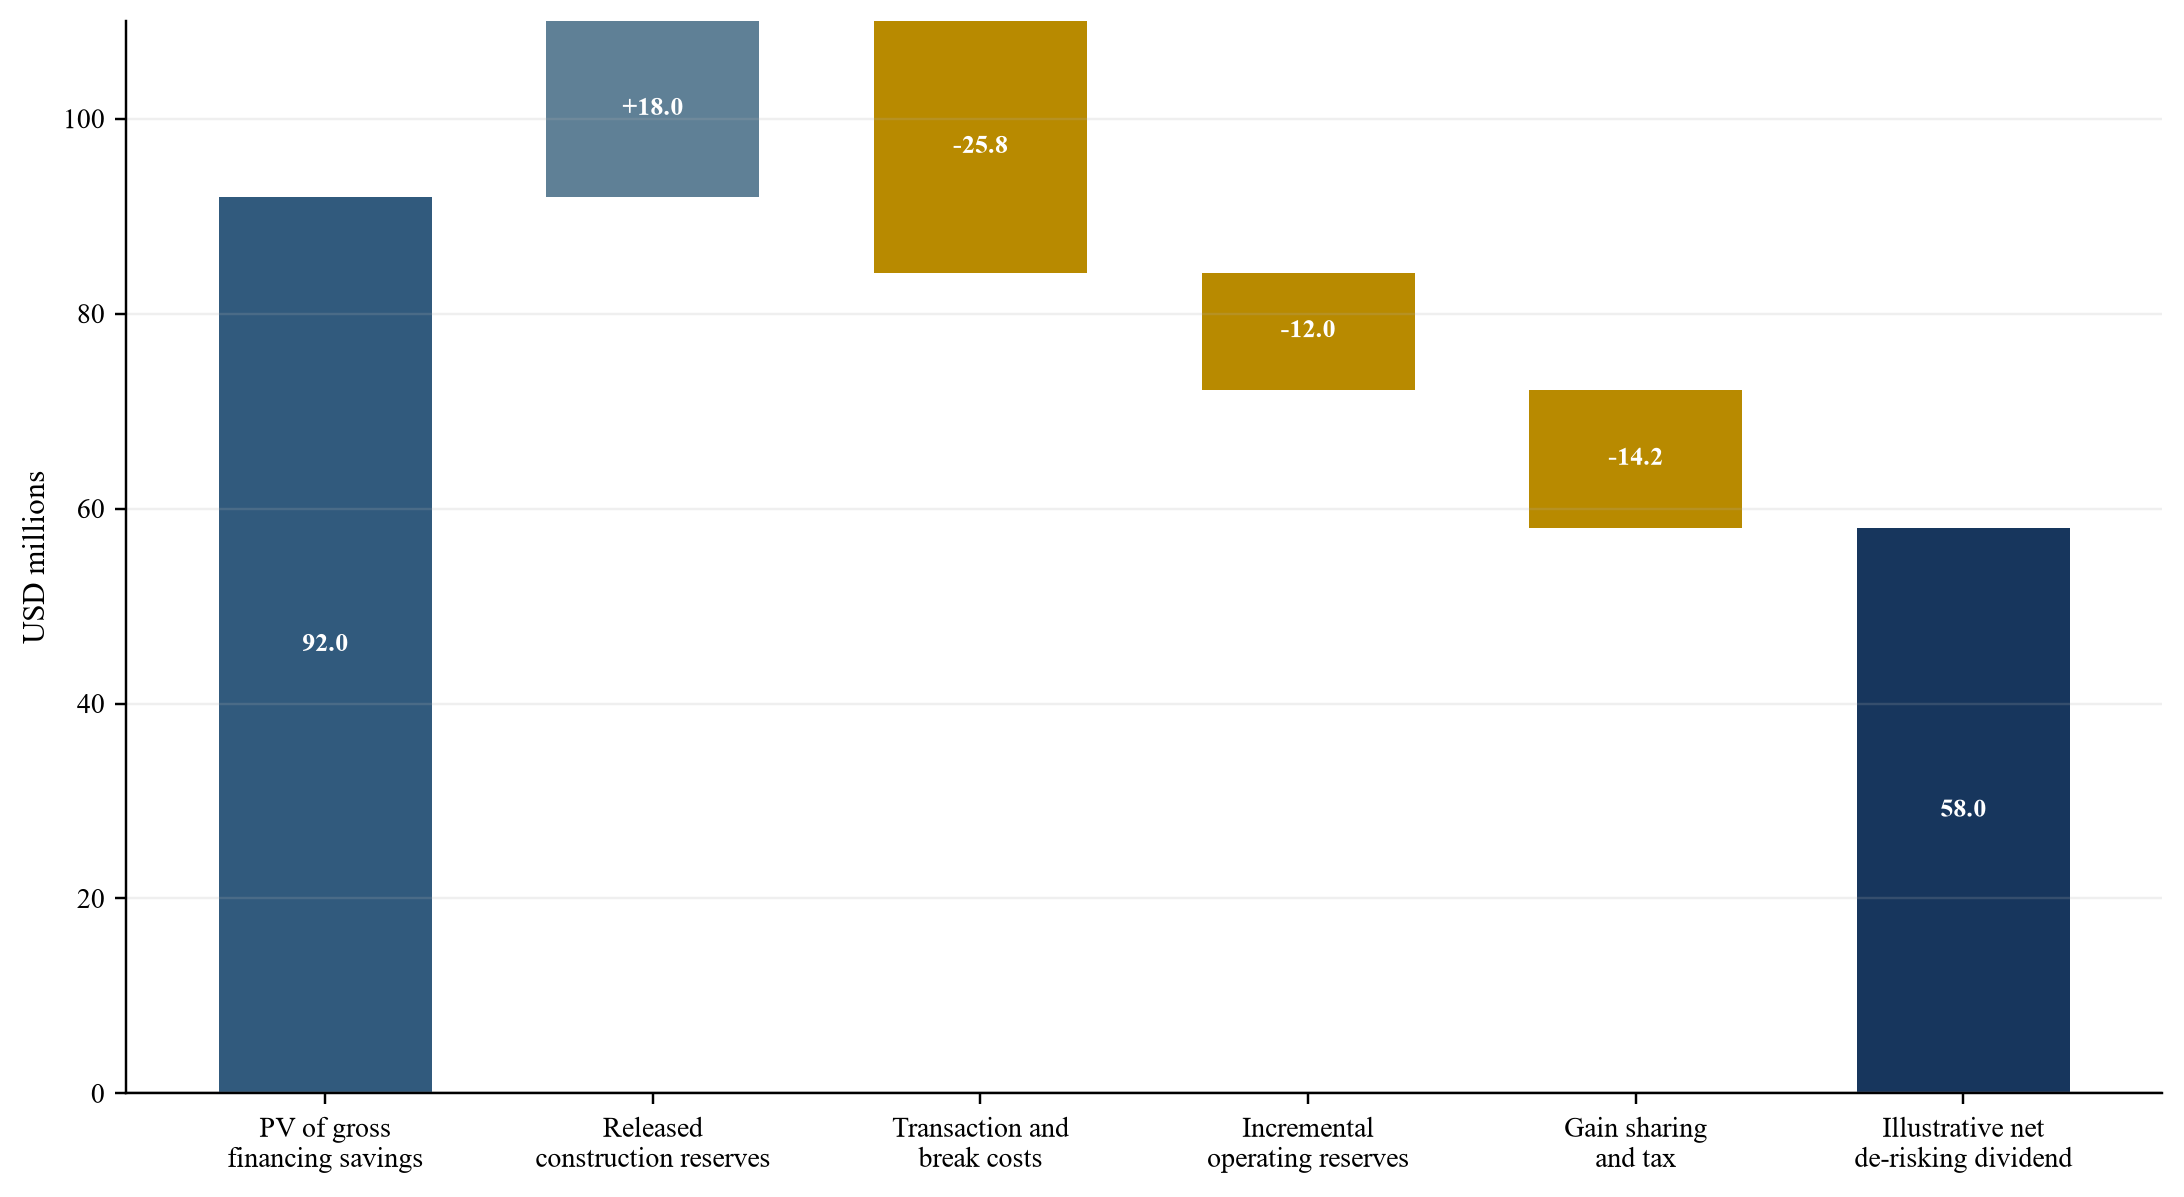
All values are illustrative management assumptions in USD millions and do not represent observed market terms, forecasts or offers.
| Scenario | Opening operating debt | All-in rate | Minimum DSCR | Illustrative net dividend | Principal decision |
|---|---|---|---|---|---|
| Central | USD 860m | 5.40% | 1.43x | USD 58m | Proceed within approved terms |
| Ramp-up weakness | USD 860m | 5.40% | 1.24x | USD 36m | Reduce debt or defer until evidence improves |
| Operating shock | USD 825m | 5.40% | 1.18x | USD 21m | Increase reserve and tighten distribution controls |
| Market delay | USD 860m | 6.15% | 1.31x | USD 19m | Compare execution with bank extension |
All values are illustrative management assumptions; coverage and value outcomes require transaction-specific modelling and independent review.
22. Link retained risks to controls
The risk heat map should show what survives after completion. Relevant exposures can include performance degradation, demand, tariff, counterparty, operating cost, lifecycle expenditure, currency, benchmark rates, regulation, force majeure and refinancing at maturity.
Each risk should have a probability range, cash-flow consequence, contractual allocation, reserve or covenant control, monitoring indicator and escalation owner. The map should use the post-refinancing structure, because a risk that was absorbed by sponsor support during construction may sit with creditors or the project after support is released.
The committee should examine correlated risks. A technical event can reduce output, increase cost, trigger contractual deductions and delay an insurance recovery. A counterparty event can combine cash-flow loss with legal cost and refinancing difficulty.
| Retained risk | Evidence indicator | Primary control | Escalation trigger |
|---|---|---|---|
| Performance degradation | Availability, output, heat rate or loss factor against tested baseline | Warranty, maintenance plan and performance reserve | Sustained variance outside approved band |
| Revenue underperformance | Billing, collections, deductions, demand and tariff application | Cash sweep, lock-up and liquidity reserve | Forecast minimum DSCR below warning threshold |
| Counterparty weakening | Payment delay, rating, financial statements and disputes | Security, replacement rights and concentration limit | Credit deterioration or repeated late payment |
| Lifecycle expenditure | Asset condition, maintenance backlog and forecast replacement cost | Funded reserve and independent engineering review | Deferred work or reserve shortfall |
| Refinancing exposure | Debt tail, maturity balance, market access and cash accumulation | Amortisation, cash retention and early market plan | Access weakens inside approved lead time |
The map is a decision template; probability and consequence require project-specific evidence.
23. Govern documentation and disclosure
The documentation workstream should cover issuer authority, offering document, trust deed or indenture, security, agency, accounts, intercreditor terms, hedging, listing and settlement.
The verification process should trace material statements to evidence and record responsibility. Forward-looking information should be clearly identified and supported by documented assumptions.
Risk factors should be specific. Generic language can obscure the issues that determine debt service. The document should explain retained construction risk, operating record, counterparty dependence, regulatory framework, maintenance, climate exposure and refinancing structure.
Counsel should confirm securities, listing, marketing, tax, sanctions, anti-money-laundering and data requirements in each relevant jurisdiction. The paper does not replace transaction-specific legal advice.
24. Control execution timing and market risk
The project plan should run backward from the required refinancing date. Critical tasks include data-room readiness, model audit, technical diligence, rating, consents, documentation, investor education, roadshow, pricing, settlement and security perfection.
Market execution requires named decision rights. The board should approve a range for size, tenor, pricing, covenants and allocations. A smaller pricing committee can act within those limits and escalate deviations.
The issuer should define launch, pause and withdrawal conditions. These can include rating outcome, spread level, order-book quality, investor concentration, consent status and material operating events.
A failed launch is expensive and visible. Dual-track alternatives, adequate liquidity and early preparation protect negotiating leverage.
25. Design the payment waterfall
The payment waterfall converts contracts and covenants into cash control. It should define the order for revenue accounts, operating cost, tax, senior debt service, reserve replenishment, maintenance, subordinated obligations and distributions.
The waterfall must align with bank accounts, account-control agreements, trustee powers and operating needs. It should also address insurance, compensation, asset-sale proceeds and termination payments.
The committee should model waterfall performance in downside cases. A nominal reserve can fail if higher-ranking uses absorb cash before replenishment.
Reporting should reconcile actual bank movements to the waterfall. Unexplained transfers or recurring manual adjustments are control warnings.
26. Plan closing and first-day operations
Closing is a transition between two control systems. The issuer should prepare a detailed funds flow, payoff letters, security-release and perfection steps, hedge termination or novation, reserve funding, fee payment and settlement instructions.
The first-day plan should confirm account mandates, trustee and agent contacts, reporting calendar, covenant calculations, investor communications, tax processes and document custody. Operational responsibility should be assigned before settlement.
Business continuity should cover failed settlement, delayed security release, payment-system outage and incorrect funds movement. A tabletop exercise can expose dependencies.
The board should receive a closing certificate confirming conditions, exceptions, final economics, ratings, allocations and retained risks.
27. Monitor the operating financing
Post-close governance should track operating performance, cash flow, coverage, reserves, maintenance, counterparties, covenants, ratings, investor reporting and market signals.
Surveillance should compare actual outcomes with the refinancing thesis. The finance committee should understand whether improved economics arise from operations, structure or market movement.
Investor reporting should be timely, consistent and evidence-based. Material events should follow the notice and disclosure requirements in the documents and applicable law.
The project company should maintain a maturity and optional-redemption plan. Early preparation preserves alternatives if the asset, market or strategy changes.
28. Implement through a 180-day programme
Days 0-30 define the financing objective, risk-release ledger, evidence standard, alternatives and governance. Days 31-60 close completion and operating-data gaps, reconstruct the construction capital stack and appoint advisers. Days 61-100 complete the operating model, route comparison, technical review, rating or lender cases and authority engagement.
Days 101-140 finalise term sheets, documents, reserves, covenants, hedging and execution parameters. Days 141-170 secure final feedback, update downside cases, confirm consents and obtain final approvals. Days 171-180 execute, settle, release construction support and transfer controls to operating surveillance.
Each stage should have exit criteria. The transaction should pause if completion evidence, operating stability, consent, financing certainty or net value moves outside approved limits. Market readiness can accelerate a launch only after the relevant evidence and authority exist.
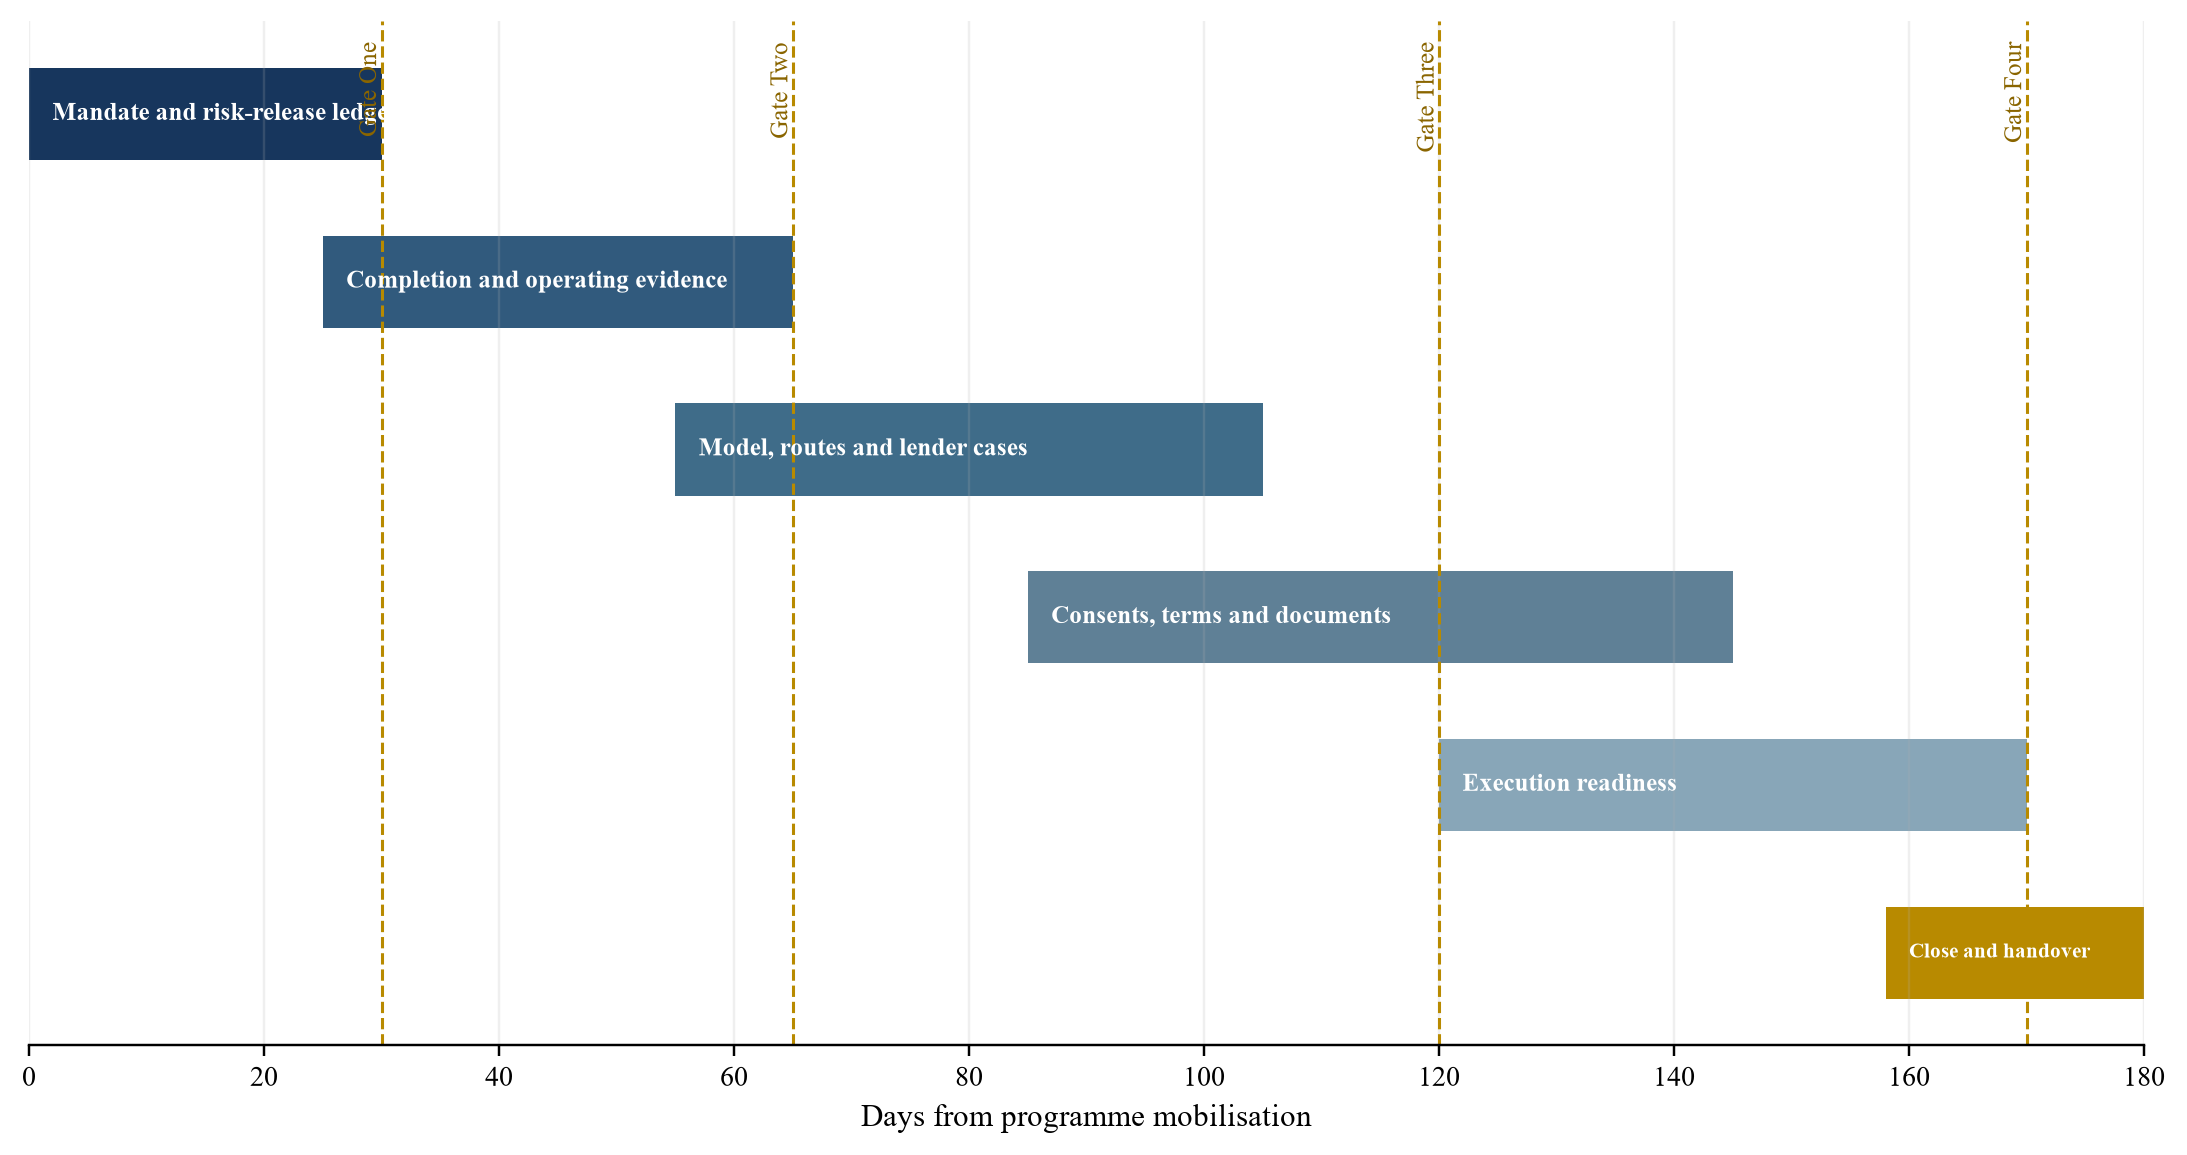
The sequencing is illustrative and should be adapted to the asset, contracts, jurisdiction, financing route and market conditions.
| Decision question | Required evidence | Decision owner |
|---|---|---|
| Has construction risk closed to the required standard? | Certificates, tests, claims, defects and independent technical conclusion | Board |
| Is the operating record stable and reconciled? | Historical KPIs, collections, accounts, CFADS and maintenance record | Investment committee |
| Does the proposed term reset create net value? | Route comparison, all-in economics, downside, covenants and reserves | Financing committee |
| Is value extracted within resilient limits? | Liquidity, leverage, gain sharing, consents and lifecycle plan | Board |
| Can the project execute and monitor the new structure? | Timetable, authorities, controls, reporting and contingency plan | Board and management |
The checklist supports an auditable decision; transaction-specific advice and approvals remain necessary.
29. Govern model risk and independent review
The refinancing model links operating evidence to debt capacity, pricing and shareholder value. Small errors in indexation, tax, reserve mechanics, sculpting or hedge treatment can change the apparent outcome. Model governance should therefore be independent of the commercial preference for a transaction.
The issuer should maintain a controlled master model with version history, input ownership, change logs and protected calculations. Historical data should reconcile to source systems. Contractual formulas should be mapped to the relevant provisions and reviewed by counsel or the appropriate specialist where interpretation affects cash flow.
An independent model audit should test logic, formula integrity, circularity, scenario controls, financial statements, taxes, debt schedules, reserves, covenants and outputs. The audit scope and materiality thresholds should be agreed before work begins. Open points should remain visible to the financing committee until resolved.
The board paper should report sensitivity rather than a single net-present-value result. It should identify the assumptions that drive route choice, rating headroom and distribution capacity. A model can support judgement only when its limitations and data boundaries are understood.
30. Align tax, accounting and distributable reserves
Refinancing can affect withholding tax, deductibility, transfer pricing, deferred tax, hedge accounting, transaction-cost amortisation and distributable reserves. These effects should be analysed in the issuer, project company, holding companies and investor structure.
The tax workstream should distinguish legal obligation from model assumption. It should address interest limitation, treaty access, beneficial ownership, permanent establishment, value-added tax on fees and taxes on security enforcement or asset transfers. Current advice is required in every relevant jurisdiction.
Accounting analysis should determine classification of the new debt, treatment of extinguishment or modification, embedded derivatives, transaction fees, reserves and covenant disclosures. The result can affect reported earnings and ratios without changing underlying cash flow. The decision paper should show both accounting and cash effects.
Distribution planning should confirm that cash permitted by the financing documents can lawfully be distributed. A refinancing that creates accounting profit or excess cash does not by itself establish distributable reserves or board authority.
31. Procure advisers through defined responsibilities
The transaction can involve financial advisers, arrangers, underwriters, rating agencies, legal counsel, technical advisers, model auditors, tax advisers, external reviewers, trustees, agents and listing venues. The issuer should define each mandate, deliverable, dependency and conflict.
Adviser fees should be compared on a common basis. Retainers, success fees, underwriting discounts, expense caps, discretionary fees and recurring agency costs should be visible. Fee incentives should not determine route selection or launch timing.
The issuer should identify which advisers owe duties to it, which act for investors or lenders and which provide independent opinions. Work-product reliance, confidentiality, liability caps and termination rights should be reviewed before appointment.
A single integrated timetable should assign every deliverable to an accountable owner. The project-management office should track overdue items, decision dependencies and changes to scope. Advisers should inform governance; management and the board retain the transaction decision.
32. Protect future capital expenditure and asset renewal
Long-lived infrastructure requires maintenance, lifecycle replacement, expansion and regulatory investment. The bond structure should leave adequate capacity for these needs rather than maximising initial distributions.
The asset-management plan should classify routine operating cost, major maintenance, lifecycle capital expenditure and expansion. It should identify timing, cost basis, contingency, procurement strategy and funding source. Technical-adviser review can test whether the plan is consistent with asset condition and contractual performance standards.
Reserve and covenant design should support necessary expenditure. A distribution lock-up should not prevent spending required to preserve safety, availability or concession compliance. Additional-debt provisions should distinguish value-preserving capital from speculative expansion.
Fitch's criteria examine infrastructure renewal and obsolescence alongside operations, revenue and debt structure [3]. The refinancing model should therefore cover the full period over which debt relies on asset performance, including replacement cycles that fall after the initial operating record.
33. Build a transaction decision record
The final decision record should allow a later reviewer to understand what the board approved, why it approved it, what evidence it relied upon and which risks remained. It should include the alternatives, evaluation criteria, model versions, adviser reports, ratings, consents, investor feedback and final terms.
The record should distinguish observed information, contractual facts, external opinions and management assumptions. It should document material changes between initial approval, launch and closing. Pricing improvements should not obscure covenant, security or allocation changes introduced during execution.
Exceptions should identify owner, rationale, duration and remediation. A condition waived for timing reasons should become a post-close action with a reporting deadline. Repeated waivers can indicate that the original readiness standard was unrealistic or poorly enforced.
An annual refinancing review should compare the original thesis with realised costs, operating performance, rating movement, covenant headroom, investor engagement and governance burden. Lessons should feed into the next financing decision and the organisation's infrastructure-capital playbook.
34. Prepare for a failed or deferred transaction
A refinancing programme should have a defined response if the bond cannot launch, prices outside the approved range, receives a weaker rating, or fails to settle. The project company should know how long existing liquidity lasts, which bank facilities remain available and which contractual deadlines create pressure.
The contingency plan should include an amend-and-extend proposal, private-placement alternative, bridge facility, sponsor support parameters and cost-control actions. Each alternative should have a lead time, approval path, conditions and maximum acceptable economics. An assumed rescue facility has no value until capacity, terms and authority are evidenced.
Communications require control. Investors, banks, public authorities, contractors, employees and rating agencies may receive different information under different duties. The issuer should prepare accurate, coordinated messages that preserve confidentiality and comply with applicable disclosure requirements.
Deferral should trigger a structured review of the cause. Market volatility, incomplete evidence, consent delay, rating weakness and unacceptable terms require different remedies. The committee should set the evidence and market conditions required to restart, together with an expiry date for stale diligence.
Failure planning strengthens execution discipline. It gives the pricing committee authority to withdraw from a poor transaction without creating an immediate funding crisis. It also protects the project from accepting leverage, covenants or investor concentration that weaken long-term resilience merely to declare the refinancing complete.
35. Convert risk release into a durable financing outcome
The final financing case should allow a new lender or investor to trace the credit from physical completion to operating cash flow. It should identify the secured group, asset perimeter, material contracts, revenue rights, operating obligations, bank accounts, reserves, hedges, security and permitted transfers. Legal descriptions and financial models should use the same perimeter.
The operating evidence should show monthly performance and cash conversion at a level appropriate to the asset. Availability, output, demand, tariff, collections, operating cost, maintenance, working capital and reserve movements should reconcile to accounts and identified source records. Exceptions should be explained through cause, duration, value effect and remediation.
The risk-release ledger should accompany the credit case. Each material construction exposure should be classified as closed, migrated or retained. The financing consequence should be explicit. This record supports negotiations on pricing, covenants, reserves and release of sponsor support while preserving a defensible explanation for the board and any public authority.
The model should show how value changes across the full financing package. It should compare the status quo and each refinancing route under common assumptions, then bridge the gross financing benefit to costs, reserve changes, guarantee releases, gain sharing, tax and distributions. The dividend should be reported as a range where pricing or operating performance remains uncertain.
The downside case should test stresses that can occur together. A performance event may coincide with higher costs, delayed insurance recovery, weaker collections and a market closure. The model should show reserve draws, lock-up, cure, minimum liquidity and any reliance on sponsor or public support. Capacity or authority for that support must be evidenced before it is treated as available.
The executed transaction should be compared with the final approved case. The closing report should show principal, pricing, tenor, amortisation, fees, hedging, reserves, covenants, lender or investor concentration, support released, consents and continuing obligations. Any deviation should identify its value effect and approval.
Post-close surveillance should preserve the dividend. Operating performance, lifecycle expenditure, coverage, liquidity, counterparty quality, covenants and refinancing exposure should be monitored against the approved case. The project should retain the evidence needed to explain future changes in credit quality and to prepare for later refinancing without reconstructing the record.
The financing committee should review realised value after twelve and twenty-four months. The review should compare actual interest, fees, distributions, reserve use, operating outcomes and governance cost with the approved model. This closes the accountability loop and improves the next capital decision.
Sources
- World Bank Group, Public-Private Partnerships Reference Guide, Construction Lending versus Long-Term Lending and Refinancing Risk. Read the primary source
- S&P Global Ratings, Project Finance Infrastructure, construction-phase and operations-phase credit analysis. Read the primary source
- Fitch Ratings, Infrastructure and Project Finance Rating Criteria, 14 November 2025. Read the primary source
- World Bank PPP Resource Center, Risk Allocation, Completion and Performance. Read the primary source
- Moody's Ratings, Infrastructure and Project Finance Methodology, 2025. Read the primary source
- S&P Global Ratings, Project Finance Assessment Template for Assigning Project Finance Issue Ratings. Read the primary source
- World Bank Group, Understanding Power Project Financing, Refinancing Post-Completion. Read the primary source
- World Bank Group, Guidance on PPP Contractual Provisions, 2019 edition. Read the primary source
- Global Infrastructure Hub, PPP Contract Management, Refinancing Guidance. Read the primary source
- World Bank PPP Resource Center, Considerations for Government Public-Private Partnerships. Read the primary source
- International Capital Market Association, Infrastructure Financing Guide. Read the primary source
- Asian Securities Industry and Financial Markets Association and ICMA, Guide to Infrastructure Financing in Asia. Read the primary source
- European Investment Bank, Credit Enhancement for Project Finance. Read the primary source
- World Bank, Promoting the Use of Capital Markets for Infrastructure Financing. Read the primary source
- World Bank, Addressing Exchange Rate Risk in Infrastructure Projects in Emerging Markets and Developing Economies, 2024. Read the primary source
- International Capital Market Association, Green Bond Principles, 2025. Read the primary source
- World Bank PPP Resource Center, Intercreditor Arrangements and Sponsor Support. Read the primary source
- European Investment Bank, An Outline Guide to Project Bonds Credit Enhancement and the Project Bond Initiative. Read the primary source
