
1. Define the asset being acquired
A data-centre acquisition can involve shares in an operating company, property companies, a development platform, individual sites, customer contracts, utility rights, equipment, intellectual property, employees and operating licences. These elements can sit in different legal entities and jurisdictions. The first diligence task is therefore to define the transaction perimeter and trace each source of value to the entity and contract that controls it.
The perimeter should distinguish owned land, leased land, subleases, easements, buildings, substations, generation assets, network routes, cooling and water assets, customer agreements, licences, software, operating data and development rights. It should also identify joint ventures, minority interests, related-party arrangements and services supplied by the seller after closing. A capacity claim held by an excluded affiliate should not enter the buyer's valuation without a binding transfer or replacement arrangement.
The operating model matters. Retail colocation, wholesale capacity, hyperscale build-to-suit, enterprise hosting and sovereign cloud can use similar physical infrastructure while producing different contract terms, fit-out obligations, concentration, margins and renewal risk. A buyer should segment revenue and capacity by service rather than applying one portfolio multiple.
The deal team should create one transaction data model. Legal entities, sites, megawatts, customers, contracts, assets, capital expenditure and valuation lines need stable identifiers. This allows legal, technical, commercial and financial findings to reconcile. It also limits the risk that several workstreams count the same future capacity or overlook the same condition.
Property diligence should follow the same perimeter logic. The buyer should review title or lease term, permitted use, renewal, rent review, access, easements, utility corridors, mortgage or assignment restrictions, reinstatement, environmental liability and rights over substations, generators and rooftop equipment. Expansion land can support value only when the operating entity can use it for the intended duration and the required access and infrastructure rights survive closing. A long customer contract against a short or conditional property term creates a duration mismatch that should be resolved in the documents and model.
Shared services require a separation test. Network operations, security monitoring, procurement, billing, customer support, software licences, insurance and utility contracting can be provided centrally by the seller. The buyer should identify the people, systems, contracts, data and licences required to operate independently. A transition-services agreement should specify scope, service levels, cost, data access, cyber controls, termination assistance and the target operating model. The separation cost belongs in the purchase-price and integration bridge.
2. Build the capacity ledger before accepting headline megawatts
Capacity should be recorded as a sequence of evidence states. Requested capacity represents an application. Reserved capacity may depend on milestones, deposits and network work. Contracted capacity reflects an executed agreement but can remain subject to conditions. Energised capacity is available at the connection point. Commissioned capacity has passed required tests. IT load deducts facility use and technical constraints. Customer-committed capacity reflects enforceable contracts. Revenue-producing capacity has met acceptance, billing and collection rules.
The ledger should show gross and net measures. Utility supply, backup generation, uninterruptible power supply, cooling, power-usage effectiveness and redundancy determine the IT load that can be sold. A site marketed at 100 megawatts of utility supply may support a different billable IT load depending on design and operating conditions. The ledger should identify the measurement basis for every number.
Timing is part of capacity. Each row requires the current state, next milestone, responsible party, evidence, required spend, earliest credible date and downside date. European connection regimes increasingly distinguish a position in a historical queue from a project that is ready and needed. Great Britain's National Energy System Operator states that the former connections queue exceeded 700 gigawatts and could imply waits of up to ten years; its reformed process uses readiness and strategic-alignment gates.[11][12][13] Ireland's regulator requires qualifying new data centres to address location, dispatchable generation or storage and additional renewable electricity.[14][15] The acquisition model should therefore capture the applicable regime, readiness evidence, dependencies, milestones and downside date for each capacity block.
The ledger should reconcile three reporting systems. Engineering records describe physical and commissioned capacity. Commercial records describe reserved, contracted and billable capacity. Finance records describe recognised revenue, invoices and collections. Differences should remain visible. A hall can be technically commissioned while customer acceptance is pending; a contract can reserve capacity that is not ready; an invoice can include power and services unrelated to one hall. The buyer should establish rules for allocating each contract and cash flow to the relevant site, phase and capacity block.
Portfolio totals should avoid aggregation traps. Capacity at different redundancy standards, voltages, cooling designs and readiness states cannot always be substituted. The buyer should tag the technical and contractual characteristics of each block before presenting a group total. A sale process that reports all future phases as one buildable number can create false comparability with an operator reporting only installed IT load. Comparable-company and precedent-transaction analysis should therefore use aligned definitions or disclose the remaining difference.
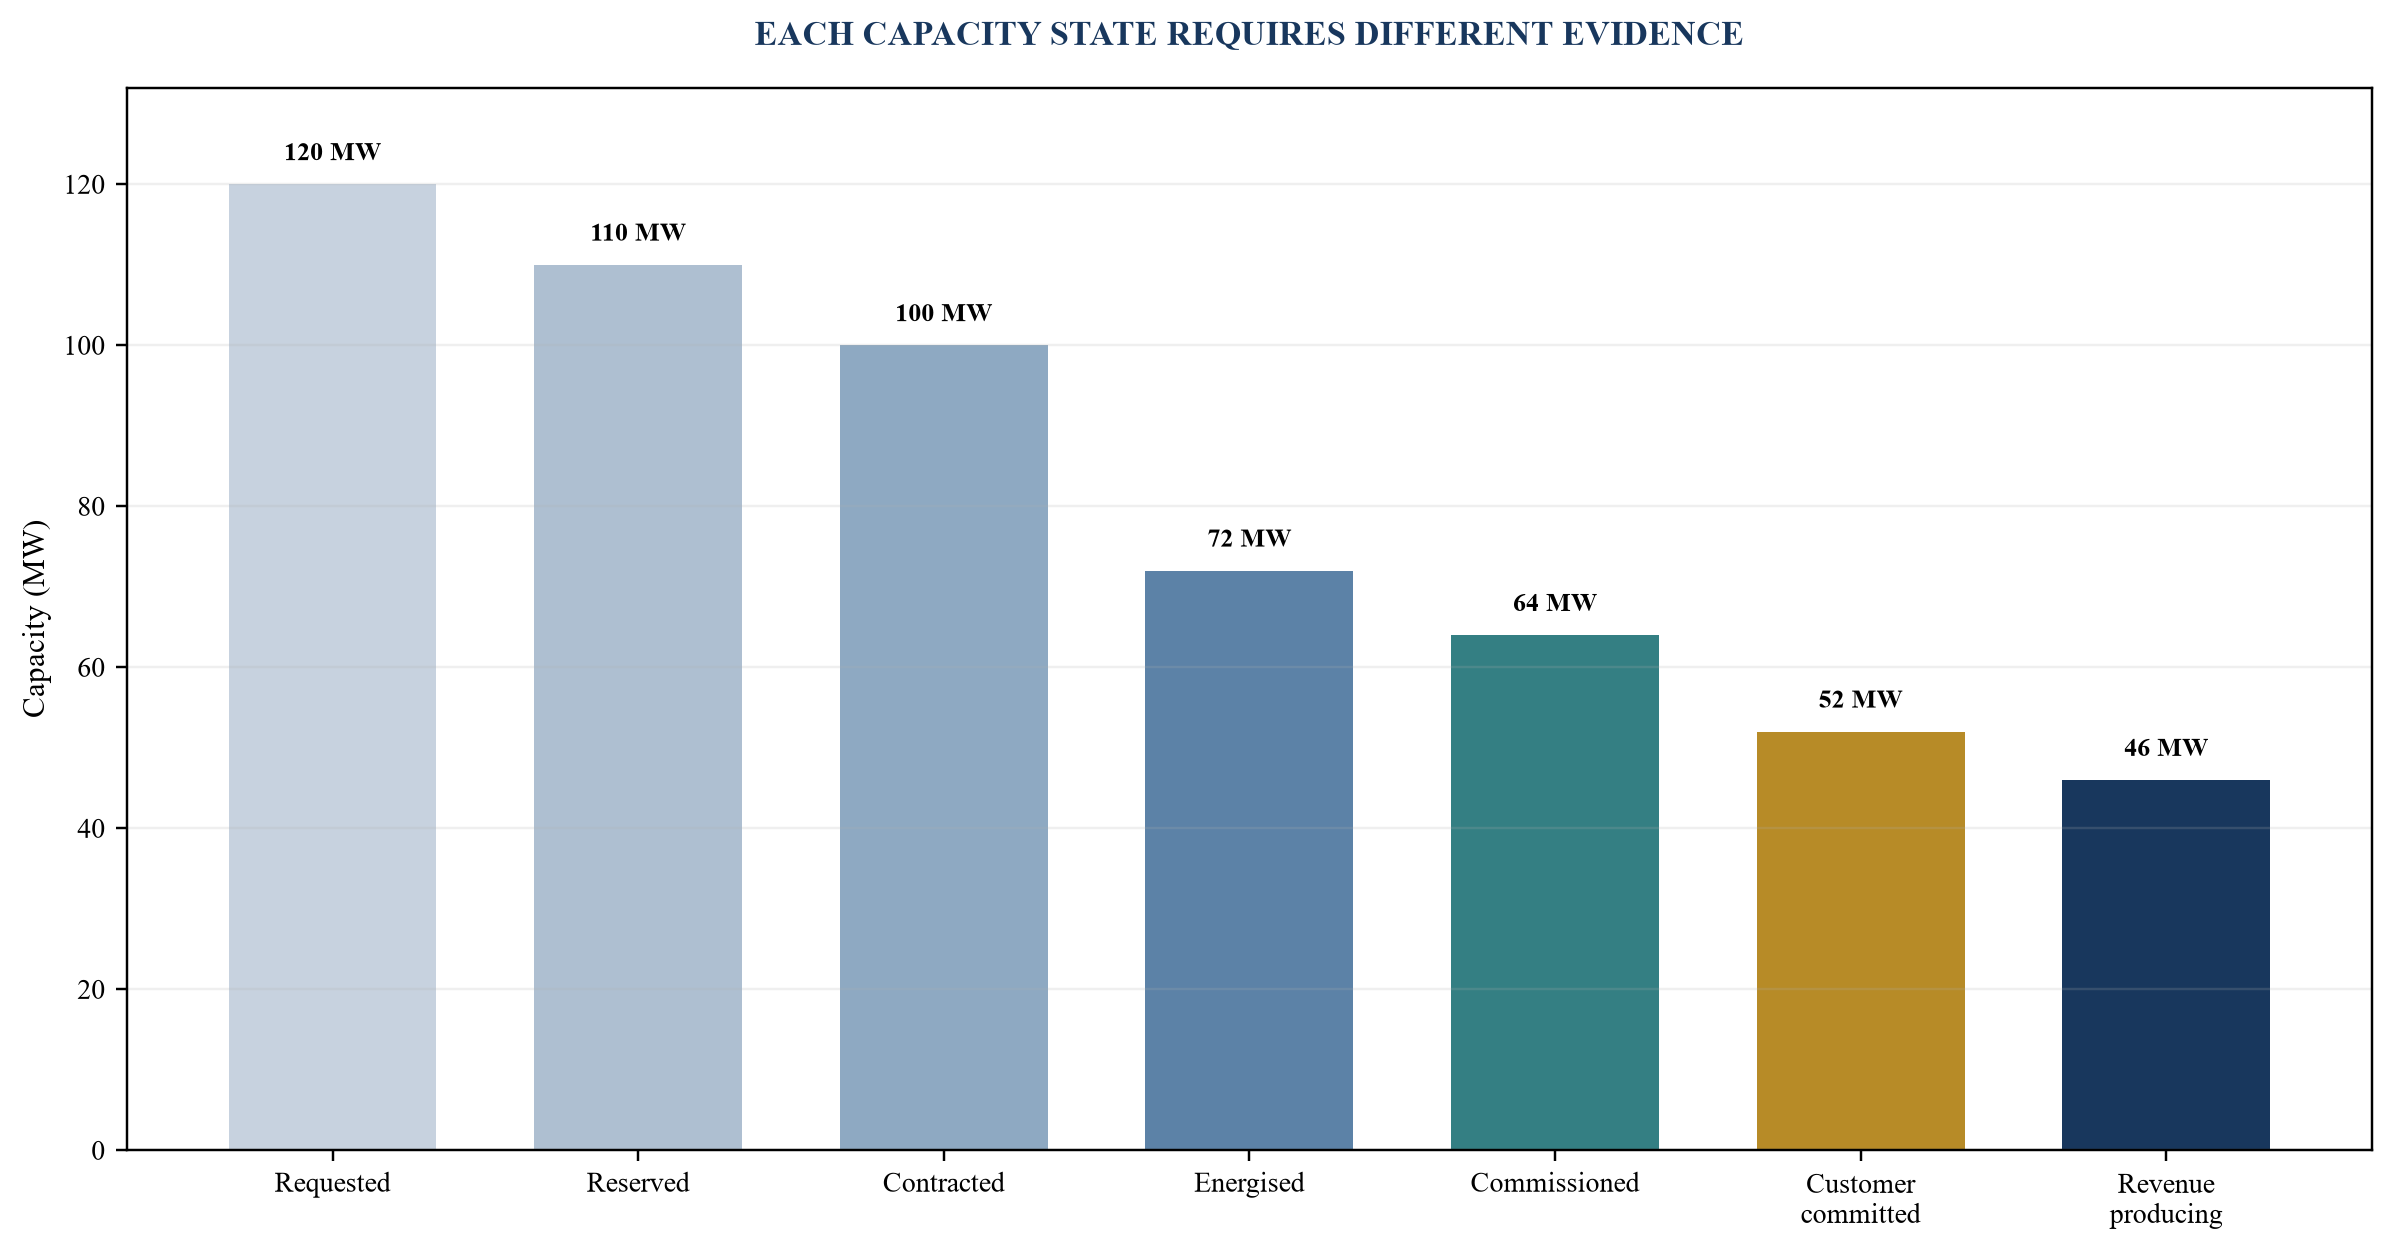
The evidence state narrows the capacity that can support purchase price; values are hypothetical.
| Field | Required evidence | Principal risk | Deal treatment |
|---|---|---|---|
| site and phase | title, lease, plan and entity map | capacity outside perimeter | transfer condition or exclusion |
| utility state | application, offer, agreement and invoice | headline exceeds enforceable right | probability weighting |
| delivery path | network study, works, permits and schedule | grid or substation delay | seller obligation or holdback |
| technical state | design, tests, commissioning and incidents | supply cannot support billable IT load | capex and availability adjustment |
| customer state | executed order, acceptance and billing | reserved capacity lacks durable revenue | contract-specific value |
| expansion state | land, power, design, equipment and capital | option presented as committed growth | stage-gated value |
Each row should link capacity, rights, technical state, customer use and value.
3. Map power rights as a chain of obligations
Power is a bundle of rights, obligations, assets and dependencies. The map begins with the applicant and utility, then traces the connection point, network reinforcement, substation, transformers, cables, protection, metering, backup, generation, storage and internal distribution. It records ownership, funding, construction, testing, operation and maintenance for each component.
The legal review should test whether the agreement is binding, transferable and durable through a change of control. It should identify long-stop dates, milestone obligations, deposits, security, termination, reduction, suspension, curtailment, force majeure, liability and dispute provisions. A buyer also needs the tariff basis, demand charges, escalation, taxes, connection costs and liabilities for reinforcement or relocation.
The technical review should reconcile the agreement with drawings, load studies, equipment ratings, redundancy, harmonic limits, power factor, protection settings, outage records and measured demand. Applicable European network codes, national connection rules, distribution codes and site-specific agreements establish technical and information obligations at connection points. The review should identify whether the stated capacity is firm, interruptible, conditional or staged and whether power-quality responsibility sits with the system operator, distribution operator, customer or shared equipment owner.
The commercial model should then translate the right into capacity, cost and timing. A low tariff with delayed energisation may have less value than available power at a higher price. A firm connection and a curtailable block should be modelled separately. Renewable certificates, behind-the-meter generation and power-purchase arrangements require separate ownership, volume, tenor, basis, curtailment and transfer tests.
Deposits and reinforcement payments need accounting and recovery analysis. A utility payment can be refundable, offset against future charges, non-refundable or forfeitable after a missed milestone. The buyer should reconcile payment evidence, balance-sheet classification, contractual status and forecast treatment. If the seller has capitalised costs that do not transfer or cannot support future service, they should not enter the acquired asset base without an explicit rationale.
Power quality and resilience also affect value. The review should capture historical interruptions, voltage events, protection trips, maintenance outages, generator tests, fuel arrangements, battery condition and single points of failure. Contractual redundancy labels should be tested against actual topology and operating procedures. The resulting service risk connects directly to tenant credits, renewal, insurance, capital expenditure and valuation.
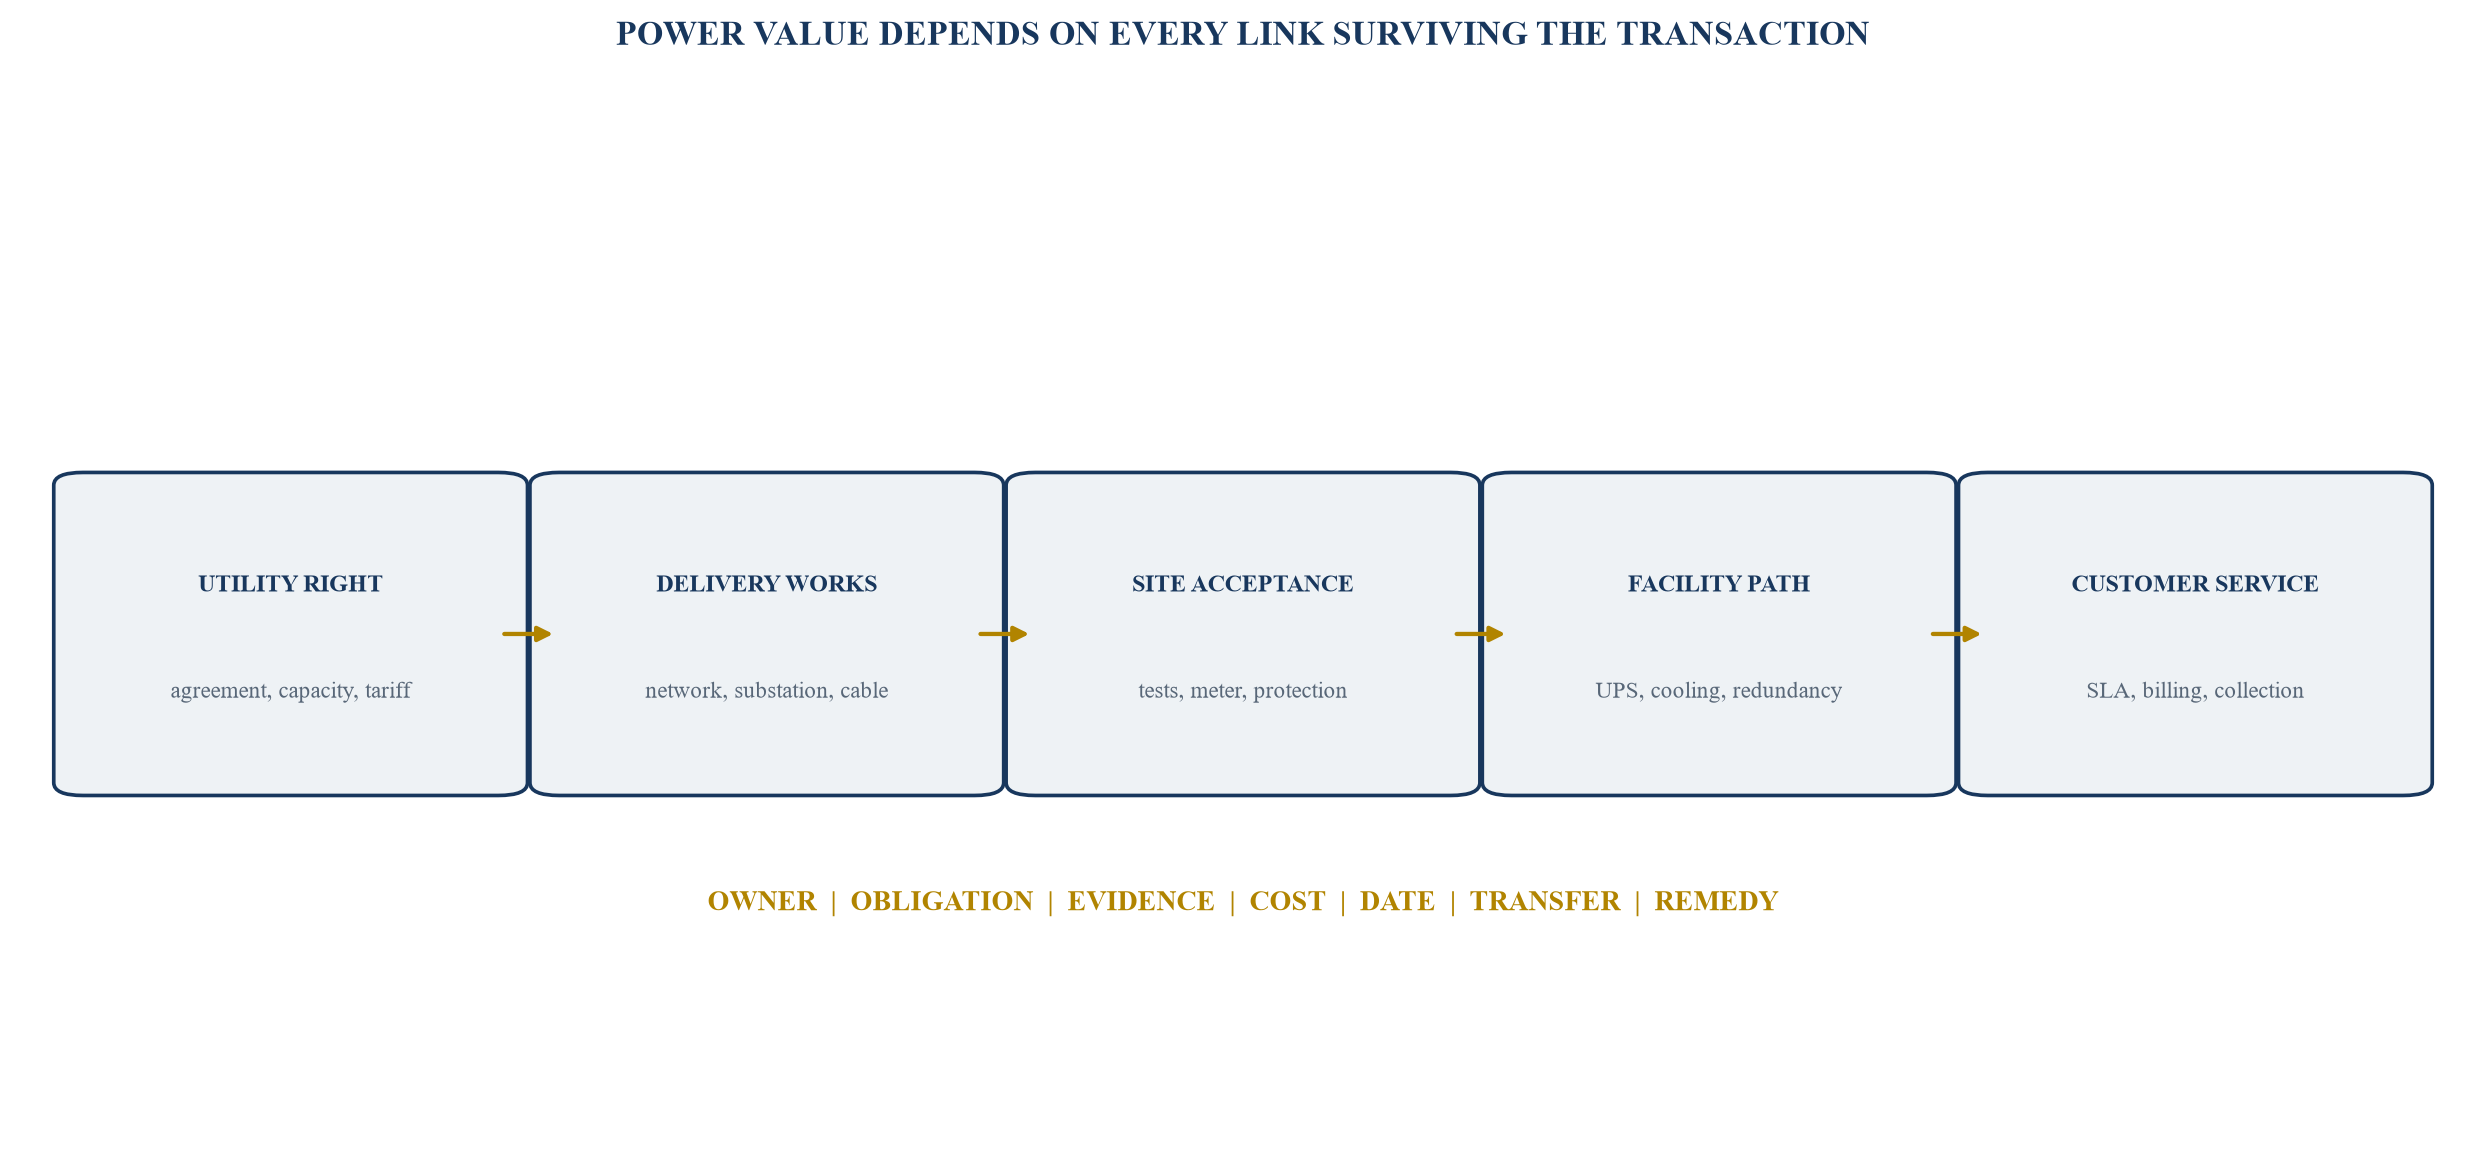
Value requires an enforceable and funded path from utility commitment to customer service.
4. Reconstruct the European grid queue and connection path
A queue position is an administrative and contractual state rather than physical capacity. The buyer should reconstruct the chronology from application through studies, offer, acceptance, security, land rights, planning, network reinforcement, equipment procurement, commissioning and energisation. Each step should identify the responsible party, documentary evidence, expiry, dependency, cost, earliest date, downside date and remedy. The schedule should distinguish target-controlled actions from utility, system-operator, generator, landowner and permitting dependencies.
Queue reform can change the meaning and order of a legacy position. Great Britain's National Energy System Operator describes a move from a first-come approach to readiness and strategic alignment, with Gate 1 and Gate 2 outcomes. A buyer should obtain the submitted evidence, operator correspondence, land and planning status, milestone notices and any appeal or modification record. Ireland's connection policy introduces location and system-support considerations for data centres. Other European markets use different transmission, distribution, capacity-allocation and permitting arrangements. A portfolio-wide label cannot replace country and connection-point analysis.
Connection dates should be expressed as conditional paths. A date in an offer can depend on upstream reinforcement, substation completion, protection studies, equipment lead times, planning, land access, third-party works and customer milestones. The model should contain an evidence-weighted central date and at least one downside date. A transaction long-stop should align with the dependencies that determine commercial operation, rather than with an unsupported management target.
Power quality is part of deliverable capacity. The technical workstream should examine voltage limits, frequency, harmonics, flicker, fault level, protection coordination, restoration, planned outages, historical interruptions and the quality of internal distribution. Sensitive computing equipment may require additional conditioning and redundancy even where the utility connection meets its formal standard. The cost and space for that equipment should enter the acquisition plan.
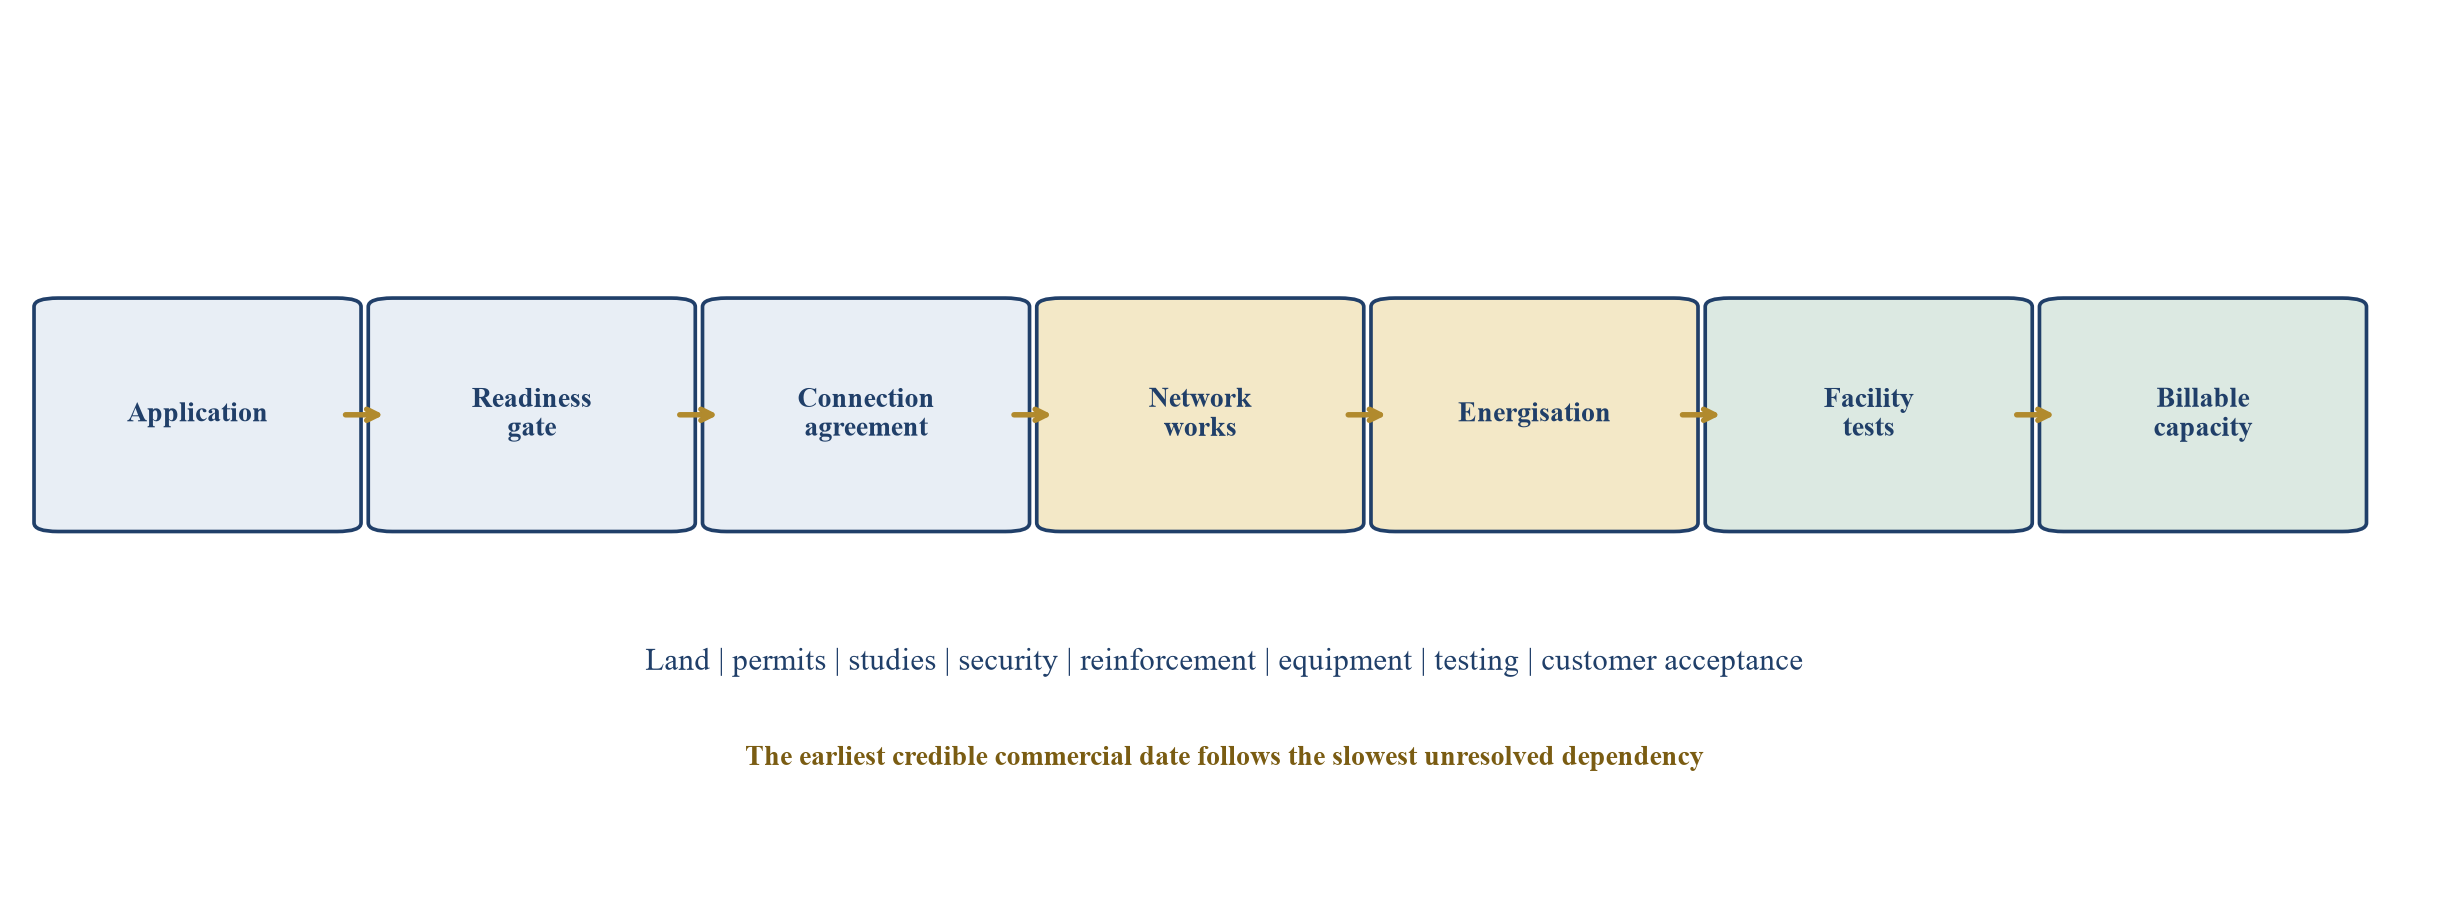
Proposed transaction control map. Each gate requires evidence, a responsible party, a credible date and a stated valuation treatment.
| Evidence | Diligence question | Model effect | Transaction response |
|---|---|---|---|
| application and operator acknowledgement | which entity applied for what capacity and at which point? | defines claimed scope | transfer, novation or exclusion |
| readiness submission and gate outcome | does the project meet current land, planning and strategic tests? | changes probability and order | condition precedent or price weighting |
| connection agreement and modifications | which capacity, dates, milestones and remedies are binding? | sets central and downside dates | covenant, long-stop and seller obligation |
| reinforcement and third-party works | what upstream work controls energisation? | adds delay and capital exposure | holdback, completion account or contingency |
| deposits and security | what is paid, refundable, forfeitable or replaceable? | affects cash and completion funding | closing adjustment and replacement security |
| commissioning and operating record | what capacity is physically available and at what quality? | supports usable IT load | technical acceptance and warranty |
Requirements vary by jurisdiction and connection point; current local legal and technical advice is required.
| Scenario | Connection assumption | Operating constraint | Valuation treatment | Protection |
|---|---|---|---|---|
| evidenced central | binding date with funded works and satisfied milestones | agreed planned outages | contracted capacity in base case | ordinary warranties and reporting |
| delayed energisation | upstream works or equipment moves the date | pre-revenue fixed cost continues | discount cash flow and add carrying cost | long-stop, holdback or seller completion |
| constrained operation | capacity available with curtailment or import limit | lower saleable IT load or backup cost | reduce revenue and margin | price adjustment, capex reserve or earn-out |
| power-quality remediation | connection exists but conditioning or redundancy is deficient | additional equipment and testing | deduct capex and delayed ramp | completion condition and technical warranty |
| failed or lost right | milestone, transfer or consent cannot be secured | no capacity for affected phase | exclude affected development value | termination right or carve-out |
Scenario probabilities and values must be transaction-specific; labels below provide a controlled structure rather than forecasts.
5. Test transfer, change of control and security
An acquisition can change the legal, credit and operational facts on which a utility or landlord relied. The diligence list should identify every consent, notice, novation, licence amendment, lender approval, landlord waiver and government approval triggered by the proposed structure. Silence in a data room does not establish transferability.
Share and asset deals create different paths. A share acquisition may preserve the contracting entity while triggering change-of-control provisions. An asset acquisition can require assignment or novation of each right. A pre-closing reorganisation can create tax, licensing, security and continuity risks. The conditions-precedent schedule should identify the exact document, authority, filing date, dependency and closing consequence.
Existing financing can also restrict transfer. Security may attach to shares, land, receivables, utility deposits, equipment and bank accounts. The buyer needs a release and perfection sequence that preserves operational continuity. Where a utility or landlord has step-in or termination rights, intercreditor and direct agreements should be reviewed alongside the acquisition documents.
6. Read tenant contracts as option portfolios
A tenant agreement contains a base obligation and a set of options. Renewal can extend cash flow at fixed, indexed or market rent. Expansion can reserve scarce capacity or require the operator to build. Contraction can return capacity to the operator while reducing contracted revenue. Termination can depend on delay, service failure, law, convenience, change of control or a customer milestone. Rights of first offer or refusal can restrict future leasing or a sale.
The tenant-option matrix should record exerciser, notice window, capacity, price, capex, condition, probability basis and valuation treatment. It should also record assignment, parent guarantees, security deposits, service credits, set-off, data residency, step-in, equipment ownership, decommissioning and reinstatement. Options should be modelled from the contract language rather than a management summary.
Pricing options can be as important as capacity options. Fixed escalators, market resets, most-favoured-customer provisions, benchmarking, power caps and currency terms can change cash duration. A renewal at below-market pricing can be likely and still reduce expected value. A market-reset clause can support value while creating dispute or vacancy risk. The model should separate contractual price, current invoiced price, normalised price and the price assumed after each option date.
Customer credit support should be mapped to the obligation it secures. A parent guarantee may expire, cap liability or exclude expansion. A deposit may be available for unpaid invoices while fit-out or decommissioning liabilities remain unsecured. Letters of credit can have renewal and draw conditions. The buyer should reconcile security amount, issuer, expiry, beneficiary and transfer, then reflect any gap in the tenant-risk and closing plan.
Expansion rights deserve close attention. A customer may hold future capacity without paying full reservation economics. The operator may have to procure power, cooling and equipment before the customer commits. A priority right can block alternative tenants and reduce the marketability of expansion. Conversely, a creditworthy take-or-pay expansion can support financing and development value when acceptance and termination risks are controlled.
7. Reconcile contracted revenue to collected cash
Annualised contract value is not cash available to the acquirer. The bridge should begin with contracted base charges and remove free periods, ramp, service credits, power pass-through timing, disputed invoices, set-off, tax, bad debt, related-party revenue and amounts conditional on future acceptance. It should reconcile invoices to bank receipts and customer-level deferred or accrued balances.
Power revenue and cost require particular care. Some contracts pass through actual electricity cost; others use fixed rates, indices, mark-ups, caps or periodic resets. Demand charges and minimum utility payments can remain when a customer uses less capacity. The buyer should model gross and net power economics by contract and site, including losses, cooling and facility load.
Customer concentration should be measured by revenue, cash contribution, contracted MW, expiry, parent group and technology workload. A portfolio can appear diversified by legal customer count while remaining dependent on one economic group or cloud platform. Concentration affects renewal leverage, credit exposure, fit-out specificity and re-leasing cost.
8. Verify operating service and customer acceptance
Tenant value depends on service delivery. The technical review should analyse availability, incidents, maintenance, capacity constraints, power quality, cooling performance, security events and customer claims. Service-level calculations should reconcile to credits and correspondence. A site reporting high portfolio uptime can still have material hall-level or customer-level issues.
Acceptance documents determine when construction becomes revenue. The buyer should review commissioning procedures, integrated systems tests, customer tests, punch lists, conditional acceptance and unresolved defects. A signed lease whose rent commencement depends on a future test belongs in contracted growth, not operating earnings.
Cyber and physical security findings can affect retention and integration. The buyer should identify certifications, audit reports, material exceptions, customer-specific controls, privileged access, monitoring, incident response, vendor dependencies and separation requirements. The transaction plan should preserve evidence and control during system migration.
9. Convert expansion claims into a stage-gated pipeline
Expansion capacity should be divided into land-controlled, permitted, power-supported, designed, procured, under construction, commissioned and customer-backed phases. Each phase should have objective entry and exit evidence. A land parcel beside an operating site is not equivalent to an approved and powered extension.
The pipeline should reconcile land area, buildable area, utility capacity, substation space, fibre routes, cooling and water, environmental constraints, equipment lead times, contractor resources, customer demand and capital. The slowest dependency controls the date. IEA analysis highlights the long lead times for grids, transformers and cables; a board should therefore test the delivery path rather than extrapolate recent build rates.
Expansion value should be probability-weighted by evidence state and reduced for capex, delay, financing and cannibalisation. The acquisition model should prevent double counting between existing contracted capacity, customer options and speculative pipeline. A separate opportunity case can preserve upside without embedding it in the price paid at closing.
Permitting should be decomposed rather than shown as a single green status. Planning, building, fire and life safety, environmental, water, generator, fuel, road access, aviation, telecom and operational approvals may follow different authorities and expiry dates. The buyer should identify whether permits attach to land, design, entity or contractor and whether a change of control or design change requires notice or reapproval. A permit valid for the current phase may not support the density, cooling or generator strategy assumed for expansion.
Equipment capacity should also match the design case. Transformer, switchgear, UPS, generator, chiller, pump, heat-rejection and control-system ratings should reconcile to the intended IT load and redundancy. Vendor reservations without an executed purchase order can provide limited schedule certainty. Executed orders with non-cancellable deposits can create a liability if the customer's design changes. The stage gate should therefore connect engineering freeze, customer specification, procurement commitment and financing approval.
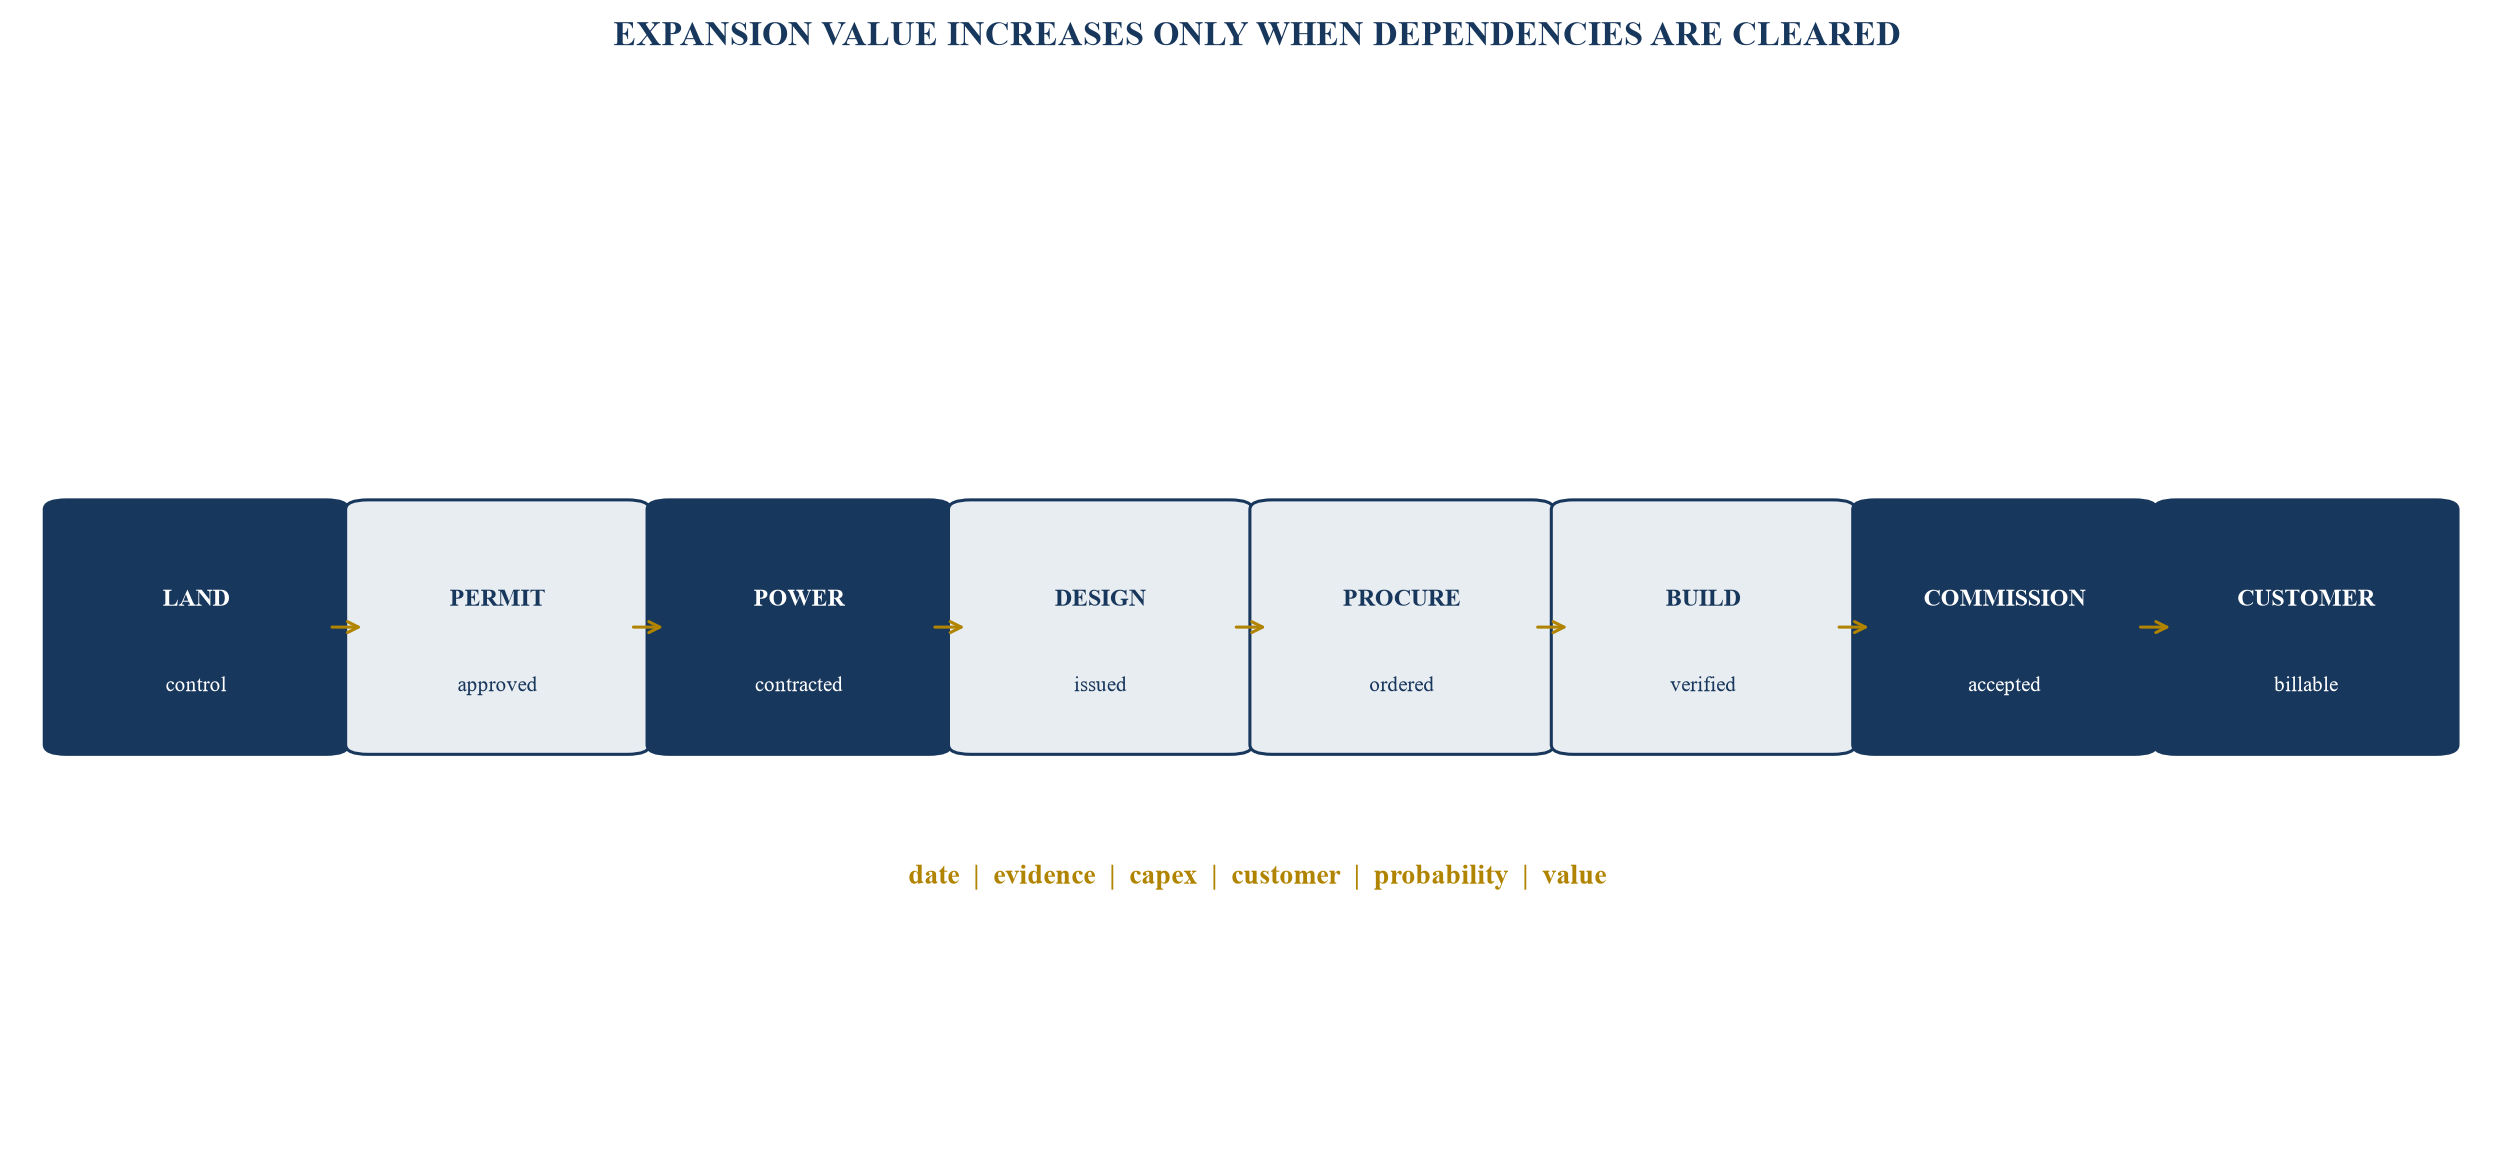
Each gate requires current evidence before capacity moves into a higher-confidence value state.
10. Rebuild capital expenditure from the bottom up
The capex bridge should separate spent cost, committed unpaid cost, forecast cost to complete, owner-supplied equipment, customer-funded work, capitalised interest, contingency, escalation, taxes and working capital. It should reconcile the engineering estimate, purchase orders, invoices, general ledger, payment certificates and budget.
Sunk cost is not proof of completion value. Some spending may relate to abandoned design, deposits at risk, related-party mark-ups or equipment that cannot be used in the buyer's plan. The buyer should test remaining scope and current pricing. Long-lead transformers, switchgear, generators, cooling equipment and controls need purchase-order, manufacturing, testing, shipping, customs, installation and warranty evidence.
The bridge should identify who funds tenant changes and options. A customer specification change can increase power density, cooling and fit-out cost. The contract may allocate this to the operator, customer or a negotiated change order. The valuation model should reflect recoverability and payment timing rather than assuming all growth capex earns the target return.
| Item | Base estimate | Diligence adjustment | Revised amount | Evidence required |
|---|---|---|---|---|
| remaining construction | 82 | 9 | 91 | quantity surveyor and contracts |
| electrical and grid works | 44 | 13 | 57 | utility scope and vendor orders |
| cooling and controls | 31 | 7 | 38 | issued design and quotations |
| customer fit-out | 22 | 5 | 27 | approved specification and recovery |
| contingency and escalation | 12 | 14 | 26 | risk register and schedule |
| total cost to complete | 191 | 48 | 239 | reconciled completion certificate |
Amounts are hypothetical and shown solely to demonstrate the reconciliation.
11. Separate operating value from rights and development value
Operating value should be based on sustainable cash from commissioned and accepted capacity. The buyer should normalise revenue, power margins, maintenance, staffing, insurance, rent, management charges and recurring capital expenditure. One-off credits, related-party pricing and capitalised operating costs require adjustment.
Contracted growth should be valued after capex, acceptance, delay and termination risk. Expansion without a signed customer requires a separate probability and leasing case. Power rights can support option value where transfer, timing and economics are evidenced; they should not be valued as operating capacity before delivery and commissioning.
The model should report value by site, phase and evidence state. This permits the investment committee to see how much price depends on operating cash, customer execution, grid delivery or speculative expansion. It also supports targeted protections rather than a single portfolio discount.
Comparable-company metrics need careful translation. Listed operators can disclose cabinets, square feet, megawatts, annualised recurring revenue, development space and future capacity using their own definitions.[21][22] Digital Realty states that rentable area depends partly on available power and required support space, and it separately reports active and future development. Equinix reports cabinet utilisation with power limitations and identifies phased projects. These disclosures show why a buyer should document the denominator and readiness state before applying a multiple.
Platform value should be separately evidenced. Management capability, customer relationships, procurement scale, development systems and a repeatable pipeline can support value beyond individual sites. The buyer should test employee retention, decision rights, systems, data ownership, vendor concentration and the historical conversion of pipeline into commissioned and leased capacity. A platform premium should be supported by repeatable capability and a funded opportunity set.
12. Build a rights-adjusted valuation waterfall
The waterfall begins with enterprise value from the agreed valuation method. It then adjusts for normalised operating earnings, debt-like items, working capital and tax in the usual transaction bridge. A second layer addresses sector-specific rights and completion findings: unsupported capacity, capex to complete, tenant-option burden, customer concentration, power defects, delayed energisation, equipment replacement and integration.
Deal protections should follow the finding. A known and measurable cost can adjust price. A pre-closing deliverable can become a condition precedent. A future outcome controlled partly by the seller can use an earn-out, escrow or holdback. A specific historic breach can use an indemnity. A continuing obligation can use a covenant, service agreement or direct agreement. Excluding the affected value remains appropriate when evidence is insufficient.
Acquisition financing should reconcile to the same downside case. Lenders may size debt against operating cash, contracted growth, asset value, completion risk and sponsor support using different eligibility rules. The buyer should identify which valuation adjustments reduce borrowing capacity, which conditions delay funding and which covenants could constrain integration or expansion. Financing certainty, hedging, security, cash control and mandatory prepayment terms should be reflected in both the sources-and-uses model and the acquisition agreement.
The equity bridge should include transaction fees, taxes, refinancing costs, break costs, working capital, capex, reserves and integration. A purchase price that fits the valuation can still exceed the available funding after these uses are included. The investment committee should see required equity under base, delay and combined downside cases and identify the funding source for customer or utility commitments that become payable shortly after closing.
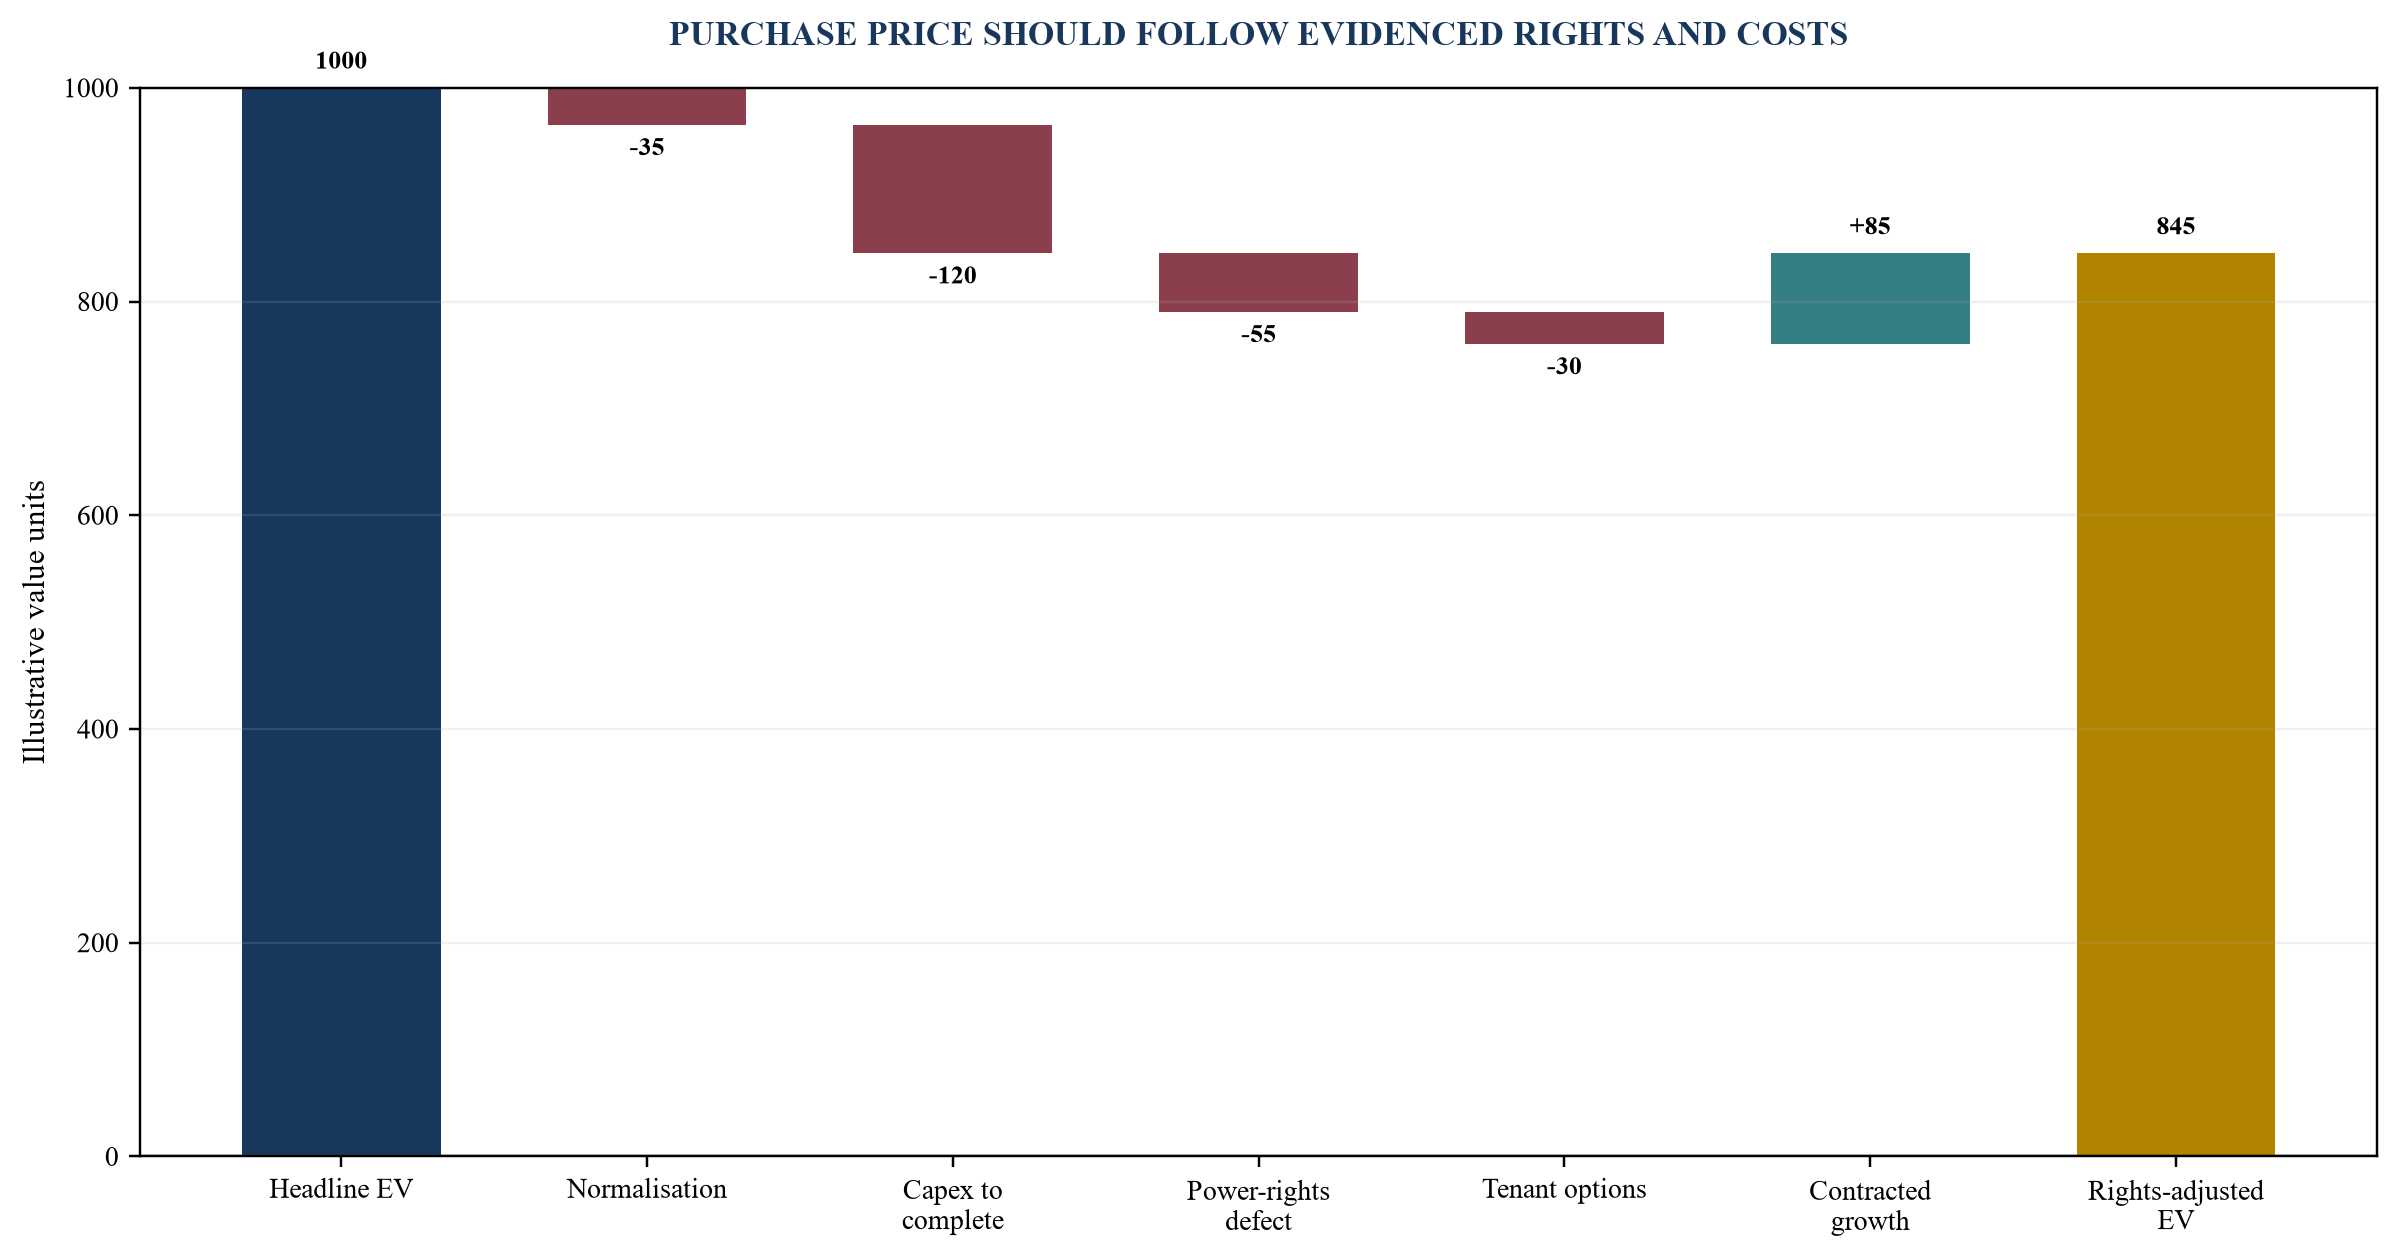
Amounts are hypothetical; a live transaction requires deal-specific valuation evidence.
13. Stress the dependencies together
Single-variable sensitivities can understate transaction risk because capacity, customer, capex and financing events interact. A grid delay can trigger customer termination, extend construction overhead, defer cash and weaken refinancing. A tenant contraction can release capacity that requires new fit-out and sales cost. A technology change can increase cooling capex and alter customer demand.
The acquisition model should include combined cases. A base case uses current contracted and operating evidence. A delay case moves grid, construction and acceptance dates. A customer case applies termination, contraction, credits and re-leasing cost. A technology case changes rack density, cooling, equipment and recurring capex. A combined downside should test liquidity, covenant headroom, equity requirement and recoverable value.
Probabilities should remain explicit management estimates unless supported by market or contract evidence. The decision paper should show the breakeven variables: maximum capex, latest energisation date, minimum retained MW, minimum renewal, maximum tariff and exit value. These thresholds become negotiation and monitoring priorities.
| Case | Capacity effect | Cash effect | Capital effect | Principal response |
|---|---|---|---|---|
| grid delay | commissioning deferred | revenue and collection delayed | overhead and interest increase | long-stop, holdback and liquidity |
| tenant contraction | committed MW falls | recurring revenue declines | re-fit and leasing spend | price and re-leasing plan |
| density change | usable MW may change | pricing and demand shift | cooling and electrical upgrade | customer-backed retrofit gate |
| tariff increase | capacity unchanged | margin declines under fixed pricing | efficiency spend may rise | pass-through and hedge review |
| combined downside | capacity and timing weaken | coverage and exit value fall | equity need increases | lower price, restructure or walk-away |
The directions show mechanisms; transaction values require current site-specific modelling.
14. Design the transaction documents around the findings
Representations should cover authority, title, contracts, utility rights, permits, compliance, customers, capital commitments, litigation, cyber, assets, financial statements and disclosed forecasts where negotiated. Materiality and knowledge qualifiers should match the diligence evidence and risk allocation. A broad representation cannot substitute for resolving a known defect.
Conditions precedent should be objective and controllable. Examples include utility or landlord consent, competition clearance, release of security, delivery of commissioning evidence, renewal of a key tenant, transfer of a licence or completion of specified works. The acquisition agreement should state the evidence and consequence of failure.
Purchase-price mechanisms should match the business. Completion accounts can address debt, cash and working capital. Locked-box structures require leakage protection and reliable accounts. Earn-outs can address future energisation, commissioning, customer acceptance or contracted growth; their definitions need control, accounting and dispute rules. Escrow and holdback can protect known completion or consent risks.
15. Plan regulatory and competition approvals early
The regulatory map should cover competition, foreign investment where relevant, sector licences, data and cyber obligations, land, utilities, environmental approvals and free-zone requirements. The buyer should identify filing parties, information, timetable, standstill obligations, remedies and long-stop interaction before signing.
European data-centre acquisitions can engage the EU Merger Regulation, national merger-control regimes, foreign-subsidy review, national foreign-direct-investment screening and sector-specific security rules.[20] The filing analysis should identify control, turnover, transaction value where applicable, relevant markets, jurisdictional nexus, timing, standstill obligations and potential remedies using current law and transaction facts.
Digital infrastructure can also fall within national-security, resilience, cyber and data-governance regimes. The NIS2 Directive includes data-centre service providers within digital infrastructure, subject to national implementation and entity classification.[19] Diligence should map the regulated entity, incident history, material suppliers, security measures, notification duties and change-of-control implications. A multi-country portfolio may require several national processes alongside EU review.
Competition work should connect legal filing analysis to commercial diligence. Relevant markets may turn on geography, service, customer type, connectivity, capacity or substitutability. Customer and competitor documents, market shares, pipeline and pricing can therefore be relevant to both valuation and regulatory review. The clean-team process should protect competitively sensitive data while permitting the advisers to assess concentration, overlaps and remedies.
Transaction timetables should use the longest credible approval path and include information-request risk. Signing documents should allocate cooperation, control of filings, remedy commitments, costs, interim conduct and long-stop rights. The operating team should understand restrictions during the standstill period, especially where capacity, customer contracts, capex and staffing continue to change between signing and closing.
16. Build the first 100 days before signing
Integration planning should protect uptime, customer trust and rights continuity. Day-one controls cover authority, bank accounts, system access, incident escalation, vendor contacts, utility relationships, customer communication and financial close. Critical staff, certifications, permits and service contracts need named owners.
The capacity ledger should become an operating control. Legal, engineering, sales and finance teams should use the same capacity identifiers and milestone states. Changes to power, construction, customer options and capex should update the ledger and valuation case. This converts diligence into portfolio management.
Synergy plans should separate revenue, procurement, network, energy, staffing, platform and capital effects. Each synergy needs a baseline, owner, cost, timing, customer impact and evidence. Capacity that can be sold across the combined platform may create value, while migration or standardisation can create downtime and capex. The integration committee should preserve a customer-safe path.
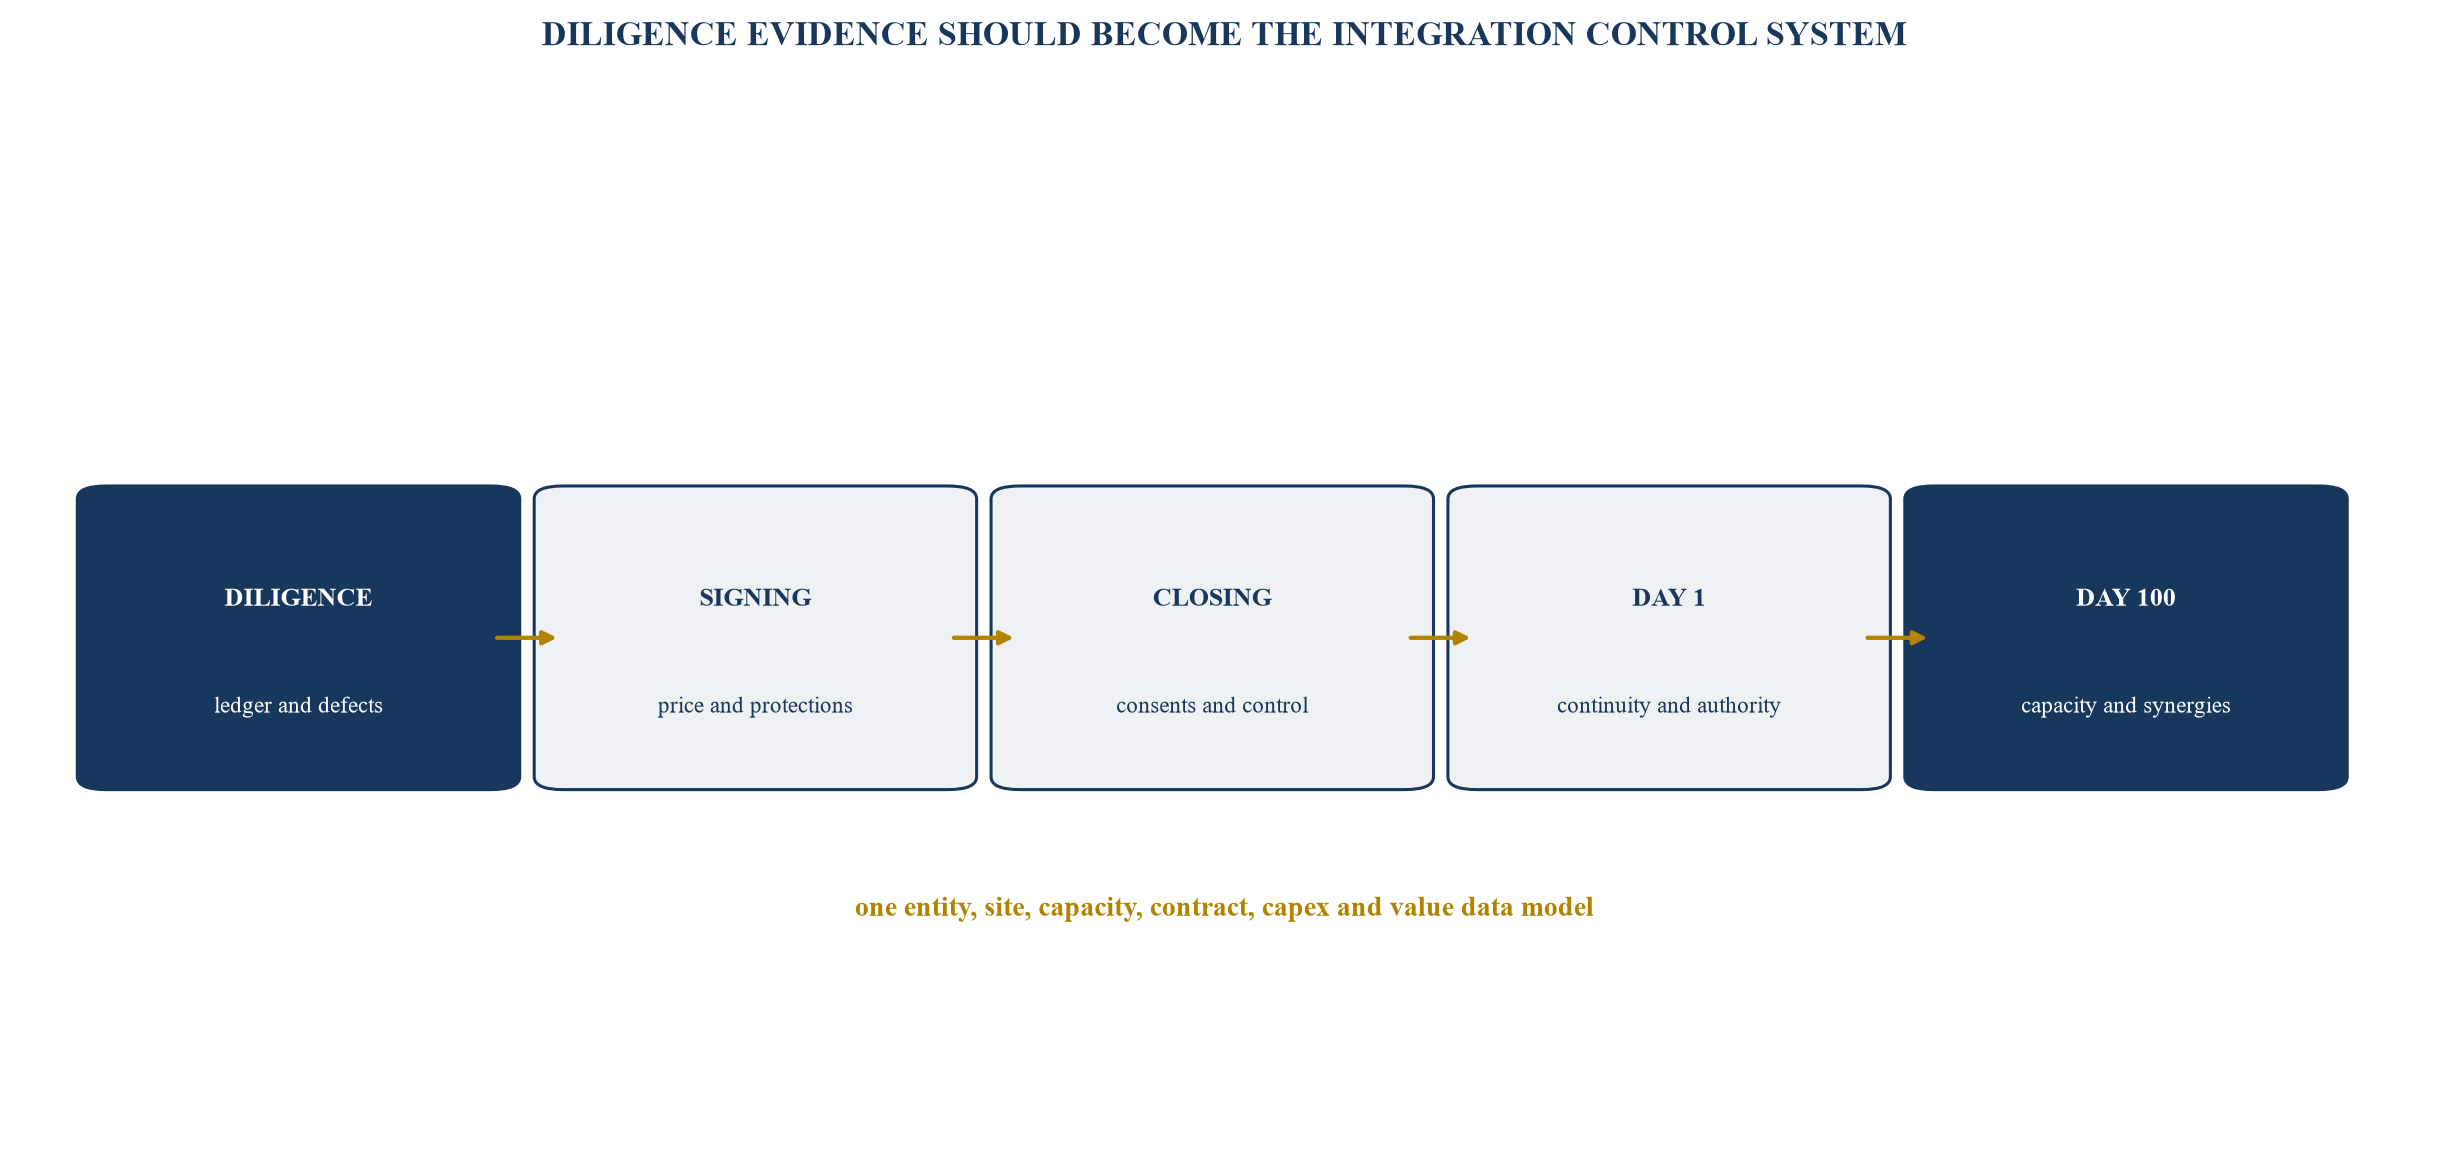
The same evidence model should continue through signing, closing and integration.
17. Use a gated acquisition process
Gate one confirms perimeter and evidence. The buyer maps entities, sites, rights, capacity, customers, assets and financial records. Missing evidence is logged with an owner and closing consequence. Gate two confirms operating value through commissioning, service, contracts, invoices and cash.
Gate three confirms power and expansion through agreements, technical studies, delivery works, permits, equipment, capex and schedule. Gate four converts findings into valuation, financing, approvals and documents. Gate five prepares closing and the first 100 days. Investment approval should state which risks are resolved, transferred, retained or excluded from value.
| Gate | Core question | Minimum output | Decision |
|---|---|---|---|
| perimeter | what rights and liabilities transfer? | entity and asset map | scope or restructure |
| operating value | which cash is commissioned, durable and collected? | capacity and cash reconciliation | sustainable earnings |
| expansion | which future MW can be delivered and funded? | rights map and capex bridge | probability-weighted value |
| transaction | how are findings allocated? | valuation waterfall and protections | price and documents |
| integration | how is continuity and value captured? | day-one and 100-day plan | owners and milestones |
A gate closes when the required evidence and decision treatment are documented.
18. Govern AI-supported diligence and decision evidence
AI can reduce the time required to assemble a power diligence record when it is connected to controlled source documents. Useful tasks include extracting dates and obligations from connection agreements, comparing modifications, reconciling capacity units, matching invoices to deposits, identifying inconsistent site names, classifying dependencies, summarising outage logs and running approved scenario calculations. The output should link back to the relevant page, field, meter interval or correspondence item.
Model risk rises when documents are incomplete, scanned poorly, multilingual, legally qualified or inconsistent. A generated summary should therefore remain a review aid. Legal counsel determines contractual meaning and transferability. Electrical engineers determine technical capacity, compliance and remediation. Valuers determine market value under their professional standards. The investment committee decides whether the risk and return meet mandate.
The transaction data room should preserve source files, hashes, versions, extraction rules, prompts or instructions where material, model versions, confidence, reviewer, correction and final approved field. Sensitive infrastructure, customer and security data should be processed under applicable confidentiality, cyber, data-protection and access controls. Applicable AI, data-protection and confidentiality law may affect particular systems and processing; transaction counsel should determine applicability.
AI should also be challenged for false consistency. Several documents can repeat the same unsupported date. A language model can present that repetition as corroboration unless provenance shows a common origin. The review workflow should require independent evidence for material assertions and should flag circular references, stale documents and management estimates.
| Task | Permitted analytical use | Required control | Decision owner |
|---|---|---|---|
| contract extraction | identify dates, capacities, obligations and clauses | page-level citation and legal review | transaction counsel |
| technical reconciliation | compare ratings, meters, tests and outage records | engineer-approved definitions and exceptions | technical adviser |
| queue dependency mapping | connect milestones, parties, works and dates | operator evidence and dated status | project director |
| scenario modelling | apply approved delay, load and capex assumptions | locked formulas, versioning and sensitivity | finance lead |
| anomaly detection | flag conflicts, missing fields and unusual events | materiality threshold and human disposition | workstream owner |
| investment summary | assemble approved findings and treatments | source links, reviewer sign-off and no autonomous approval | investment committee |
Automation supports evidence handling; professional and investment authorities remain accountable for decisions.
19. Limitations and research agenda
Public regulation, operator disclosures and industry evidence establish risk mechanisms and useful control categories. They do not establish the condition, transferability, cost, customer quality or value of a particular European portfolio. Utility and licensing practice can vary by country, system operator, distribution area, municipality, site and connection voltage. Current legal and technical advice is required.
Further research should examine observed European transaction pricing by evidence state, the value of transferable power rights, tenant-option exercise behaviour, re-leasing periods, capex by density and cooling architecture, and the effect of sovereign-cloud, data-residency and energy-efficiency requirements on contract durability. Comparable data should distinguish operating, development and platform value.
The framework can also be tested against post-acquisition outcomes. Buyers can compare diligence assumptions with actual energisation, commissioning, retention, capex, synergies and cash. This evidence can improve future probability weights and identify which documents and technical tests best predict value delivery.
20. Conclusion
European data-centre M&A requires a controlled link between rights, physical capacity, customer obligations, capital and cash. Headline megawatts and pipeline descriptions are starting points. Purchase price should reflect the subset that the buyer can legally control, technically deliver, commercially use and finance.
The proposed system uses five schedules. The capacity ledger defines evidence state. The power-rights map tests delivery and transfer. The tenant-option matrix identifies who controls future cash and capacity. The capex bridge measures the remaining funding requirement. The valuation waterfall converts the findings into price and protections.
The method also improves execution after closing. The same identifiers and evidence used in diligence become the operating control for power, construction, leasing, capex and integration. A buyer that maintains this chain can distinguish verified operating value from conditional growth, intervene before milestones fail and allocate capital to the capacity most likely to become durable cash.
Sources
- International Energy Agency, Energy and AI, 2025. Read the primary source
- International Energy Agency, Energy and AI: Executive Summary, 2025. Read the primary source
- International Energy Agency, Energy Demand from AI, 2025. Read the primary source
- International Energy Agency, Data-centre electricity use surged in 2025 even with tightening bottlenecks, 2026. Read the primary source
- European Commission, AI Continent Action Plan. Read the primary source
- European Commission, AI Gigafactories. Read the primary source
- European Commission, Energy performance of data centres. Read the primary source
- European Commission, EU-wide scheme for rating the sustainability of data centres, 2024. Read the primary source
- EUR-Lex, Directive (EU) 2023/1791 on energy efficiency. Read the primary source
- EUR-Lex, Commission Delegated Regulation (EU) 2024/1364 on data-centre reporting. Read the primary source
- National Energy System Operator, Connections Reform Results. Read the primary source
- National Energy System Operator, Setting out the timeline for Connections Reform. Read the primary source
- National Energy System Operator, Queue Management. Read the primary source
- Commission for Regulation of Utilities, Decision on New Electricity Connection Policy for Data Centres. Read the primary source
- Commission for Regulation of Utilities, Review of Large Energy Users Connection Policy. Read the primary source
- European Commission, Grids, the missing link: An EU Action Plan for Grids. Read the primary source
- European Union Agency for the Cooperation of Energy Regulators, Market Monitoring Report. Read the primary source
- ENTSO-E, Ten-Year Network Development Plan 2024. Read the primary source
- EUR-Lex, Directive (EU) 2022/2555 on measures for a high common level of cybersecurity across the Union. Read the primary source
- EUR-Lex, Council Regulation (EC) No 139/2004 on the control of concentrations between undertakings. Read the primary source
- Digital Realty Trust, Inc., Form 10-K for the year ended 31 December 2025. Read the primary source
- Equinix, Inc., Form 10-K for the year ended 31 December 2025. Read the primary source
