
Introduction
Cooling is part of the revenue engine of a data centre. It protects computing equipment, determines attainable rack density and influences the amount of contracted capacity that can be delivered through extreme ambient conditions. In a hot, water-constrained market, cooling also creates claims on two public systems: electricity and water. A transaction model that treats cooling as a fixed percentage of operating cost misses capacity, retrofit and stranded-asset risk.
India combines varied ambient conditions, accelerating artificial-intelligence infrastructure and state-specific power and water constraints. Government releases identify rapid capacity growth, rising electricity demand and adoption of advanced cooling for high-density racks. These conditions make utility capacity, source quality, tariff structure and emergency continuity material to project finance. [1][2][3]
The governing transaction question is deliverable computing capacity after cooling constraints. Installed megawatts, building shell and grid connection are incomplete measures. The buyer needs hourly information-technology load, cooling topology, design temperatures, water balance, electricity profile, maintenance history, water and discharge rights, customer specifications, retrofit cost and evidence of performance in the hottest operating window.
Water and cooling also affect the sequencing of development capital. Land and grid rights can be secured before the final customer load is known, while water pipelines, dry-cooling equipment and high-density liquid loops require early design choices. An investor therefore needs a stage-gated view of value: site feasibility, utility allocation, customer qualification, completed construction, commissioned capacity and paid operation. Each stage should have its own evidence threshold and capital-at-risk limit.
1. Define the financing perimeter
State whether financing covers a greenfield AI module, a retrofit, customer equipment, shared mechanical plant or an acquisition-linked expansion. Identify which legal entity owns the land, grid connection, building, cooling plant, information-technology equipment, customer contracts and operating licences. Set the financing date, construction period, commissioning standard, stabilization test, repayment profile and sponsor-support period.
Separate base-building expenditure from high-density incremental expenditure. The first category includes land, shell, common electrical systems and conventional cooling. The second includes rack-level liquid loops, cooling distribution units, facility-water upgrades, dry coolers or towers, controls, leak detection, water treatment and customer-specific commissioning. This separation supports asset eligibility, security, useful-life analysis and drawdown evidence.
Define the cash recipient and repayment source. Contracted colocation revenue, managed-compute revenue, customer prepayments, utility incentives and sustainability-linked margin adjustments have different credit characteristics. The lender should identify the obligor, minimum commitment, acceptance test, billing unit, termination right, credit support, currency and collection account for each material source.
2. Map the complete thermal chain
Trace heat from processors and accelerators through cold plates or air handlers, rack manifolds, cooling distribution units, facility water loops, heat exchangers, chillers, cooling towers, dry coolers and the external environment. Record temperatures, flow, pressure, redundancy, control logic, chemical treatment, leakage detection and failure modes at each boundary.
Direct-to-chip cooling does not by itself prove zero water consumption. The internal loop can be closed while the facility heat-rejection stage uses evaporative towers. Conversely, a dry cooler can avoid operational water while consuming more electricity during high ambient temperatures. The diligence model must describe both loops and the transfer point between them. [5][6][7]
3. Build the facility water balance
Reconcile incoming potable, desalinated, recycled and process water to cooling make-up, humidification, cleaning, sanitary use, treatment losses, drift, evaporation, blowdown and discharge. Obtain monthly meter records and hourly data for peak months. Tie volumes to invoices, laboratory results, chemical-treatment logs and discharge records.
Water Usage Effectiveness divides annual site water use by information-technology energy. It creates a comparable intensity measure, subject to boundary and source definitions. A transaction review should retain absolute volume because a low WUE applied to a very large computing load can still require material water infrastructure. [5][6]
Reconcile design values with actual operating mode. Cooling towers can cycle concentration and blowdown differently as source-water chemistry changes. Leaks, bypasses, failed sensors and manual overrides can produce material variance from design. Calculate WUE by month and by hall, then bridge the result to weather, load and maintenance events. This creates an auditable baseline for retrofit savings and identifies whether the forecast assumes correction of current operational defects.
4. Separate withdrawal, consumption and discharge
Withdrawal measures water taken from a source; consumption measures the portion not returned to the same watershed or system; discharge measures water released after use. Evaporative cooling can have high consumption because water leaves as vapour. Once-through systems can have lower consumption but high withdrawal and significant discharge obligations.
These distinctions affect tariffs, permits, public reporting and stakeholder claims. The buyer should reconcile each metric to the relevant regulator and contract. A sustainability statement based on withdrawal reduction should not be modelled as a consumption reduction unless the measured boundary supports it.
5. Separate financeable assets and operating costs
Classify project uses by ownership, mobility, useful life and cash-flow contribution. Long-life facility assets may support senior project debt. Replaceable cooling distribution units, pumps and controls may fit equipment finance or vendor credit. Customer-dedicated fitout may be funded through prepayments, committed-capacity charges or amortizing service fees. Software subscriptions, consumables and operating labour belong in the operating model.
Create an asset register that records supplier, purchase currency, delivery date, warranty, performance guarantee, replacement cycle, security interest, insurance and permitted relocation. Imported equipment creates foreign-currency, customs, logistics and spare-parts exposure. A rupee revenue stream should not carry an unmeasured foreign-currency repayment or replacement obligation.
Financing eligibility should follow evidence. A purchase order is not an installed asset. An installed asset is not commissioned capacity. Commissioned capacity is not customer-accepted service. The borrowing base should recognize each stage at a deliberately different advance rate and require sponsor equity or completion support for the gap.
6. Test water rights and utility capacity
Obtain the executed connection agreement, allocated capacity, tariff schedule, meter class, curtailment provisions, quality specification, notice rights and change-of-control terms. Confirm that stated capacity is reserved for the asset and not shared informally across a campus. Compare contracted daily volume with design-day demand and emergency storage.
A utility letter, construction drawing and paid bill prove different things. Build an evidence ladder from indicative availability through binding allocation, completed connection and paid operation. Value should increase only when the evidence supports the relevant stage.
7. Apply India's infrastructure and resource context
Government information released in March 2026 states that Indian data-centre capacity rose from about 375 MW in 2020 to around 1,500 MW in 2025 and that electricity demand from data centres could reach 13.56 GW by 2031-32. It also identifies more than 38,000 GPUs onboarded through the IndiaAI compute framework. These national figures establish scale and direction; a financing decision still requires state, utility, site and customer evidence. [1][3]
State-level conditions determine bankability. Verify sanctioned electrical load, connection milestones, feeder redundancy, open-access eligibility, renewable-energy arrangements, water source, groundwater restrictions, discharge permission, fire approvals, building approvals and local incentives. Record which approvals attach to the site, project company, operator or customer and whether they survive enforcement or change of control.
The financing model should distinguish announced investment from committed funding, contracted demand and paid use. A policy objective, tax provision or industry forecast can support market context. It cannot replace a binding utility right, signed customer obligation or funded construction plan.
8. Price power, water and foreign-currency dependencies
Build an all-in electricity schedule comprising energy, demand, network, wheeling, balancing, banking, standby, losses, taxes and renewable-energy costs. Cooling choices change both annual energy and peak demand. Dry heat rejection may reduce water dependence and increase electrical exposure during the hottest hours. Liquid cooling may reduce fan energy while adding pumps and controls. Model the complete facility effect.
For imported chillers, cooling distribution units, heat exchangers, pumps, controls and spares, record the contract currency, hedge, payment milestones, delivery terms and warranty jurisdiction. Match foreign-currency debt or vendor credit to an evidenced hedge or foreign-currency revenue. Include customs, delay, replacement and trapped-spares scenarios.
Water cost should include connection, fixed charges, volumetric tariff, treatment, storage, discharge and contingency supply. A low reported tariff can conceal pipeline capex or interruption exposure. The lender should review the executed agreement and physical capacity rather than rely on a published schedule alone.
9. Test water sourcing and discharge feasibility
Recycled water can reduce potable-water demand, yet availability, quality and network proximity may be uncertain. Review source plant capacity, seasonal supply, pipeline route, storage, treatment specification, corrosion potential, biological control, customer restrictions and discharge compatibility. Identify the party funding connection and pretreatment.
Model recycled water as an operating input only after confirming binding supply, quality and completion. Before that point it is a development option with probability-weighted capex and schedule. The the relevant Indian state policy framework supports technical and economic evaluation of this source. [10][11][15]
10. Establish the hourly computing-load profile
Cooling demand follows actual processor load, rack density and operating mode. Obtain interval information-technology power, total facility power, coolant temperatures, pump loads and external ambient data. Separate installed, commissioned, occupied, reserved and billed capacity. Test the ramp schedule for each customer and hall.
AI workloads can change thermal density faster than building occupancy. A 12 MW facility operating at 70 per cent average load produces a different water and power profile from a fully loaded facility with the same nameplate. The cooling model should use hourly load and credible customer ramps.
11. Reconcile WUE, PUE and useful computing
Water Usage Effectiveness and Power Usage Effectiveness can move in opposite directions. Evaporation can reduce mechanical-cooling electricity; dry rejection can reduce water while increasing compressor or fan energy. Compare both metrics under the same weather, workload and boundary.
Add a useful-computing denominator where hardware and workload data permit. ASHRAE's AI data-centre framework identifies WUE, Water Usage Impact, PUE, carbon metrics and information-technology work capacity. The investment committee should avoid rewarding an intensity improvement caused by lower utilization or a shifted boundary. [5]
12. Model ambient temperature and humidity
Use hourly dry-bulb and wet-bulb weather data, including design extremes and projected hotter cases. Evaporative systems depend on wet-bulb conditions; air-cooled chillers and dry coolers lose efficiency as dry-bulb temperature rises. Record the number of hours at which the plant approaches design limits.
Model coincident heat and computing peaks. A cooling design that performs efficiently on annual averages may constrain capacity during the most valuable hours. Test degradation, fouling, sand, salt, dust and air-filter loading where relevant to the site.
Climate scenarios should inform sensitivity rather than become a single deterministic forecast. Use observed weather for the operating baseline, design weather for equipment capacity and a hotter stress case for investment resilience. Record which weather station, period and percentile supports each input. Where a site depends on coastal air or seawater, include humidity, salinity and corrosion implications alongside temperature.
13. Classify liquid-cooling readiness
Inspect rack manifolds, piping, cooling distribution units, heat exchangers, leak detection, water chemistry, controls and redundancy. Confirm which ASHRAE liquid-cooling temperature class the system can support and which customer hardware has been qualified. Review warranties and responsibility at the facility-to-equipment boundary.
ASHRAE identifies W17, W27, W32, W40, W45 and W+ classes, named for maximum facility liquid-supply temperature. Higher-temperature systems can create more opportunities for chiller-free operation, subject to equipment and climate. The target's design and acceptance tests determine value. [5][6]
14. Compare four cooling architectures
Compare conventional evaporative rejection, hybrid towers, closed-loop air-cooled chillers and direct-to-chip liquid cooling with dry rejection. Score each against water use, peak power, rack density, capex, maintainability, redundancy, vendor concentration, retrofit disruption and customer acceptance.
Architecture labels can conceal mixed systems. A direct-to-chip facility may retain evaporative towers for heat rejection; a hybrid plant may consume water only above a threshold. Model actual modes by hour rather than assigning one annual marketing label.
15. Test the zero-water claim
Microsoft describes a new design that recirculates water in a closed loop and avoids operational water evaporation, with expected savings exceeding 125 million litres per year per data centre relative to its fiscal-year 2024 average. It also states that mechanical cooling can increase power use and that warmer liquid temperatures help mitigate the penalty. [7][8]
Use this as evidence of technical direction. For a target asset, verify make-up water, humidification, cleaning, leaks, commissioning, sanitary use and heat rejection. Define whether zero applies to cooling consumption, cooling withdrawal or the whole facility.
16. Quantify the power penalty
Build an hourly cooling-power model for pumps, fans, chillers, towers, cooling distribution units and controls. Test tariff periods, demand charges, grid constraints and backup-generation implications. A water-saving retrofit can reduce deliverable information-technology capacity if the electrical connection cannot support the added load.
Calculate marginal PUE and incremental megawatt-hours for each cooling mode. Link power assumptions to the signed tariff and meter history. Include degradation and part-load performance rather than relying only on design efficiency.
Test whether cooling power competes with computing load under a capped grid connection. The economic cost can exceed the electricity bill when an additional cooling megawatt displaces billable information-technology capacity. Model both outcomes: purchased energy where headroom exists, and lost or deferred customer capacity where it does not. Include the capex and timing of any grid reinforcement required to preserve load.
17. Link cooling capacity to billable rack capacity
Cooling creates value when it preserves contracted computing output during the hottest hours. Map thermal headroom to customer service levels, liquidated damages, credits and termination rights. Determine whether the facility can derate workloads, shift them, use redundant equipment or tolerate higher inlet temperatures.
Avoid assigning a general resilience premium. Value the expected avoided cash loss under evidenced contracts, outage history and probability. Record any customer-specific capacity reservation or qualification that depends on the cooling design.
18. Verify AI customer qualification and acceptance
Obtain technical schedules for rack density, coolant temperatures, water chemistry, pressure, redundancy, maintenance and telemetry. Confirm whether target customers have accepted the architecture through design review, factory tests, commissioning and operating history. Unqualified cooling capacity is development inventory rather than contracted operating capacity.
Customer concentration can magnify design risk. A system optimized for one accelerator generation or vendor may require retrofit for another. Review change provisions and who funds customer-driven upgrades.
19. Map permits, discharge and environmental obligations
Compile water connection, abstraction, recycled-water, chemical storage, blowdown, discharge, noise, refrigerant, construction and environmental permits. Reconcile permit limits to design-day operation. Confirm monitoring, sampling, reporting and renewal obligations.
the relevant Indian state's water-management policy references water-quality, recycled-water, trade-effluent, marine-discharge and district-cooling technical rules. A data-centre transaction requires its own legal mapping; this policy demonstrates the range of interfaces that can affect heat-rejection infrastructure. [11][15]
20. Test physical resilience and redundancy
Review N, N+1 or 2N configuration for chillers, towers, pumps, cooling distribution units, heat exchangers, pipes and controls. Test common-mode dependencies such as one water main, one treatment plant, one control system or shared electrical switchgear. Inspect isolation, bypass and black-start procedures.
Compare design redundancy with maintenance records and actual failover tests. A redundant component adds little value when valves, controls or electrical supply create a single point of failure.
21. Build the lifecycle capex schedule
Separate remaining construction cost, deferred maintenance, expansion capex, customer-fit-out capex and technology-conversion capex. Record equipment age, operating hours, maintenance cycles, refrigerants, spare parts, vendor support and replacement lead times.
Model towers, chillers, dry coolers, pumps, heat exchangers, cooling distribution units, controls and water-treatment assets separately. Cooling assets can have different useful lives from the building and customer lease. Use evidence from condition assessments and service contracts.
22. Model the retrofit pathway
Define phases by hall, load and customer window. Identify shutdown requirements, temporary cooling, design approvals, procurement, commissioning tests and rollback plans. Link expenditure to objective milestones and retained contract capacity.
Retrofit value depends on execution while the facility earns revenue. A theoretically superior system can destroy value through downtime, schedule delay or lost customer qualification. Include owner engineering, contingency, interest during construction and revenue interruption.
Create a hall-by-hall migration plan with temporary cooling and reversible cutover points. Link payments to design approval, factory acceptance, delivery, installation, integrated systems testing and sustained performance. Confirm access to long-lead equipment and specialist labour. The acquisition agreement and financing documents should use the same milestone definitions so that completion risk does not fall between contractual regimes.
23. Apply the hypothetical financing case
The hypothetical project comprises a 12 MW high-density AI module designed for rack densities up to 100 kW. Average information-technology load at stabilization is 8.4 MW and annual information-technology energy is approximately 73.6 GWh. Total uses are INR 720 crore: INR 250 crore for electrical and base mechanical works, INR 140 crore for liquid-cooling and heat-rejection systems, INR 180 crore for customer and rack fitout, INR 90 crore for commissioning and development costs, and INR 60 crore for contingency and financing costs.
Funding comprises INR 350 crore of senior term debt, INR 180 crore of equipment finance, INR 150 crore of sponsor equity and INR 40 crore of customer prepayments. Sponsor equity funds early design, permits and deposits. Senior debt draws against certified construction milestones. Equipment finance draws against delivered, insured and accepted equipment. Customer prepayments remain restricted to the relevant capacity until acceptance.
At stabilization, hypothetical annual revenue is INR 360 crore and operating cost is INR 198 crore, producing INR 162 crore of EBITDA. Scheduled annual debt service is INR 98 crore, producing debt-service coverage of 1.65 times. The model is a financing illustration and does not describe market pricing, an investment offer or the expected performance of an identified project.
24. Run completion and utilization downside cases
Run separate construction-delay, capex-overrun, customer-delay, utilization, price, power-cost, water-restriction, equipment-failure and combined cases. The combined hypothetical downside assumes a nine-month delay, 20 per cent capex overrun, billable utilization below plan, weaker realized pricing and higher power cost. EBITDA falls to INR 90 crore while annual debt service remains INR 98 crore, producing 0.92 times coverage before cure actions.
The downside requires additional sponsor equity, a larger interest-during-construction reserve, extended principal grace or reduced debt. These remedies have different allocation effects. A grace extension preserves liquidity but may increase total interest. Additional equity reduces leverage. A cash sweep accelerates deleveraging after stabilization. A lender should not solve a permanent utilization problem solely with temporary liquidity.
Model the timing of customer acceptance and receivables separately from accounting revenue. Cooling performance may be proven before the customer's computing environment is ready, or computing service may begin before final efficiency targets are tested. Drawdown, repayment and margin ratchets should specify which milestone controls each consequence.
25. Build the integrated cash-flow model
Model capacity revenue, customer premiums, avoided downtime, water, treatment, chemicals, electricity, maintenance, insurance, permits, capex, taxes and financing. Use monthly periods through retrofit and ramp, then annual periods. Separate cash flows by legal entity and contract.
Drivers should include information-technology load, WUE, PUE, ambient temperature, water source mix, tariff, power price, capex, schedule, customer acceptance and availability. Reconcile physical units before monetizing them.
26. Size senior debt to verified cash flow
Size senior debt to cash available for debt service after power, water, operations, maintenance, leases, taxes, sustaining capex and required reserves. Use contracted minimum revenue and an evidence-weighted ramp. Exclude unsigned pipeline, unapproved incentives and uncommitted sponsor support from the base case.
Test minimum and average debt-service coverage, loan life coverage, project life coverage, leverage, interest cover and closing liquidity. The applicable metric depends on the borrower and structure. A corporate facility may rely on diversified cash flows and balance-sheet covenants. A project or ring-fenced facility requires tighter completion, account, distribution and reserve controls.
Match amortization to the slower of customer-contract life, equipment useful life and proven cash-flow ramp. Retain refinancing risk where maturity precedes the expected asset life. Do not assume terminal value will refinance a project whose technology, customer or power position has not been demonstrated.
27. Build the sources-and-uses and claims waterfall
Reconcile every use with a committed source and draw condition. The hypothetical INR 720 crore project uses INR 350 crore of senior debt, INR 180 crore of equipment finance, INR 150 crore of sponsor equity and INR 40 crore of customer prepayments. Identify which source funds taxes, contingency, overruns, interest during construction and replacement equipment.
Map claims in enforcement and ordinary operation. Senior lenders may hold security over project accounts, receivables, shares and eligible fixed assets. Equipment financiers may retain title or asset-specific security. Customers may hold refund, service-credit or capacity rights. Vendors may have retention-of-title, warranty or suspension rights. These claims can overlap and require intercreditor treatment.
The equity bridge should deduct funded debt, lease-like liabilities, unpaid capex, vendor claims, customer refunds and restricted cash from enterprise value. Do not treat restricted customer prepayments as free cash. A financing package is sustainable when sources, uses, security and cash waterfalls describe the same legal and economic perimeter.
28. Apply accounting and impairment discipline
IFRS 13 requires market-participant assumptions under current market conditions. IAS 36 requires reasonable and supportable cash-flow assumptions and recognizes that regulatory or environmental change can indicate impairment. Cooling valuation should reflect current asset condition and separately identify uncommitted enhancement capex. [23][24]
Under IFRS 3, determine whether customer contracts, permits, software or other rights meet identifiability criteria. Avoid double counting between property, plant, customer relationships, contract-based intangibles and goodwill. Tie purchase-price allocation to evidence.
29. Assess debt capacity
Establish draw conditions for design, permits, power, water, equipment, construction, commissioning, customer acceptance and collection. Require an independent engineer to confirm technical milestones and a financial model auditor to confirm model integrity where appropriate. Define cost-to-complete tests before every material draw.
Completion support should cover delay, overrun, performance shortfall and missing customer acceptance until the agreed completion test is met. Possible forms include sponsor equity commitments, guarantees, letters of credit, standby facilities and restricted reserves. Their value depends on enforceability, tenor, ranking and provider credit quality.
Operating covenants should address minimum coverage, leverage, liquidity, permitted debt, distributions, capex, insurance, hedging, customer concentration, vendor concentration, maintenance and reporting. Technical covenants should preserve safe operating limits and permit necessary optimization. An overly rigid efficiency covenant can create operational risk if it ignores weather, load mix and customer requirements.
30. Convert diligence into financing conditions
Translate unresolved diligence into conditions precedent, conditions subsequent, reserves, pricing, covenants and draw limits. A missing final power agreement may block financial close. A pending customer acceptance test may restrict the final equipment draw. A vendor warranty assignment may be a condition to commissioning. An untested water contingency may require a reserve and remedial milestone.
Milestones should be objective, evidenced and linked to a defined consequence. Avoid conditions based only on management satisfaction. Use signed documents, independent certificates, meter records, accepted tests and bank receipts. State cure periods, waiver authority and the effect on interest, distributions, further drawings and enforcement.
Preserve a single completion definition across the loan agreement, equipment facility, customer contract, construction contract and financial model. Conflicting completion definitions create gaps in funding and accountability precisely when the project is most exposed.
31. Test security, assignment and step-in rights
Review security over land or lease rights, project-company shares, bank accounts, receivables, insurance, material contracts and movable equipment. Confirm registration, perfection, priority and enforcement requirements under applicable Indian law. Obtain specialist advice for each transaction.
Test assignment and step-in rights under power, water, network, construction, operations, cooling-vendor and customer agreements. A lender may have security over equipment and still lack the licence, software, data, spares or qualified personnel needed to operate it. Direct agreements should address notice, cure, continuity and transfer where commercially available.
Separate physical portability from economic portability. Rack-level equipment may be movable, while site-specific pipework, electrical distribution and heat-rejection assets may have low recovery value. The advance rate and amortization should reflect installed recoverability, removal cost, remarketing market and technology obsolescence.
32. Evaluate vendor and technology concentration
Identify sole-source cooling distribution units, control software, pumps, valves, refrigerants and specialist service providers. Review intellectual property, source code access, cybersecurity, spare parts, training and alternative suppliers.
Technology concentration can create both performance and replacement-cost risk. Model a vendor failure or product discontinuation. Confirm whether customer warranties require an approved vendor.
33. Use AI controls as measured operating evidence
The Government of India announced a 2026 pilot with Khazna and Agility to evaluate AI control agents across data-centre and district-cooling operations. The stated aims include lower cooling energy, higher information-technology capacity and greater resilience in high ambient temperatures. Results require measured evidence when available. [18]
For a target using optimization software, inspect training data, sensors, control boundaries, fallback modes, human oversight, model-change governance and actual before-and-after performance. Value verified savings and capacity, not the presence of an AI label.
Separate automated advisory recommendations from direct control. Record the permitted operating envelope, safety interlocks and responsibility for overrides. Test performance across seasons and maintenance states, not only a selected demonstration period. Where the supplier receives operating data, review data rights, cybersecurity, confidentiality, export, service continuity and termination assistance. Any value attributed to proprietary optimization should survive vendor failure and change of control.
34. Reconcile sustainability claims
Tie public claims to water meters, energy meters, invoices, discharge records, source classification and calculation methodology. Confirm reporting boundary, baseline, renewable-energy treatment and whether avoided water is potable, desalinated or recycled.
Separate operational reductions from replenishment projects and purchased attributes. Each can be useful, though they represent different cash, physical and reputational outcomes.
35. Separate contracted cash flow from sponsor upside
Stand-alone value includes benefits available to a market participant under existing rights and funded plans. Buyer synergies may include portfolio procurement, shared control centres, preferred technology, customer relationships, data aggregation and financing scale.
Do not transfer all synergy into seller value. The purchase model should identify execution cost, timing, probability and which party created the opportunity. Preserve headroom for integration risk.
36. Establish post-closing value control
Create a monthly dashboard for information-technology load, rack density, WUE, PUE, water source, withdrawal, consumption, discharge, peak cooling power, temperature compliance, downtime, customer credits, capex and permit status. Assign accountable owners and escalation thresholds.
Compare actual results with the acquisition model and debt case. Maintain calibration, change control and audit trails. Reforecast when load, tariffs, weather, customer requirements or retrofit milestones move.
The dashboard should retain both numerator and denominator for every efficiency measure. A reported improvement in WUE can arise from a genuine reduction in water withdrawal, a change in computing load, a boundary change or a meter failure. The control process should therefore reconcile facility water, cooling-system water, information-technology electricity, total facility electricity and billable computing output. Finance should connect the same period to utility invoices, customer billing, service credits and maintenance expenditure. Engineering should explain weather normalization, operating mode and exceptional maintenance. This creates a common record for the board, lenders and customers.
Post-closing capital approval should use explicit gates. The first gate confirms design basis, utility rights and customer requirements. The second confirms vendor scope, outage plan, guarantees and contingency. The third confirms commissioning evidence and customer acceptance. The final gate releases retained consideration or project reserves only after the agreed measurement period. A failed gate should trigger a documented response: remedial work, revised operating limits, additional capital, a price mechanism or abandonment of the affected phase. The governance design turns the valuation assumptions into accountable operating decisions.
37. Frame the investment-committee decision
The committee should approve a price and funded operating plan, not a cooling slogan. State which water and power rights are proven, which capacity is customer-qualified, which retrofit is committed and which benefits remain contingent. Present central, downside and no-retrofit cases.
The final record should identify evidence, assumptions, legal advice, engineering reliance, conflicts, open conditions and monitoring owners. Where water or cooling evidence is incomplete, reduce base value and preserve the option through contingent consideration or staged capital.
The committee paper should show a clean bridge from physical capacity to cash. Begin with installed information-technology capacity, reduce it for commissioning, redundancy and thermal constraints, then identify customer-qualified and billable capacity. Reconcile the resulting load with annual water withdrawal, electricity demand, cooling operating cost and customer revenue. Show the retrofit as a separate investment with its own capex, completion date, performance test and financing. This prevents a buyer from paying for both unproven capacity and the capital required to make that capacity usable.
Decision rights should match exposure. Engineering should sign the thermal design and performance evidence. Legal advisers should identify the enforceability and transferability of water, power, discharge, customer and vendor rights. Finance should own the cash-flow reconciliation, valuation bridge and funding plan. Operations should own commissioning, maintenance and contingency procedures. The investment committee should approve the unresolved-risk treatment and the maximum capital at risk before each gate. A single named executive should be accountable for the integrated outcome because water, power, customers and financing can fail together.
Appendix A. Cooling project-finance model
Begin with hourly information-technology load and ambient weather. Select cooling mode by operating rule. Calculate pumps, fans, chillers, towers and control power; calculate make-up, evaporation, drift, blowdown and discharge; then apply tariffs, treatment, maintenance and customer economics.
The model should distinguish facility cost, customer revenue, avoided loss and project financing. Reconcile monthly meters and invoices to cash. Use a transparent scenario register for weather, load, WUE, PUE, tariffs, capex and completion.
For each month, calculate information-technology electricity from installed capacity, utilization and hours. Apply the cooling architecture to derive cooling-system power and total facility power. Calculate water withdrawal from the selected WUE boundary and show consumption, discharge and treatment separately. Price each source using the contractual tariff, fixed charge, connection cost and escalation rule. Add maintenance, consumables, chemicals, specialist labour, software and insurance. Customer benefit should enter the model only where the technical requirement, commercial consideration and collection route are evidenced.
The valuation schedule should then translate operating cash into enterprise value and equity value. It should identify sustaining capex, expansion capex, retrofit capex, tax, working capital, debt service, leases, vendor finance, reserves and contingent claims. Scenario logic should preserve physical relationships. Higher dry-cooling use may reduce water while increasing power. Greater computing load may improve revenue while increasing heat rejection. A delayed retrofit may defer capital and also defer customer qualification. Every scenario should include a short written explanation of these linked effects.
Appendix B. Minimum confirmatory evidence
Technical evidence includes design drawings, equipment schedules, hydraulic models, weather files, rack-density plans, commissioning tests, capacity tests, water balance, energy meters and maintenance records. Commercial evidence includes utility contracts, tariffs, water bills, customer technical schedules, credits and service-level history.
Legal evidence includes permits, licences, easements, discharge consents, change-of-control provisions, warranties and insurance. Financing evidence includes debt documents, leases, security, completion tests and reserves. Grade every item by source, date, owner and reconciliation status.
The confirmatory process should include meter sampling and a period reconciliation. Select representative high-load, low-load and hot-weather periods. Trace raw meter readings through the building-management system, sustainability report, utility invoice and management accounts. Inspect sensor calibration and missing-data rules. Where derived data are used, reproduce the calculation independently. Reconcile customer service reports with the same timestamps. This exercise can reveal boundary changes, estimated readings, excluded auxiliary loads or cooling events that annual averages conceal.
Evidence quality should affect valuation directly. A signed utility allocation with proven delivery supports a different value than an application or management statement. A commissioned performance test supports a different value than a vendor specification. An executed customer requirement supports a different value than a sales forecast. The diligence register should assign each material input an evidence grade and map that grade to a valuation treatment, financing condition or transaction protection.
Appendix C. Hypothetical worked case
The project is a 12 MW high-density AI module with 8.4 MW average information-technology load and a target rack density of 100 kW. Total project uses are INR 720 crore. Senior term debt provides INR 350 crore, equipment finance INR 180 crore, sponsor equity INR 150 crore and customer prepayments INR 40 crore.
At stabilization, annual revenue is INR 360 crore and operating cost is INR 198 crore, producing INR 162 crore of EBITDA. Annual debt service is INR 98 crore and debt-service coverage is 1.65 times. The combined downside assumes a nine-month delay, 20 per cent capex overrun, lower billable utilization, weaker pricing and higher power cost. EBITDA falls to INR 90 crore and coverage to 0.92 times before cure actions. All figures are wholly hypothetical.
Appendix D. Investment-committee questions
Which water source is legally and physically secured? Which cooling boundary does WUE measure? What happens during the hottest coincident computing load? Which customers have qualified the system? What electrical headroom remains after dry cooling? What retrofit shutdown is required?
Who funds capex and overruns? Which permits and consents survive closing? What benefits are contracted? Which claims rank ahead of equity? What is the no-retrofit value? Which post-closing metric triggers intervention?
Appendix E. Scenario governance
Preserve the approved valuation date and evidence set. Run load-ramp, hot-weather, water-curtailment, power-price, capex-overrun, retrofit-delay, customer-rejection and combined cases. Do not alter one driver without its physical counterpart.
Record actual performance monthly and explain variance. Reopen valuation when a utility right, customer requirement, cooling technology or environmental obligation changes materially.
Appendix F. Data dictionary
The computing record should include installed, commissioned, occupied and billed MW; rack density; energy; hardware class and customer. The cooling record should include topology, temperatures, flow, redundancy, WUE, PUE, power and availability. The water record should include source, withdrawal, consumption, discharge, quality, tariff and permit.
The capex record should include asset, owner, supplier, amount, completion, useful life and milestone. The contract record should include customer, utility, term, capacity, price, service level, assignment and termination. The valuation record should identify cash recipient, method, discount rate, term, claims and sensitivity.
Appendix G. Decision figures and tables
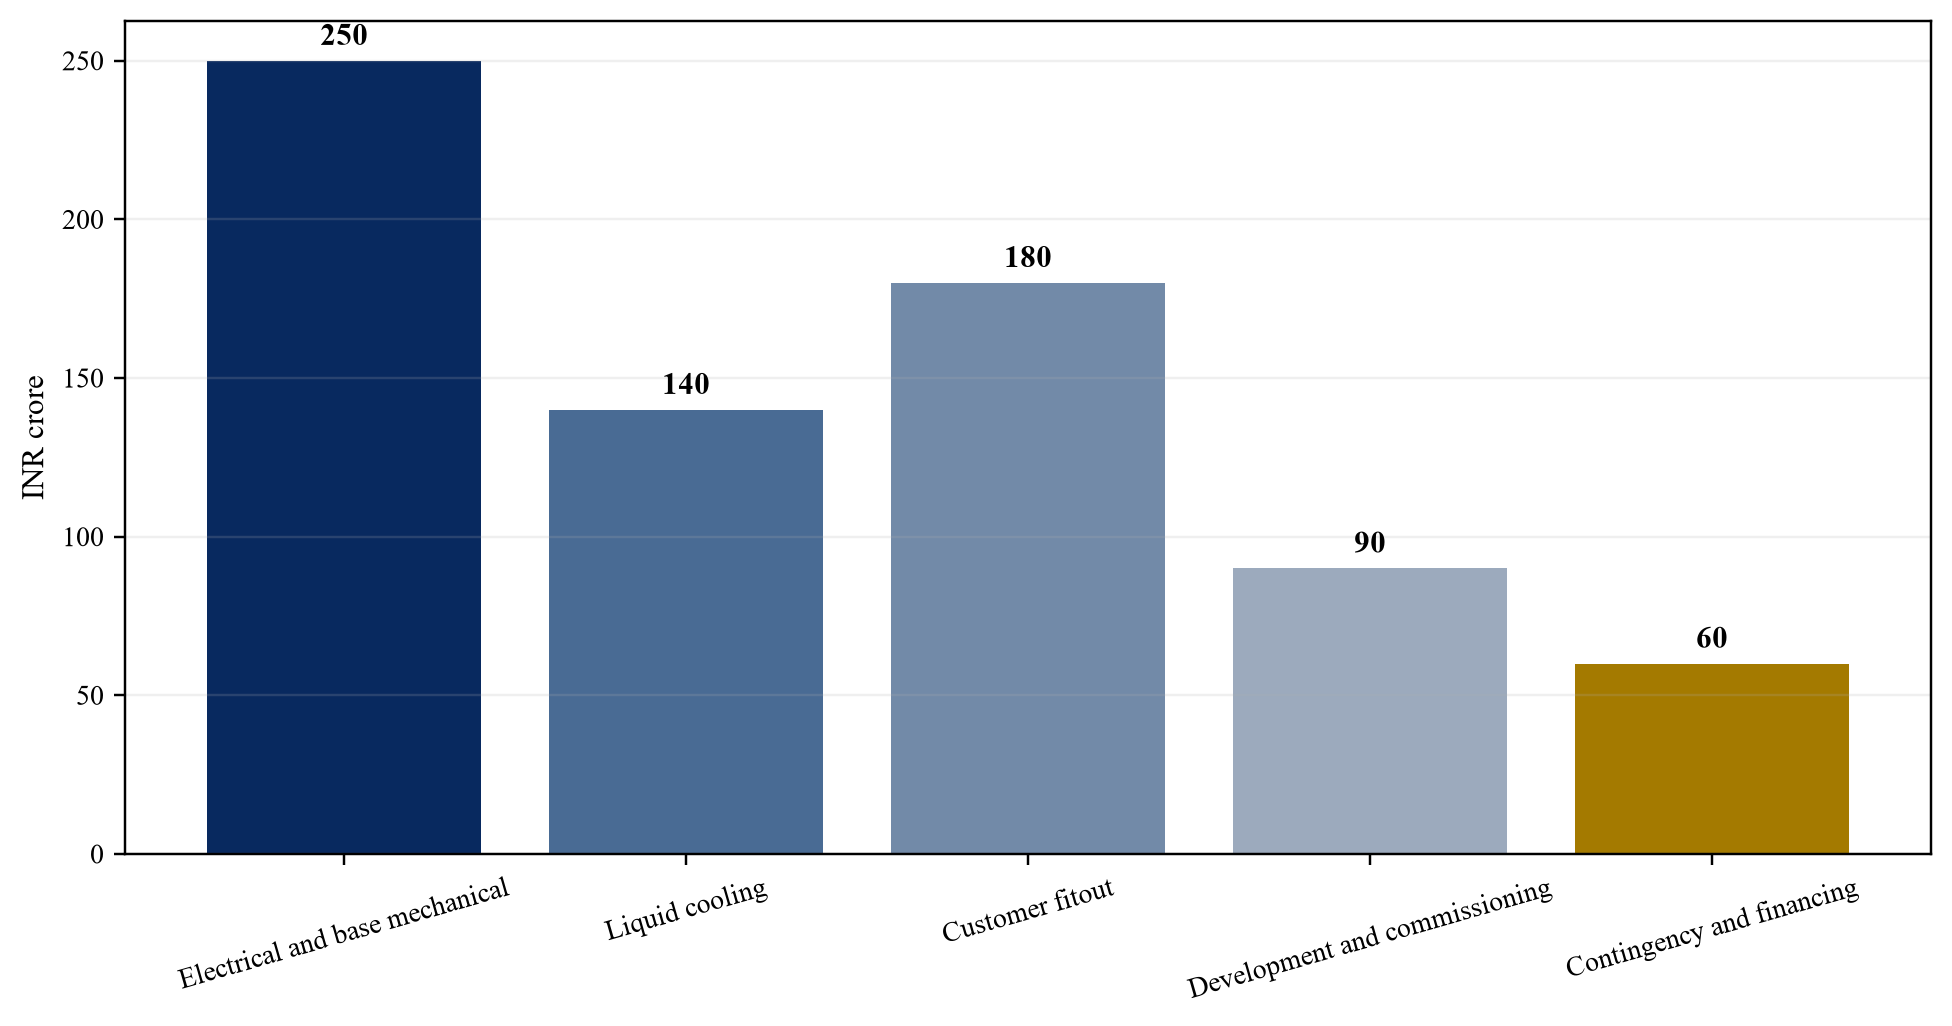
Wholly hypothetical; INR crore.
| Architecture | Principal asset | Financing issue | Minimum evidence |
|---|---|---|---|
| Conventional air | shared mechanical plant | density ceiling | tested capacity and customer load |
| Direct-to-chip | CDUs, loops and controls | interface and leak risk | integrated test and warranty |
| Immersion | tanks, fluids and handling | technology and residual value | equipment qualification and service plan |
| Hybrid | mixed air and liquid systems | boundary and operating complexity | mode map and measured performance |
Proposed framework unless stated otherwise.
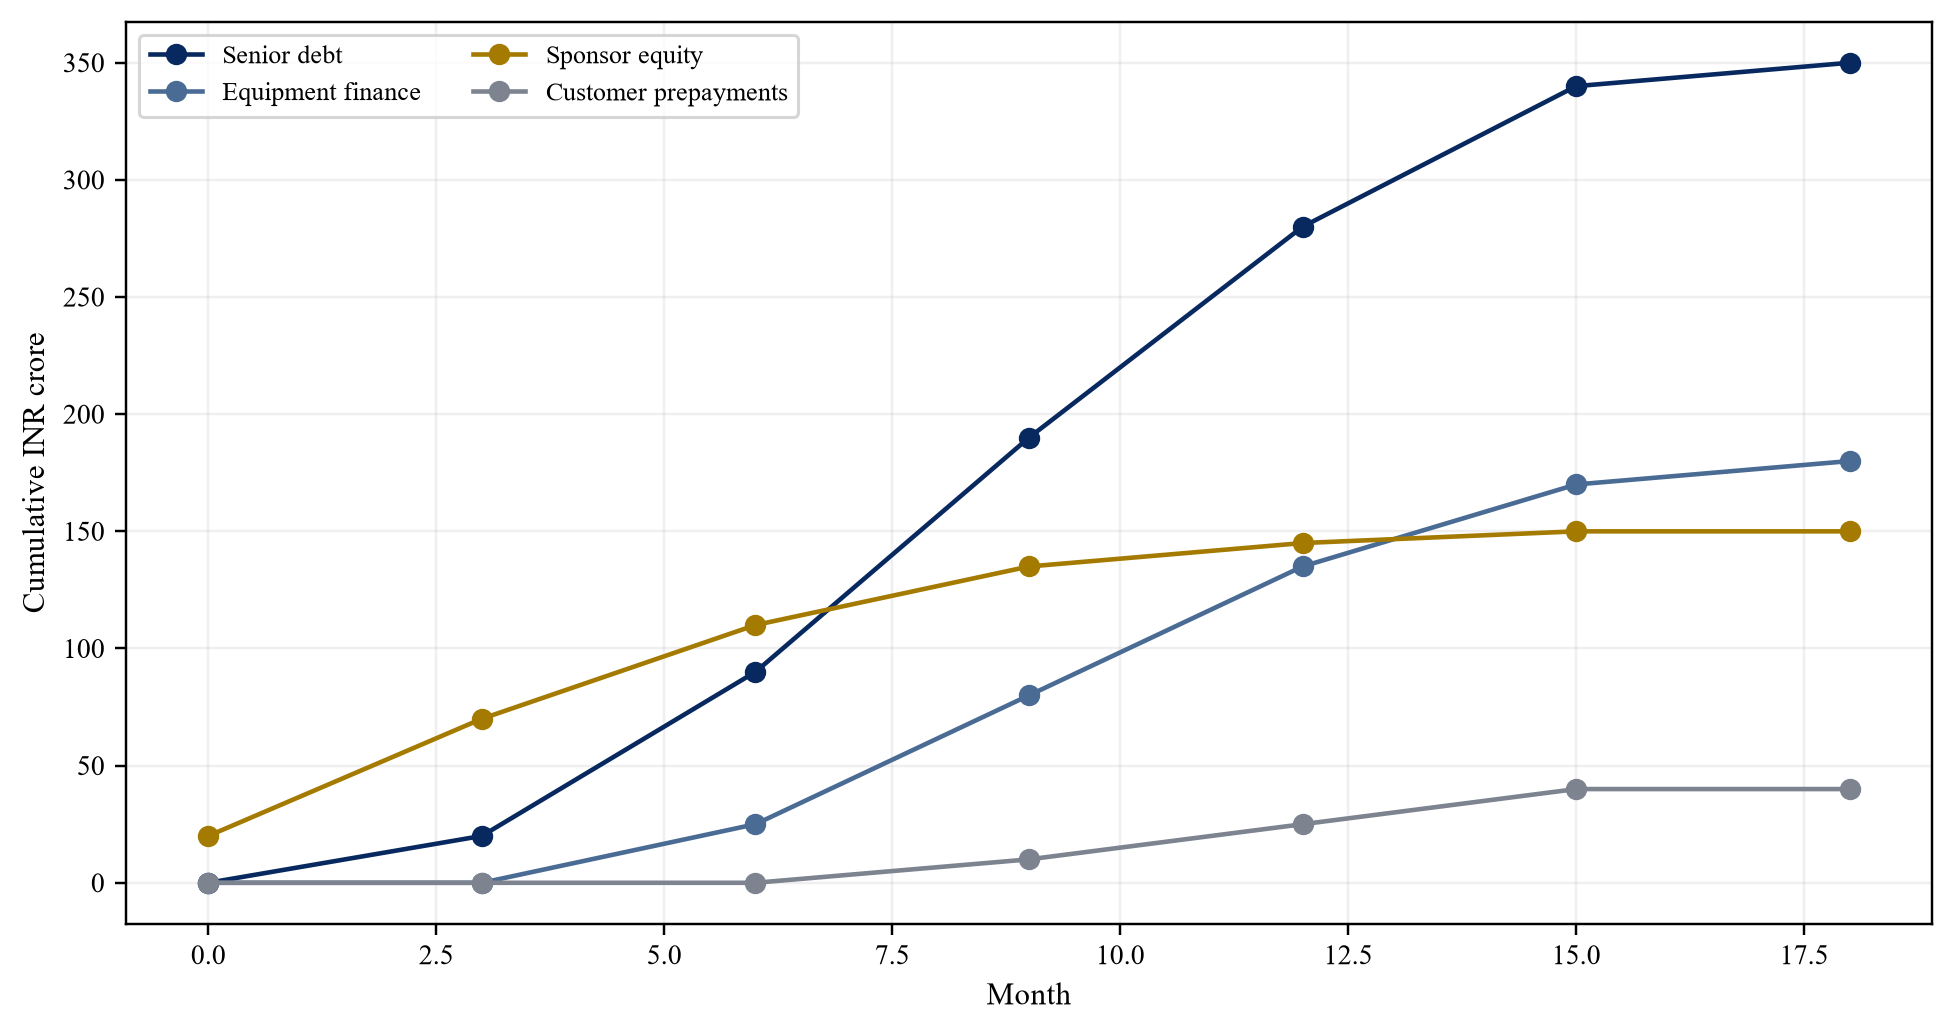
Wholly hypothetical; INR crore.
| Stage | Evidence | Indicative financing treatment |
|---|---|---|
| Design | approved thermal and electrical basis | sponsor funded |
| Procurement | fixed scope, price and guarantees | deposit facility or equity |
| Delivery | inspected, insured equipment on site | equipment draw |
| Installation | certified work and cost to complete | construction draw |
| Commissioning | integrated performance test | retained amount released |
| Acceptance | customer sign-off and billable service | term conversion |
Proposed framework unless stated otherwise.
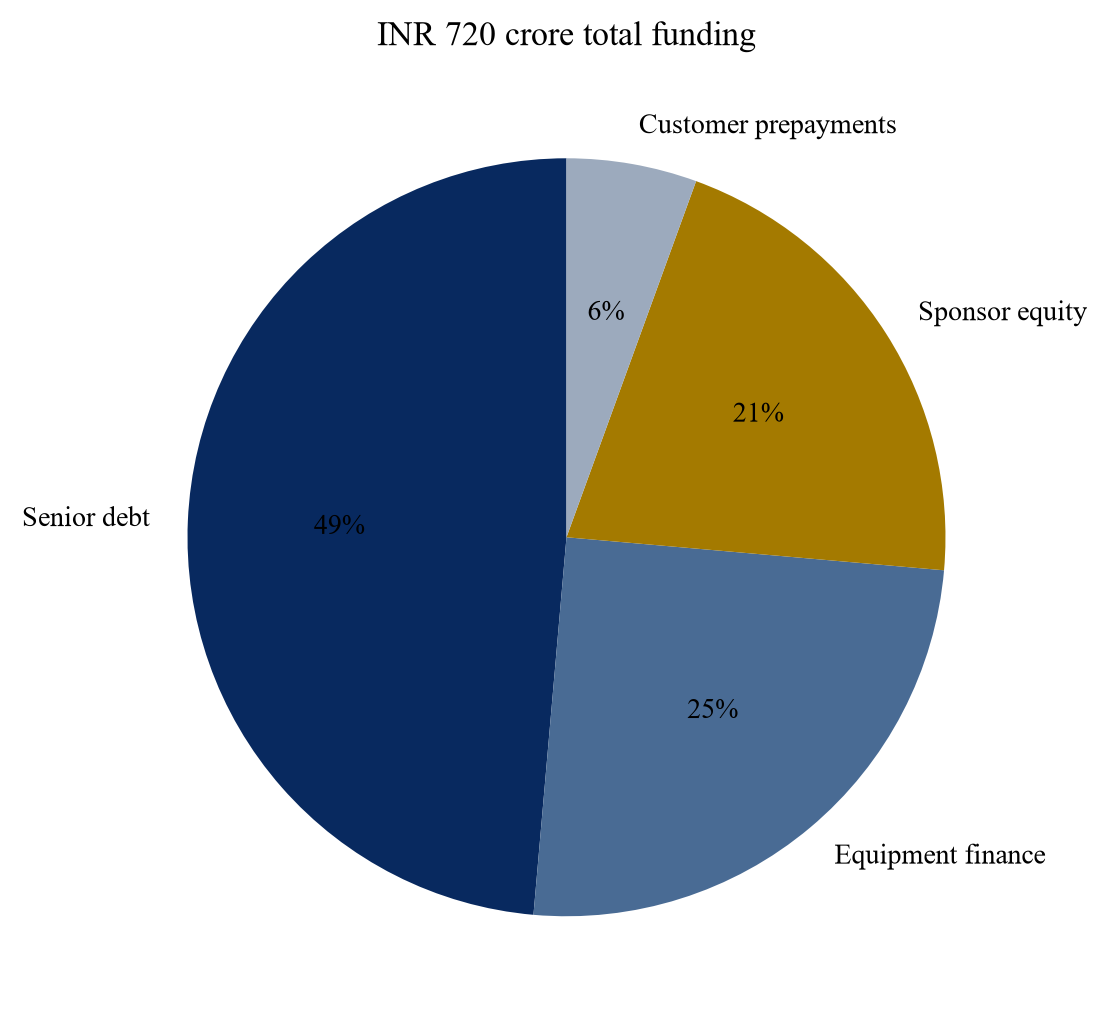
Wholly hypothetical; total INR 720 crore.
| Use | INR crore | Credit focus |
|---|---|---|
| Electrical and base mechanical | 250 | utility capacity and completion |
| Liquid cooling and heat rejection | 140 | performance and vendor support |
| Customer and rack fitout | 180 | customer acceptance and reuse |
| Development and commissioning | 90 | timing and cost-to-complete |
| Contingency and financing | 60 | overrun and liquidity protection |
Wholly hypothetical and not a financing offer.
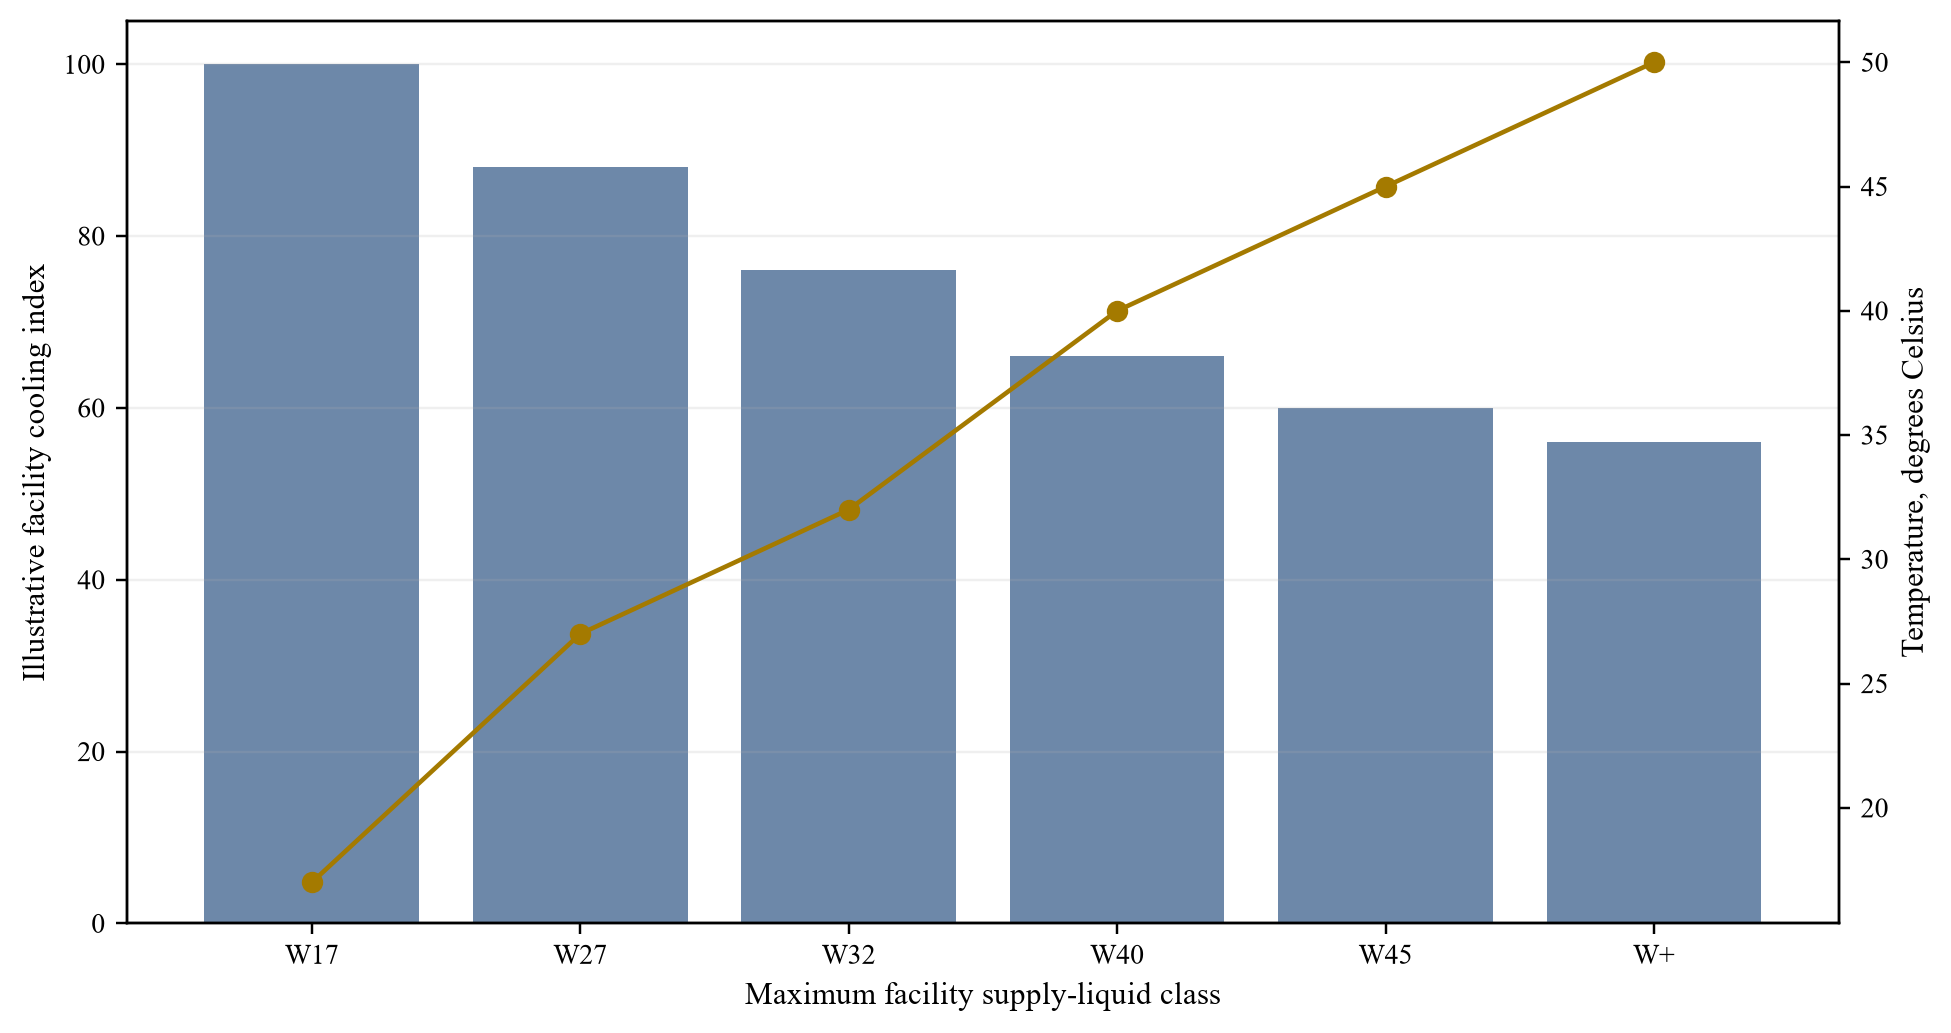
Conceptual representation using ASHRAE liquid-cooling classes.
| Sources | Amount | Uses | Amount |
|---|---|---|---|
| Senior term debt | 350 | Electrical and base mechanical | 250 |
| Equipment finance | 180 | Liquid cooling | 140 |
| Sponsor equity | 150 | Customer fitout | 180 |
| Customer prepayments | 40 | Development, contingency and financing | 150 |
| Total | 720 | Total | 720 |
INR crore; figures may not sum visually because each side is shown independently.
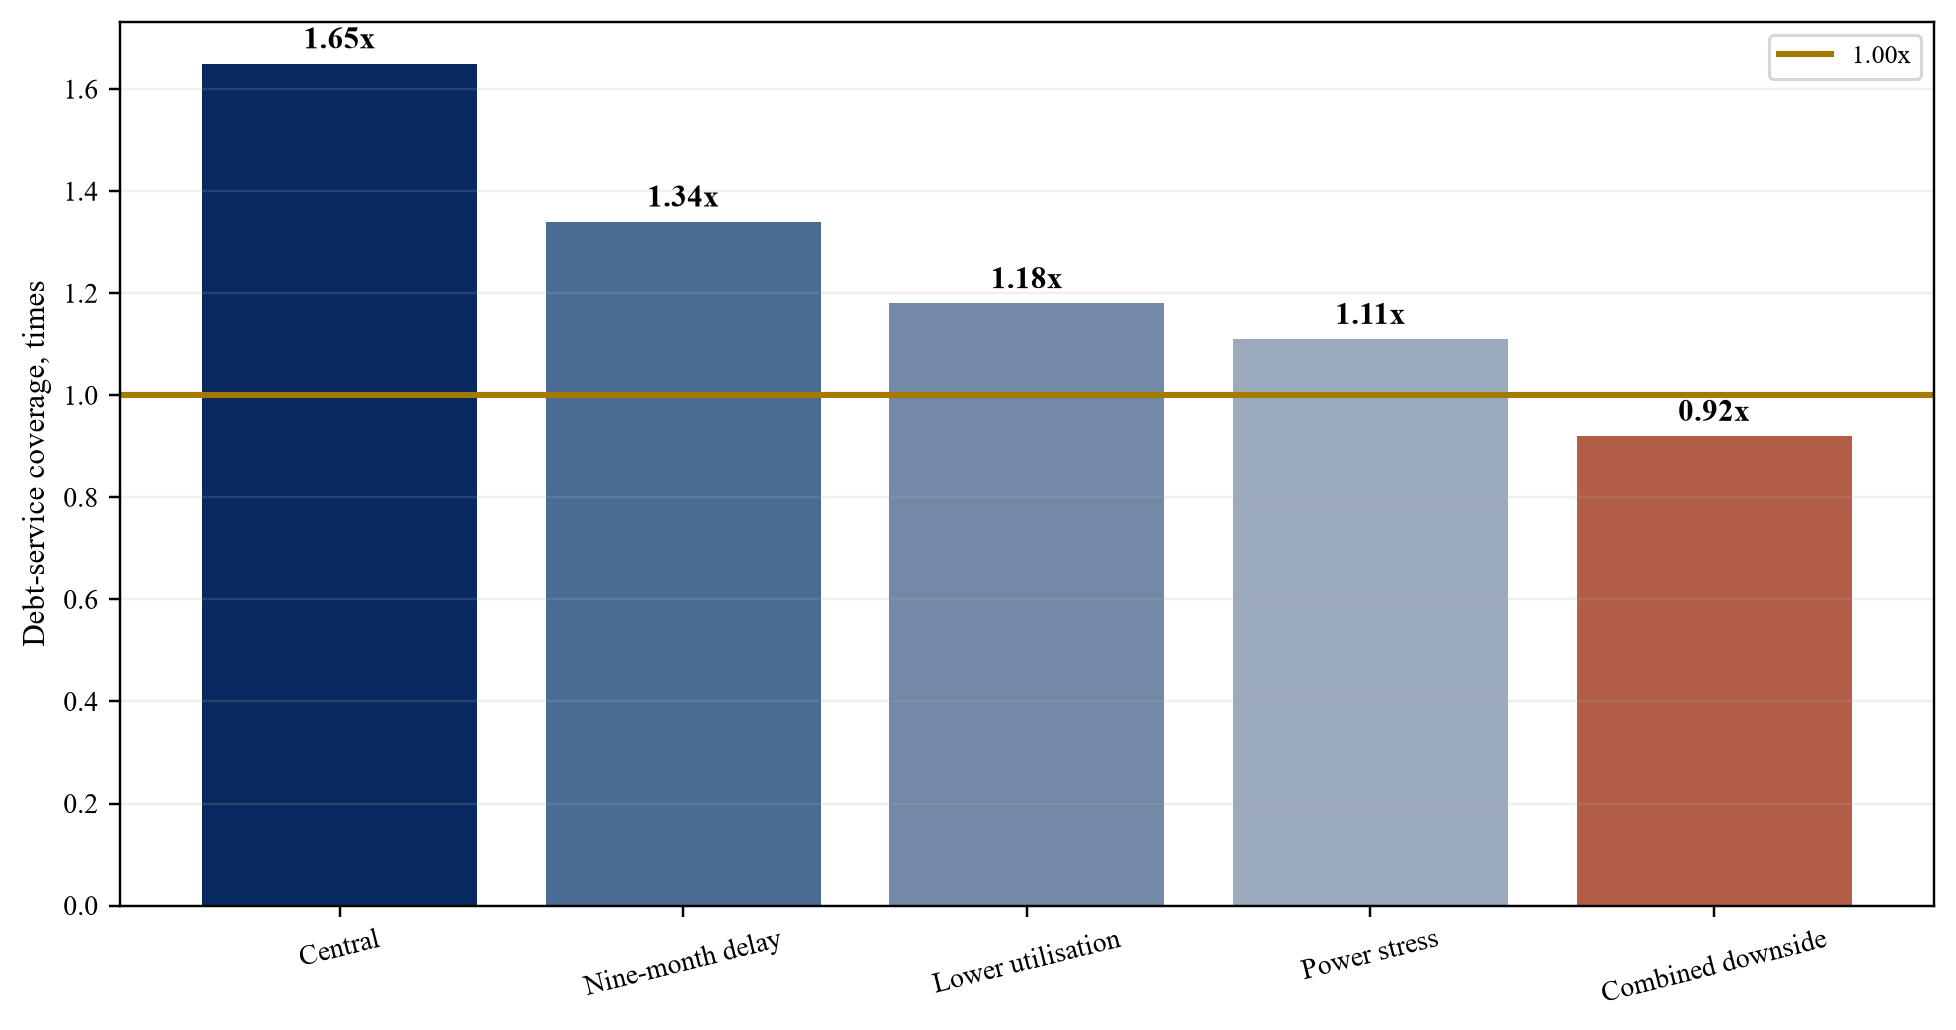
Wholly hypothetical.
| Item | Central | Combined downside |
|---|---|---|
| Average IT load | 8.4 MW | 6.7 MW |
| Annual revenue | INR 360 crore | INR 270 crore |
| EBITDA | INR 162 crore | INR 90 crore |
| Annual debt service | INR 98 crore | INR 98 crore |
| DSCR | 1.65x | 0.92x |
Wholly hypothetical and not a financing offer.
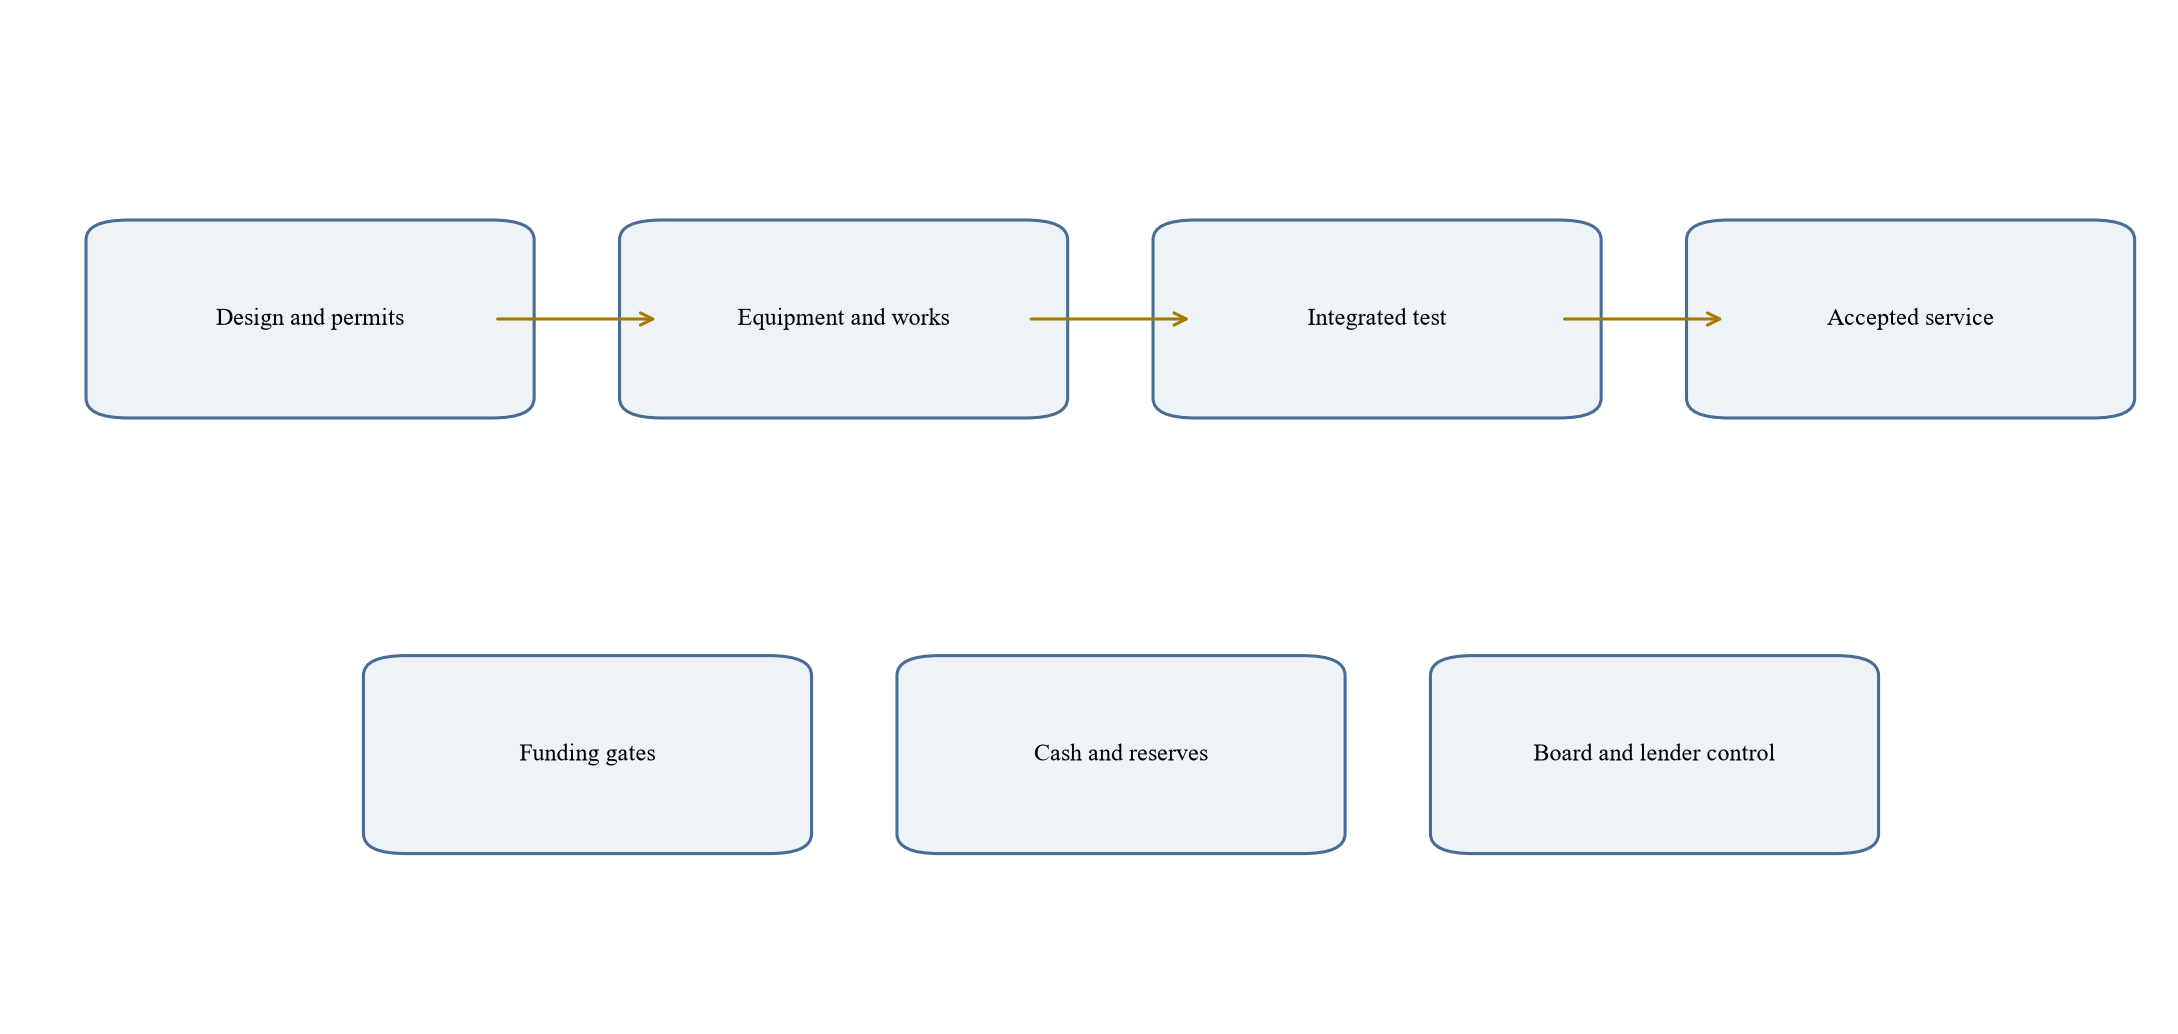
Proposed governance framework.
| Risk | Control | Evidence or trigger |
|---|---|---|
| Completion delay | completion support and longstop | independent engineer certificate |
| Cost overrun | equity-first cure and contingency | cost-to-complete test |
| Utilisation shortfall | distribution lock and cash sweep | billable load and collections |
| Power or water stress | operating reserve and remediation | utility notice or meter threshold |
| Vendor failure | spares, warranty and alternative supplier | service breach or insolvency |
Terms require transaction-specific negotiation and legal advice.
| Metric | Source | Trigger |
|---|---|---|
| Installed, accepted and billable MW | commissioning and customer records | conversion delay |
| Rack density and thermal headroom | rack and facility sensors | design variance |
| WUE, PUE and peak power | calibrated meters | resource or tariff breach |
| Capex, commitments and cost to complete | project ledger | overrun or funding gap |
| Revenue, collections and DSCR | billing, bank and model | covenant pressure |
| Reserves, hedges and insurance | controlled accounts and policies | expiry or insufficiency |
Proposed framework unless stated otherwise.
Sources
- Press Information Bureau, Data centre capacity increased from about 375 MW in 2020 to around 1,500 MW by 2025, 13 March 2026. Read the primary source
- Press Information Bureau, CEO Roundtable on Ease of Doing Business for Scaling India's Data Centre Ecosystem, 2 September 2026. Read the primary source
- Press Information Bureau, India to add 20,000 GPUs beyond existing 38,000, 17 February 2026. Read the primary source
- International Finance Corporation, IFC partners with Sify to support expansion of data centers through sustainability-linked finance, 18 June 2026. Read the primary source
- International Finance Corporation, Sify Data Center investment disclosure, project 51725. Read the primary source
- Press Information Bureau and NITI Aayog, Workshop for states on accelerating AI data-centre investments, 8 May 2025. Read the primary source
- ASHRAE, AI Data Center Energy Performance Framework: Introduction and Purpose. Read the primary source
- ASHRAE Handbook, Data Centers and Telecommunication Facilities, Chapter 20. Read the primary source
- Bureau of Energy Efficiency, Energy Efficiency Guidelines and Best Practices in Indian Datacenters. Read the primary source
- Bureau of Energy Efficiency, Reports and studies including Future-Proofing India's Cooling. Read the primary source
- Ministry of Environment, Forest and Climate Change, India Cooling Action Plan. Read the primary source
- Central Ground Water Authority, Guidelines to regulate and control groundwater extraction in India. Read the primary source
- Reserve Bank of India, Review of Regulatory Framework for Infrastructure Debt Fund-NBFCs, 18 August 2023. Read the primary source
- Securities and Exchange Board of India, Data relating to activities of Alternative Investment Funds. Read the primary source
- Reserve Bank of India, Master Direction on External Commercial Borrowings, Trade Credits and Structured Obligations. Read the primary source
- Central Electricity Authority, National Electricity Plan. Read the primary source
- Central Electricity Authority, Growth of Electricity Sector in India from 1947 to 2025. Read the primary source
- Press Information Bureau, India AI Impact Summit session on resilient high-performance data centres, 17 February 2026. Read the primary source
- Press Information Bureau, IndiaAI Mission expands AI ecosystem with affordable compute and startup support, 25 March 2026. Read the primary source
- Ministry of Electronics and Information Technology, IndiaAI Mission Report 2026. Read the primary source
- Press Information Bureau, Budget 2026-27 sets the stage for India as a global hub for cloud and AI infrastructure, 14 February 2026. Read the primary source
- Press Information Bureau, Google AI Hub in Visakhapatnam, 14 October 2025. Read the primary source
- Ministry of Power, Green Energy Open Access Rules, 2022. Read the primary source
- Indian Green Building Council, IGBC Data Center Rating System. Read the primary source
- IFRS Foundation, IFRS 9 Financial Instruments. Read the primary source
- IFRS Foundation, IFRS 13 Fair Value Measurement. Read the primary source
- IFRS Foundation, IAS 36 Impairment of Assets. Read the primary source
- IFRS Foundation, IFRS S2 Climate-related Disclosures. Read the primary source
- Ministry of Electronics and Information Technology, Digital Personal Data Protection Act 2023. Read the primary source
- Open Compute Project Foundation, Advanced Cooling Solutions project. Read the primary source
