
Introduction
Microgravity can change fluid behaviour, crystal formation, sedimentation, convection and tissue growth. These effects support credible research pathways in pharmaceuticals, advanced materials, semiconductors, optical fibre and biomanufacturing. They do not by themselves establish a commercial manufacturing business. Investors must connect the physical effect to a saleable specification, a reliable return path and a customer decision that produces cash.
The financing problem is acute because capital is committed before production history exists. Payload hardware, flight qualification, launch integration and return systems require funding while product yield remains uncertain. A delayed launch can defer the entire learning cycle. A successful orbital run can still fail during re-entry, recovery, testing or customer qualification. Each stage creates a distinct probability of technical success and a distinct probability of commercial conversion.
This paper provides a decision framework for boards, founders, strategic customers, public agencies and investors. It uses current public programmes as evidence of technical direction and market-building activity. It treats the financial case as programme-specific. Every commercial number in the worked case is hypothetical and requires replacement with controlled company evidence.
1 Define the product and the customer decision
The first valuation task is to identify the exact output sold to a customer. The output may be a returned physical product, a seed crystal, a process recipe, characterisation data, intellectual property, a manufacturing service or a combination of these items. Each has different revenue recognition, quality control, logistics and capital requirements. A broad claim that microgravity improves materials provides insufficient scope for valuation.
The customer decision should be stated in operational terms. A pharmaceutical customer may pay when returned crystals improve formulation, stability or delivery. A semiconductor customer may pay for seed material that improves downstream device performance. An optical-fibre customer may pay for verified attenuation, strength and consistency. The economic case depends on the value of that measured improvement relative to terrestrial alternatives, qualification time and switching cost.
The diligence file should name the buyer, decision owner, test protocol, acceptance threshold, expected purchase form and alternative solution. It should also show who owns the returned material, process data and improvements. This product boundary controls the revenue model and prevents platform capability from being mistaken for customer demand.
2 Build the evidence chain
Valuation should follow the chain from physical mechanism to repeat purchase. The terrestrial benchmark establishes current quality, cost and cycle time. Laboratory or parabolic-flight work may demonstrate a microgravity effect. Orbital experiments test whether the effect survives real hardware, mission constraints and process variability. Recovery and qualification establish whether the returned output retains the required properties. Customer acceptance establishes commercial relevance.
These stages should remain separate in the model. A company can complete an orbital experiment without producing a recoverable batch. A recovered batch can fail specification. A technically conforming batch can still lack a customer willing to pay a premium. A first paid batch can remain non-repeatable because launch windows, payload configuration or regulatory approvals change. Each transition therefore needs a dated evidence record and an explicit probability.
The board should require a milestone register that links evidence, cash release and valuation treatment. Scientific evidence supports technical probability. Signed contracts support commercial probability only to the extent that pricing, acceptance, termination and refund terms are enforceable. Cash received before performance must be classified according to its legal terms rather than treated automatically as earned revenue.
3 Measure yield through the entire mission
Gross payload mass is a poor proxy for saleable output. The yield model should begin with feedstock loaded, then deduct commissioning loss, process loss, off-spec production, storage loss, re-entry loss, recovery loss, testing samples, terrestrial finishing loss and customer rejection. The final measure is accepted output available for invoicing or downstream use.
Each loss factor should be linked to measurement. A process can show high on-orbit conversion while producing little customer-accepted material if the batch is damaged during return or requires destructive testing. Small development missions may also allocate a large share of output to validation. Scale assumptions should explain which losses decline with repetition and which remain physical or regulatory requirements.
Investors should monitor first-pass yield, recovered yield and customer-accepted yield separately. First-pass yield measures process control. Recovered yield measures the full space-to-Earth chain. Customer-accepted yield connects technical performance to revenue. The valuation model should use the narrowest measure consistent with the revenue forecast.
4 Separate mass economics from value density
In-space manufacturing may favour products with high value per kilogram because launch and return impose substantial fixed and mass-dependent costs. Value density alone remains incomplete. The product must also tolerate mission duration, packaging, radiation, vibration, temperature change, re-entry and recovery. A high-value material with a long qualification cycle may tie up capital and delay customer cash.
The model should calculate revenue per kilogram of accepted output, contribution per mission and contribution per calendar month. These views expose different constraints. Revenue per kilogram can appear attractive while mission contribution remains negative because payload mass is small. Contribution per mission can appear positive while annual economics remain weak because launch and return cadence is low.
Boards should compare the orbital route with terrestrial process improvement, contract manufacturing and alternative research methods. The relevant willingness to pay is the customer's incremental economic benefit after qualification and adoption costs. Market prices for finished products should not be applied to an intermediate orbital output unless the company controls the remaining value chain.
5 Price launch integration and schedule risk
Launch cost includes more than the quoted ride to orbit. Payload developers incur safety review, interface engineering, qualification testing, documentation, transport, insurance, schedule management and contingency. Shared launches can reduce direct price while limiting orbit, timing and change control. A launch delay can increase working capital and push customer qualification into another budget cycle.
The financial model should separate committed launch payments, refundable deposits, integration costs and delay costs. It should show whether a payload can move to another provider without redesign. A dedicated mission may offer control at higher cost. A hosted payload may provide access to power, crew and laboratory infrastructure while creating platform dependency and constrained production time.
Scenario analysis should include on-time launch, moderate delay, missed window and mission loss. The company should fund operations through the next available window rather than assume an immediate reflight. Customer contracts should address schedule changes, substitute missions and acceptance timing.
6 Treat return as a production stage
Return capability is part of manufacturing because the customer cannot use a terrestrial product that remains in orbit. The return chain includes de-orbit authority, thermal protection, navigation, landing location, recovery, chain of custody, transport and environmental control. Each step can affect quality and timing. A platform that produces successfully in orbit but cannot return reliably has incomplete unit economics.
United States commercial re-entry requires FAA authorisation, and the licensing process covers concept of operations, safety, environmental review and compliance. The UK is funding reusable heat-shield development to support return of manufactured materials. ESA's Space Rider is designed as a reusable uncrewed system for access to and return from low Earth orbit. These programmes broaden potential return pathways while preserving operator-specific licensing and performance risk. [5][6][7][9]
The model should allocate return cost per mission and per accepted kilogram. It should also include the cash consequence of a delayed licence or unavailable landing window. Insurance, customer remedies and replacement rights should reflect which party controls each return step.
7 Validate product quality after recovery
Quality evidence should be defined before flight. The protocol should identify the terrestrial control, sample size, analytical method, acceptance range, laboratory, chain of custody and statistical treatment. Post hoc selection of favourable measures can overstate the commercial effect. Independent testing may be required where customers, regulators or capital providers cannot rely solely on company data.
NASA's optical-fibre reporting illustrates this distinction. Commercial lengths were produced on the ISS, and analysis after return was still needed to determine whether the programme's quality objective had been achieved. Production length and production quality were separate milestones. [3]
The valuation model should therefore assign value to evidence that reduces uncertainty, even before commercial revenue. A repeatable, independently verified quality advantage can raise the probability of customer adoption. The increase should be linked to the affected cash flows and probabilities rather than added as an arbitrary technology premium.
8 Model pharmaceutical pathways
Pharmaceutical use cases include protein crystallisation, formulation development, drug-delivery devices, tissue models and biomanufacturing. The commercial output may support research, improve a formulation or become part of a regulated product. These pathways have different timelines and evidentiary requirements. A successful crystal-growth mission does not automatically create an approved medicine.
NASA's InSPA portfolio supports protein crystals, tissue engineering and medical devices. Redwire reported launching PIL-BOX payloads for pharmaceutical partners. Varda identifies pharmaceutical processing as a mission type. These activities establish real programme participation and growing operational experience. Public sources do not disclose enough programme-level economics to infer customer pricing or margin for another company. [1][10][11][12]
The valuation should map where the orbital output enters the customer's development chain. It should estimate the probability that the output changes formulation, delivery, efficacy, manufacturing or time to market. Customer willingness to pay should be based on the expected value of that change and the contractual rights received.
9 Model semiconductor and advanced material pathways
Microgravity may support crystal growth and material formation with reduced convection, sedimentation or defect formation. Commercial value depends on whether the returned material improves device yield, power efficiency, reliability or another customer metric after terrestrial processing. The economic unit may be a seed crystal or process insight rather than a finished wafer.
UK public programmes describe semiconductor work involving silicon carbide, gallium nitride and gallium oxide and a hybrid model in which orbital seed material returns to terrestrial facilities for scale-up. They also funded feasibility work to define commercial routes for semiconductor seed crystals. These programmes provide useful evidence for the value-chain design. [13][14][15]
The financial model should include downstream finishing, characterisation and customer qualification. It should avoid pricing orbital intermediate material at the value of the finished device. Strategic value may arise from protected process knowledge, supply-chain resilience or sovereign capability, although each benefit requires a named customer and an enforceable funding mechanism.
10 Model optical fibre pathways
Optical-fibre use cases depend on producing material with lower attenuation, improved transmission or other verified performance advantages. NASA reported more than 11 kilometres of fibre drawn during a 2024 investigation and noted that returned analysis was required to assess the quality target. This evidence supports process scale and repetition while keeping product qualification separate. [3]
The model should connect accepted fibre length and quality to customer applications. It should deduct unusable starts, breaks, testing samples, splicing requirements and finishing loss. A headline length can overstate revenue if only part of the material meets specification. Customers may also require long-term reliability data before adopting the product in medical, defence or telecommunications systems.
An investment case should compare orbital production with improvements in terrestrial furnaces, drop towers and material chemistry. The relevant premium is the net benefit of the returned fibre after integration into the customer's system.
11 Evaluate biological manufacturing
Biological systems can behave differently in microgravity, supporting three-dimensional tissue growth, disease modelling and production of medical devices. Biological payloads add constraints involving viability, contamination, temperature, timing and sample handling. Return delay may destroy value even when the orbital process succeeds.
The quality plan should specify viable yield, sterility, structural integrity, functional performance and the maximum time from process completion to controlled recovery. The operating model should allocate responsibility for cold chain, biosafety, customs and laboratory transfer. Where regulatory submissions are expected, data integrity and validated methods should be designed into the mission.
Valuation should use programme-specific development milestones. Early evidence may justify option value or strategic funding. Revenue forecasts require a defined product pathway, a customer acceptance protocol and rights to use the resulting data.
12 Distinguish technology readiness from manufacturing readiness
Technology readiness measures whether a process or system works in a relevant environment. Manufacturing readiness addresses repeatability, quality systems, supply chain, throughput, workforce and cost. A flight demonstration can advance technology readiness while leaving manufacturing readiness low. This gap is material because commercial value depends on repeat production.
The diligence process should score payload hardware, process control, feedstock, return system, terrestrial finishing and quality systems separately. A single blended readiness label can conceal the weakest link. Manufacturing evidence should include batch records, configuration control, calibration, deviation handling and corrective action.
Capital should fund the next weak link rather than expand every component simultaneously. A company with proven process physics and unproven return may prioritise repeatable recovery. A company with reliable return and low accepted yield may prioritise process control and customer specification.
13 Build customer willingness to pay from incremental value
Customer willingness to pay should be derived from the economic benefit of the accepted output. That benefit may include higher product performance, lower downstream cost, faster development, improved reliability, new intellectual property or access to a product that cannot be made terrestrially. The analysis should identify who captures each benefit and when it becomes measurable.
The customer model should distinguish paid research, development funding, reservation payments, minimum purchase commitments and volume purchases. A research contract may validate engagement without proving recurring product demand. A reservation may improve scheduling confidence while remaining refundable. A minimum purchase agreement may support financing only after acceptance conditions and termination rights are understood.
The strongest evidence is a repeat order after the customer has tested returned output. Before that point, valuation should use probability-weighted cash flows tied to contractual and technical milestones.
14 Construct the commercial pipeline waterfall
Pipeline reporting should narrow from identified accounts to qualified use cases, paid studies, flight reservations, contracted batches, accepted output and repeat orders. Each stage should have a defined evidence threshold. Aggregate letters of interest should not be combined with binding purchase commitments.
The funnel should track customer concentration and use-case concentration. Several contracts with one pharmaceutical company may leave a large counterparty exposure. Several customers dependent on the same unproven return system may create correlated operational risk. Timing matters because customers can withdraw if qualification takes longer than their development programme.
The board should review pipeline value at the same cut-off date as technical readiness and mission schedule. A commercial forecast built on old customer interest and a current technical plan can create false precision.
15 Design contracts around evidence and control
Contracts should specify payload configuration, launch window, process objective, return obligation, testing protocol, acceptance, data rights, intellectual property, refunds, liability and remedies. The allocation should follow control. The platform operator may control flight hardware and return, while the customer controls feedstock and downstream testing.
Milestone payments can fund development when they correspond to measurable completion. Availability payments may support reserved capacity. Product payments should depend on agreed acceptance. Termination rights, reflight obligations and refundability determine whether contracted amounts support debt or remain contingent liabilities.
The financing model should reproduce the contract waterfall. Cash receipts, revenue recognition and debt service may occur at different times. A customer prepayment can strengthen liquidity while increasing performance obligations.
16 Calculate mission contribution and cash conversion
Mission contribution should begin with cash revenue attributable to the flight. It should deduct payload hardware, launch, integration, platform service, return, recovery, testing, finishing, insurance, royalties, warranty and expected reflight cost. Shared corporate expense and continuing research should remain visible below mission contribution.
Working capital can be significant. Suppliers and launch providers may be paid before customers accept output. Testing and qualification can extend the cash cycle after recovery. A mission with positive accounting margin can consume cash for a long period. The model should show peak cash need and funding headroom under delay.
Investors should compare contribution per mission, per accepted kilogram and per calendar month. These metrics reveal whether value depends on yield, price or cadence.
The contribution bridge should distinguish committed cost from avoidable cost. A launch deposit may be non-refundable once a window is reserved, while testing, finishing or recovery expenditure may depend on successful return. This distinction matters when management decides whether to continue after an adverse result. The model should calculate the incremental cash needed to complete a mission, the expected cash recovered from completion and the value of the evidence produced. A decision to proceed can remain rational when the individual flight has negative contribution if the controlled experiment materially changes the probability or design of a valuable later programme. That research value should be stated separately from operating profit.
Cash conversion also depends on claim and remedy terms. The programme should identify which costs are recoverable after launch delay, mission loss, late return, damaged material or failed acceptance. Insurance proceeds, supplier credits, customer refunds and reflight rights may arrive at different times and may remain disputed. The liquidity case should fund the period before recovery rather than net expected remedies immediately against the loss. This treatment makes the cash model more conservative and gives the board a practical view of the capital required to preserve the next milestone.
17 Model production cadence
Annual value depends on the number of completed cycles, not the number of announced payload opportunities. Cadence includes payload preparation, launch integration, orbit time, return scheduling, recovery, testing, refurbishment and the next mission. A bottleneck at any stage limits throughput.
The operating plan should identify parallel capacity. Multiple payloads may share a launch while competing for integration resources. Reusable return vehicles may reduce unit cost only after recovery and refurbishment are proven. Commercial stations may broaden access, though programme timelines and service terms remain platform-specific. [16][17][18]
The valuation should cap revenue at verified system capacity and apply utilisation assumptions separately. Expansion capital should follow evidence that demand and operational cadence support added capacity.
Cadence should be managed through a constraint register. Each mission should have a critical resource, maximum queue, expected service time and recovery plan. Examples include payload engineers, clean-room capacity, launch integration slots, licensed return windows, recovery teams and customer laboratories. Management can then separate demand backlog from executable production backlog. A customer order that cannot enter a qualified mission within its required delivery window contributes limited near-term value. Conversely, a reserved launch or return slot without a qualified customer creates cost exposure rather than assured revenue.
The board should monitor schedule variance by stage and by cause. A programme delayed by external launch availability has different remediation options from one delayed by unstable process hardware or incomplete customer testing. Repetition should shorten cycle time only where the underlying task becomes standardised. The forecast should preserve fixed regulatory, quality and recovery steps unless the company has evidence that those steps can run in parallel or be shortened. This approach converts cadence from an aspirational mission count into an operating-capacity model that can be reconciled to contracts and cash.
18 Apply milestone valuation
An early company can be valued using probability-weighted cash flow, comparable transactions, replacement cost and option analysis. Each method requires adjustment. Forecast cash flow needs explicit probabilities for technical, return, qualification and customer events. Comparables may combine spacecraft, research services and product businesses with different economics. Replacement cost does not establish customer value.
A milestone method can reduce false precision. The valuation starts with the current evidence state and models the value change if the company reaches the next state. The increase should reflect revised cash-flow probability, time and capital requirement. It should not be a predetermined markup assigned merely because a flight occurred.
The board should record the milestone, evidence required, independent reviewer, cost to reach it and financing implication. This creates a basis for staged equity, strategic investment and public co-funding.
Milestone valuation should also account for evidence decay. A technical result may lose relevance if hardware, process chemistry, launch environment or customer specification changes before the next mission. A customer indication may weaken when budgets, competing products or qualification requirements change. The model should therefore assign each evidence item an effective date, configuration boundary and refresh requirement. Reuse of prior evidence should be justified by documented similarity. This discipline limits the risk that old results are carried forward into a new configuration with materially different performance.
Financing negotiations can use the same milestone register. Investors may release capital in tranches, customers may make development payments, and public agencies may reimburse eligible costs after delivery. The company should model timing and conditions for each source. A headline commitment that depends on matching funds, accepted milestones or future appropriations is not equal to unrestricted cash. The valuation committee should compare the value created by the next milestone with dilution, control rights, liquidation preference, repayment obligations and the cost of delay if financing is not completed.
19 Structure the capital stack
Early technical and regulatory risk usually requires equity, strategic customer funding or public support. Customer development payments can align demand and reduce dilution when obligations are manageable. Equipment finance or structured debt may become viable when assets have alternative use, contracts provide dependable cash and downside reserves are funded.
Senior debt should not rely on uncontracted future product value. Lenders need enforceable cash flows, clear security, insurance and a funded path through delay. Convertible instruments may bridge milestones but can create valuation and governance complexity if several rounds stack before commercial proof.
The financing plan should fund the company through the next value-changing milestone plus a credible delay. Capital calls should reflect launch deposits and long-lead hardware rather than smooth monthly assumptions.
The capital structure should preserve decision flexibility. A mission-specific vehicle can isolate a defined payload, customer contract and return path, provided that intellectual-property rights, shared services and contingent liabilities are allocated clearly. A corporate facility can finance several programmes and diversify single-mission risk, though cross-default and security provisions may transmit a failure across the portfolio. Strategic capital can bring customer access, manufacturing capability or launch capacity; its information, exclusivity and governance rights require explicit valuation because they can affect other commercial relationships.
The downside case should identify a stop point before each material commitment. Management should show cash remaining after a failed test, delayed launch, lost mission, unsuccessful return and customer rejection. It should also identify the assets, data, licences and contractual rights preserved in each case. This recovery analysis supports staged commitments and prevents the full programme budget from being treated as unavoidable on day one. A financing plan is decision-ready when the board can see how much capital is at risk, what evidence that capital is expected to buy and which route remains available after an adverse outcome.
20 Protect process data and intellectual property
In-space manufacturing can create several kinds of intellectual property. Payload hardware may be patented or retained as trade secret. Process parameters, telemetry and failure data can improve later batches. Returned material may support new composition, formulation or device claims. Customer contracts may also create background and foreground intellectual-property rights. Valuation depends on which party owns and can exploit each layer.
The diligence team should map rights from feedstock through orbital processing and terrestrial finishing. Government and university funding terms may include licences, reporting duties or march-in provisions. Platform agreements may grant providers rights to operational data. Customer agreements may restrict disclosure, reverse engineering or use outside a named programme. A company that lacks the right to reuse learning can lose much of the value attributed to repetition.
The commercial model should distinguish product margin from licensing, data and platform revenue. Intellectual-property value should connect to an identifiable right, an enforceable territory and a plausible route to cash. The same future income should not appear both in the base cash flow and in a separate intellectual-property premium. Cybersecurity, export controls and access governance should protect sensitive process data throughout the mission chain.
21 Address regulatory and quality systems early
The applicable regulatory pathway depends on the product and jurisdiction. Spaceflight authorisation governs launch and return. Pharmaceutical, medical-device, semiconductor and aerospace customers may impose additional quality, validation and traceability requirements. These obligations can shape payload design, sampling and data collection long before commercial production begins.
Management should prepare a regulatory matrix covering the vehicle, landing site, payload, biological or hazardous material, import and export, customer quality standard and downstream product. Each requirement should have an owner, lead time and evidence deliverable. A programme can finish its technical development and still wait for permission or customer-quality approval if these workstreams begin too late.
The valuation should include the time and cash required for compliant repeat production. A quality system can create value by reducing batch failure and qualification friction. It also creates fixed cost and may limit rapid configuration changes. The model should therefore show the customer segments that need regulated production and the price or volume required to recover those costs.
22 Test platform scale before assigning platform value
A manufacturing company may own both the product process and the orbital platform. These businesses should be modelled separately. The product case asks whether accepted output earns sufficient margin. The platform case asks whether several products can share launch, power, volume, crew support, return and ground operations without creating scheduling or contamination conflicts.
Shared infrastructure can reduce unit cost when utilisation rises and missions remain operationally compatible. It can also add coordination cost, change-control risk and customer concentration. One large customer may fill capacity while demanding exclusivity. Several small customers may diversify revenue while increasing integration work. Platform value therefore depends on observed utilisation, standardised interfaces, turnaround and contract quality.
Investors should calculate stand-alone economics for each priority product and consolidated economics for the platform. Intercompany assumptions should use explicit transfer prices. A platform premium becomes defensible when multiple customers use common assets, incremental payloads improve contribution and the operating record shows that shared capacity does not reduce accepted yield or schedule reliability.
23 Make the investment decision
Approval requires a defined product, a measured orbital advantage, an end-to-end return plan, a customer acceptance protocol and funding through the next milestone. The investment committee should identify the variables that dominate value and the evidence that can change them within the proposed capital period.
The decision can be approve, stage, resize, partner, redesign or decline. A staged approval can release capital against payload completion, launch, successful process, recovery, accepted quality and repeat order. A partnership may be preferable where a specialist controls return, finishing or customer qualification.
The final record should preserve downside actions. Management should know which programme can be paused, which assets retain value, what customer obligations survive and how data and intellectual property are protected if the next milestone fails.
Conclusion
In-space manufacturing combines credible physical effects with a demanding commercial chain. The investable unit is the accepted output and associated rights after launch, processing, return, recovery, qualification and customer testing. Gross payload mass and successful experiments provide useful technical evidence while remaining several steps away from repeat revenue.
The framework developed here links valuation to six evidence states. It uses yield, return economics, quality, willingness to pay, pipeline conversion, mission contribution and cadence to test the business case. It also separates product economics from platform economics and technology readiness from manufacturing readiness.
The hypothetical case shows why this discipline matters. A five-mission programme can produce technical progress and USD 82 million of illustrative revenue while generating only USD 11 million of programme contribution before central overhead and financing. Small changes in accepted yield, price or completed missions can alter value materially. Investors should therefore release capital against evidence that reduces one of these uncertainties.
Public programmes show meaningful momentum in microgravity manufacturing, commercial return and reusable access. Programme-specific value still depends on the customer, product, contract and operating chain. A defensible valuation states what has been observed, what remains a scenario and which milestone can convert uncertainty into evidence.
Appendix A Hypothetical worked case
The hypothetical programme covers five missions. Total uses are USD 96 million: USD 18 million for payload and process development, USD 24 million for launch and integration, USD 19 million for orbital platform services, USD 14 million for return and recovery, USD 8 million for testing and terrestrial finishing, USD 5 million for insurance and regulatory work, and USD 8 million for programme reserves and corporate support. Funding comprises USD 34 million of sponsor equity, USD 22 million of customer development payments, USD 20 million of strategic capital, USD 14 million of public milestone funding and USD 6 million of equipment or structured finance.
The yield waterfall begins with 120 kilograms of gross processed material. Sixty-four kilograms are recovered, 38 kilograms pass the technical specification and 24 kilograms are accepted by customers. Illustrative cash revenue totals USD 82 million: USD 28 million of customer development payments, USD 42 million of accepted-product revenue and USD 12 million of platform, data and intellectual-property income. Direct and programme operating costs total USD 71 million, leaving USD 11 million before central overhead, financing, tax and terminal obligations.
Appendix B Minimum diligence file
The diligence file should include the terrestrial benchmark, process-science evidence, payload design, configuration record, safety approval, launch agreement, platform agreement, return licence, recovery plan, chain-of-custody procedure, quality protocol, test results, customer correspondence, signed contracts, acceptance terms, data rights, intellectual-property schedule, supplier agreements, insurance indications, programme budget, sources and uses, cash runway, downside plan and board milestone register. Every item should reconcile to one controlled technical configuration and valuation date.
Appendix C Red flag tests
Red flags include applying finished-product prices to an intermediate output; using gross payload mass as saleable yield; treating an orbital experiment as repeat production; omitting return and recovery from unit economics; using unsigned customer interest as contracted backlog; counting public grants as recurring revenue; assuming a return licence transfers between vehicles or sites; ignoring customer qualification time; treating technology readiness as manufacturing readiness; sizing debt against prospective option value; omitting reflight cost; and adding a technology premium on top of cash flows that already assume full technical success.
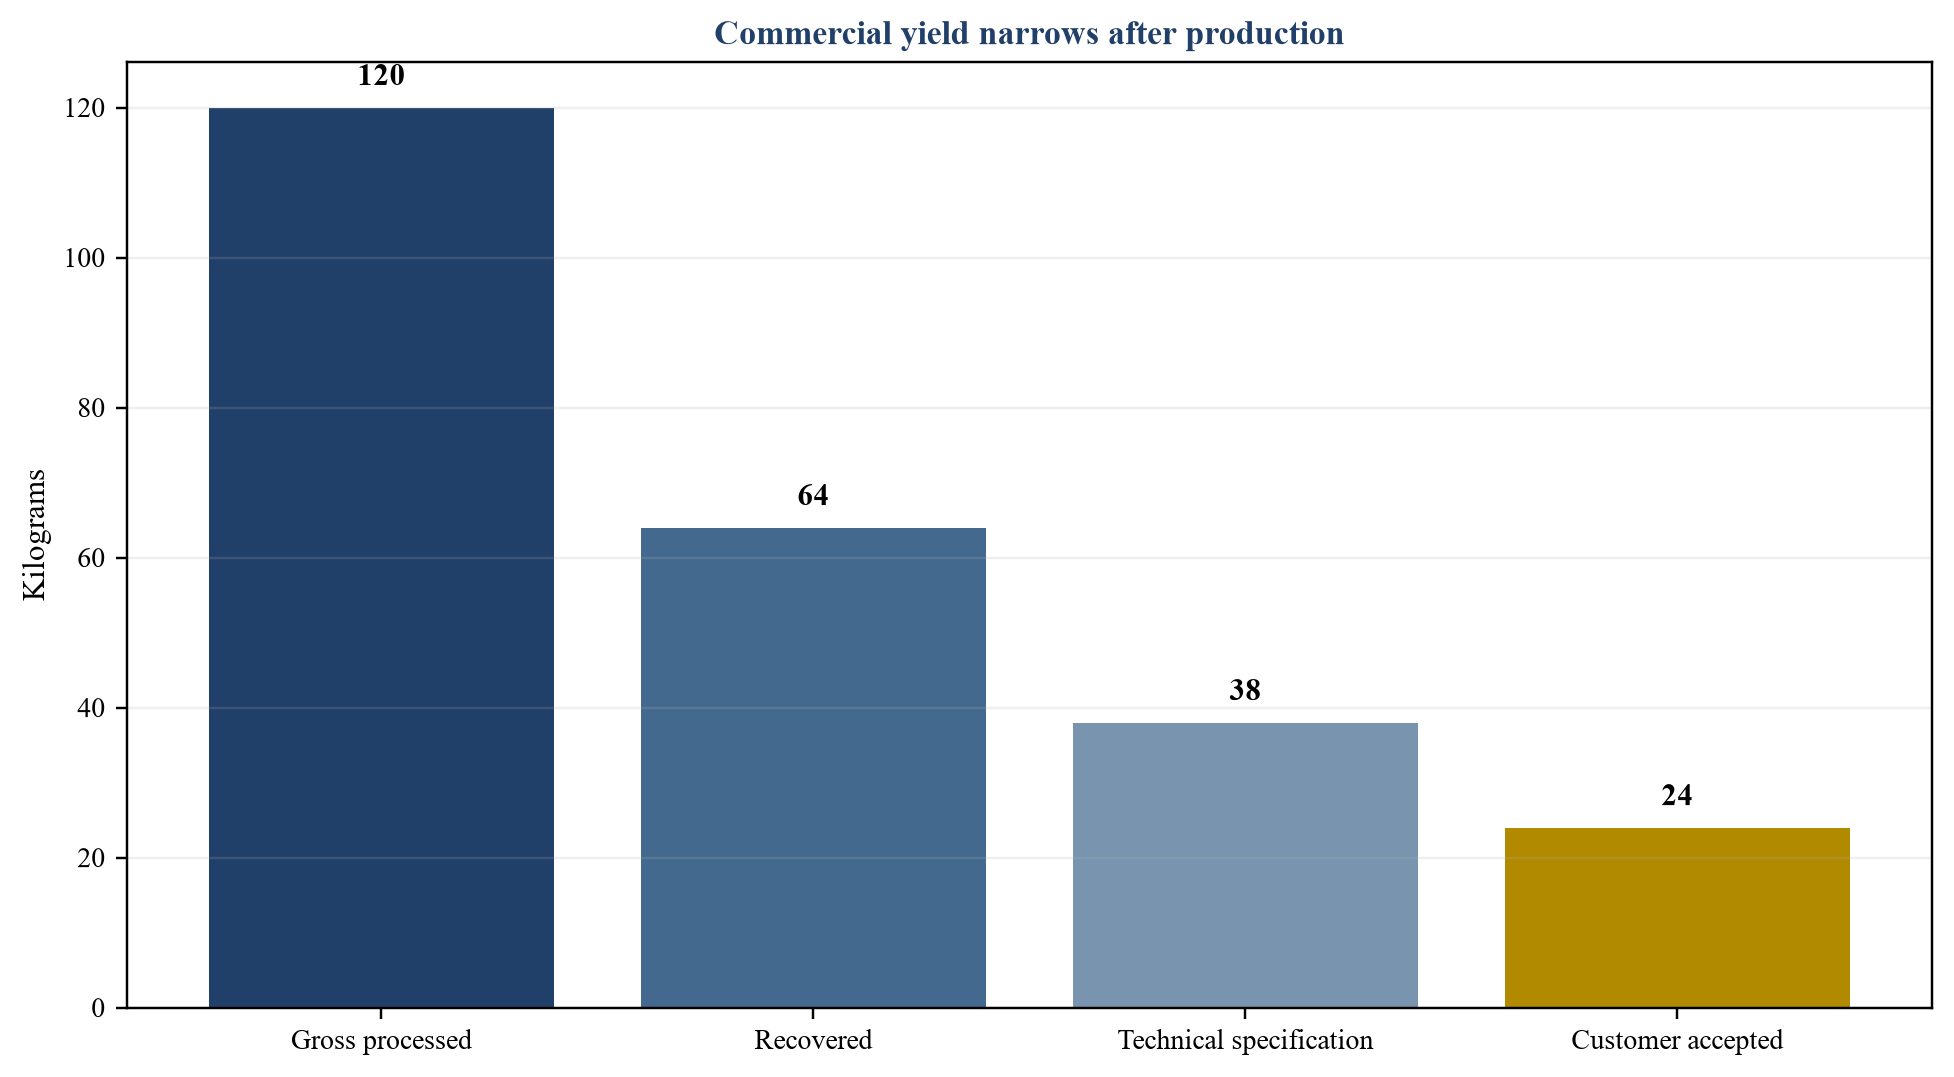
Hypothetical kilograms across a five-mission development programme.
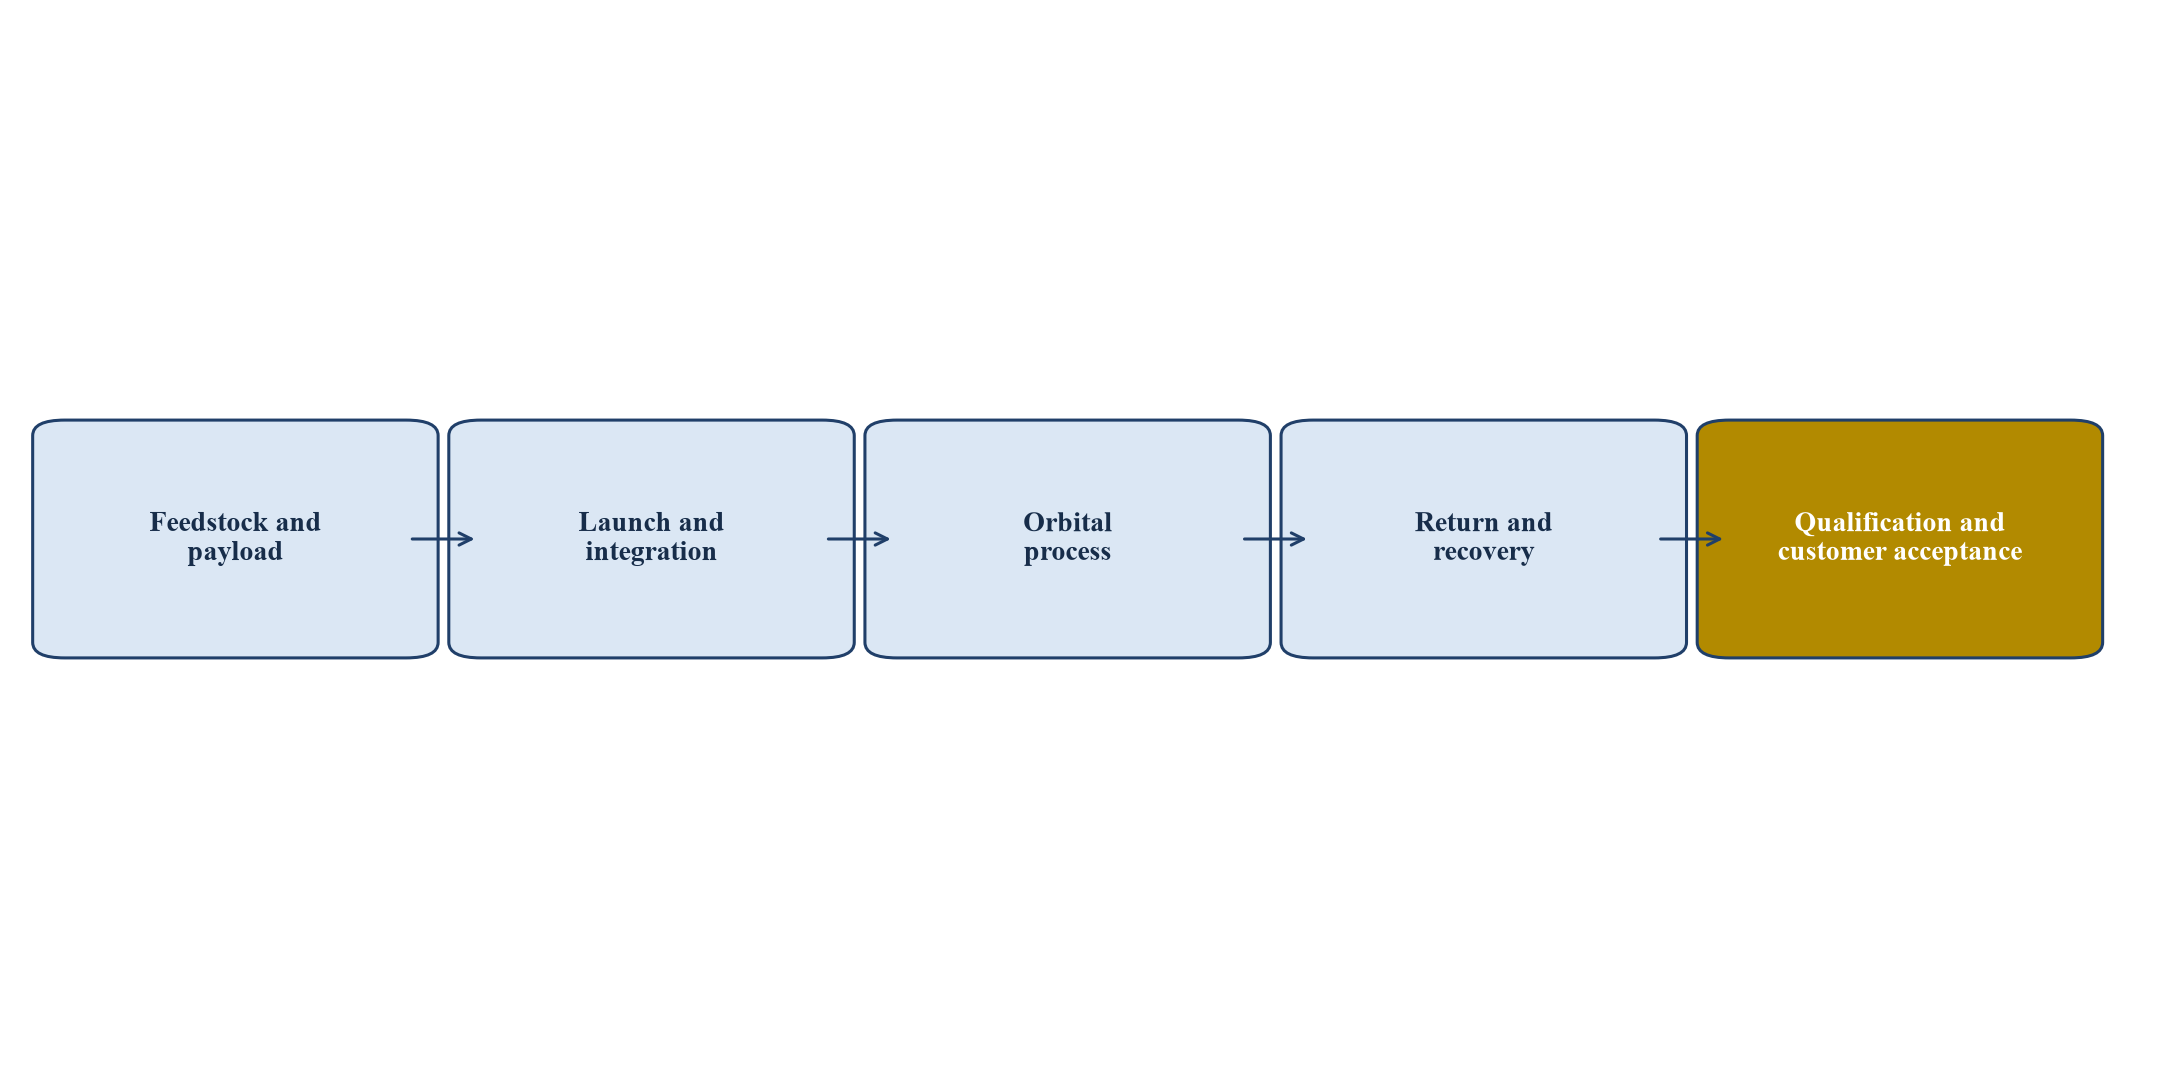
Proposed diligence architecture from feedstock to repeat purchase.
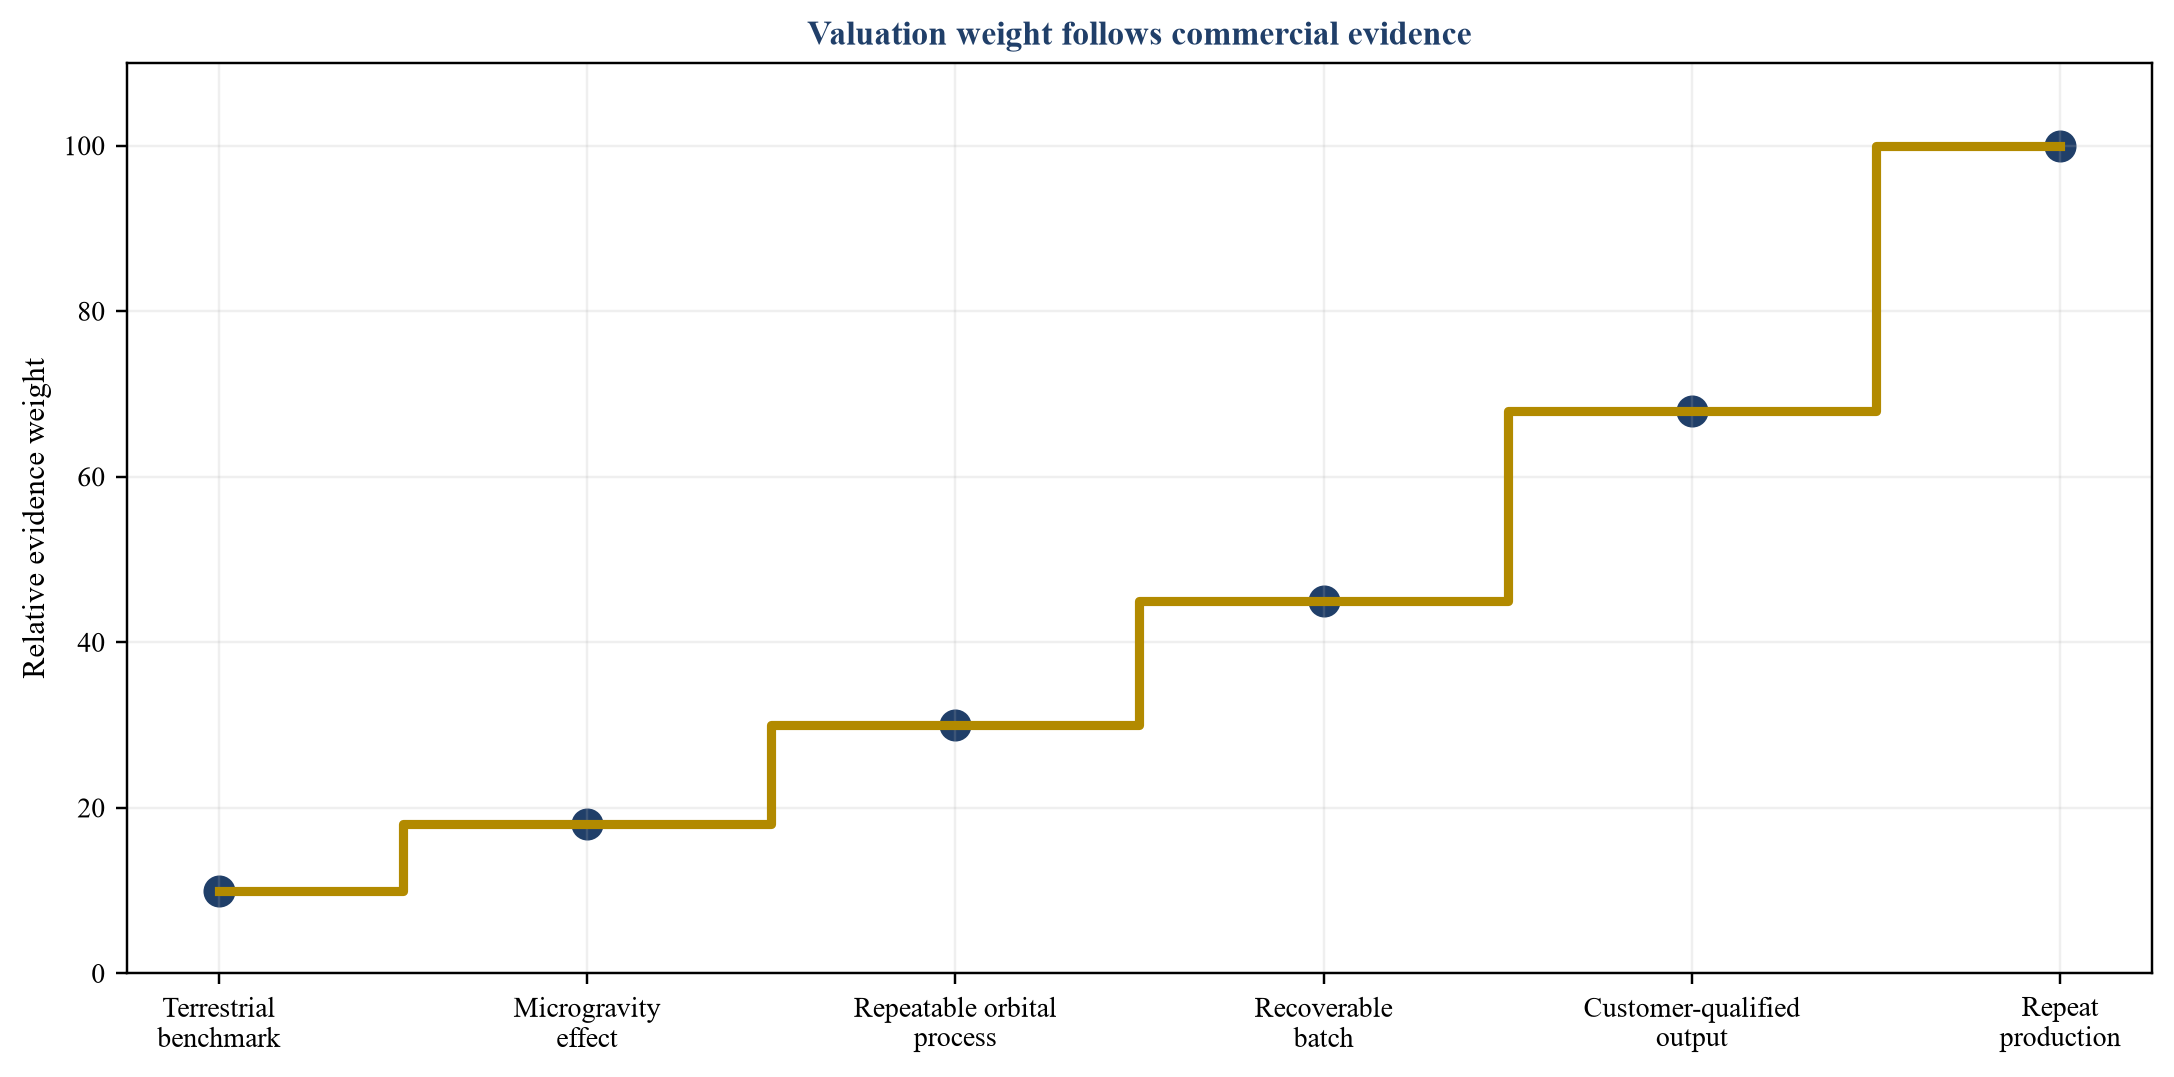
Proposed progression; each state requires controlled evidence.
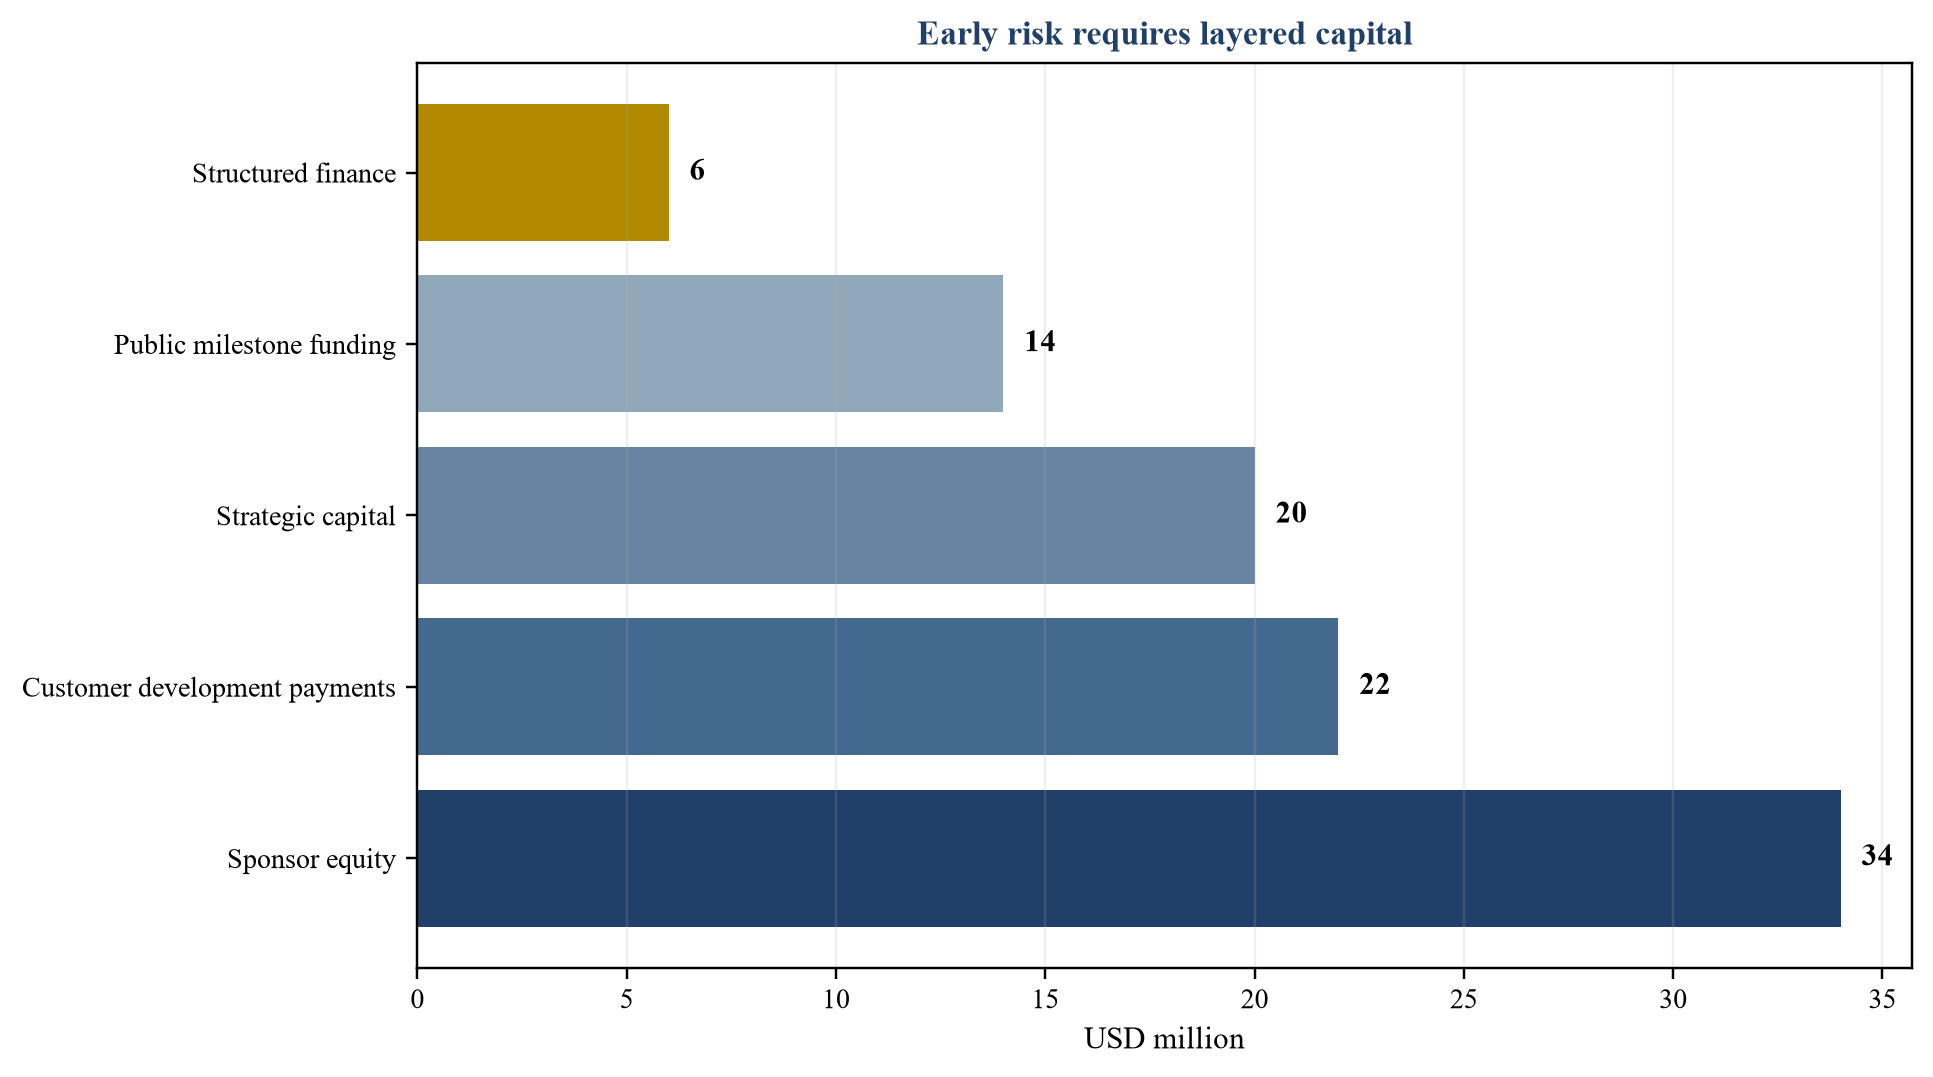
Illustrative USD millions; total programme uses USD 96 million.
Illustrative USD millions before central overhead financing tax and terminal obligations.
| State | Required evidence | Valuation treatment |
|---|---|---|
| Terrestrial benchmark | controlled comparison and customer problem | base research option |
| Microgravity effect | repeatable measured difference | technical probability increase |
| Orbital process | flight data and configuration record | mission execution option |
| Recoverable batch | successful return and chain of custody | end to end probability increase |
| Qualified output | independent testing and customer acceptance | commercial probability increase |
| Repeat production | repeat order and stable contribution | operating business valuation |
Proposed valuation states.
| Stage | Kilograms | Conversion from prior stage | Evidence |
|---|---|---|---|
| Gross processed | 120 | n.a. | mission batch record |
| Recovered | 64 | 53 percent | recovery and custody record |
| Technical specification | 38 | 59 percent | independent laboratory test |
| Customer accepted | 24 | 63 percent | contractual acceptance |
Illustrative kilograms across five missions.
| Cost category | Unit basis | Main uncertainty |
|---|---|---|
| Payload and process | mission and batch | redesign and qualification |
| Launch and integration | mission and kilogram | timing and shared launch terms |
| Orbital platform | time power crew and volume | utilisation and service pricing |
| Return and recovery | mission and landing | licence and recovery cadence |
| Testing and finishing | sample and accepted kilogram | destructive testing and yield |
| Insurance and reserves | mission and programme | exclusions and reflight obligation |
Proposed model structure.
| Instrument | Evidence | Cash treatment | Financing relevance |
|---|---|---|---|
| Paid study | scoped research work | revenue as performed | engagement evidence |
| Reservation | capacity and window | deposit or deferred revenue | limited until refund terms clear |
| Development agreement | milestones and rights | milestone revenue | supports funded work |
| Purchase commitment | accepted output and price | product revenue on acceptance | supports forecast after conditions |
| Repeat order | tested output and new commitment | recurring product revenue | strongest commercial evidence |
Proposed classification and financing relevance.
| Sources | USDm | Uses | USDm |
|---|---|---|---|
| Sponsor equity | 34 | Payload and process development | 18 |
| Customer development payments | 22 | Launch and integration | 24 |
| Strategic capital | 20 | Orbital platform services | 19 |
| Public milestone funding | 14 | Return and recovery | 14 |
| Structured finance | 6 | Testing insurance regulation and reserves | 21 |
Illustrative USD millions; total sources equal total uses.
| Scenario | Accepted output | Completed missions | Customer evidence | Valuation implication |
|---|---|---|---|---|
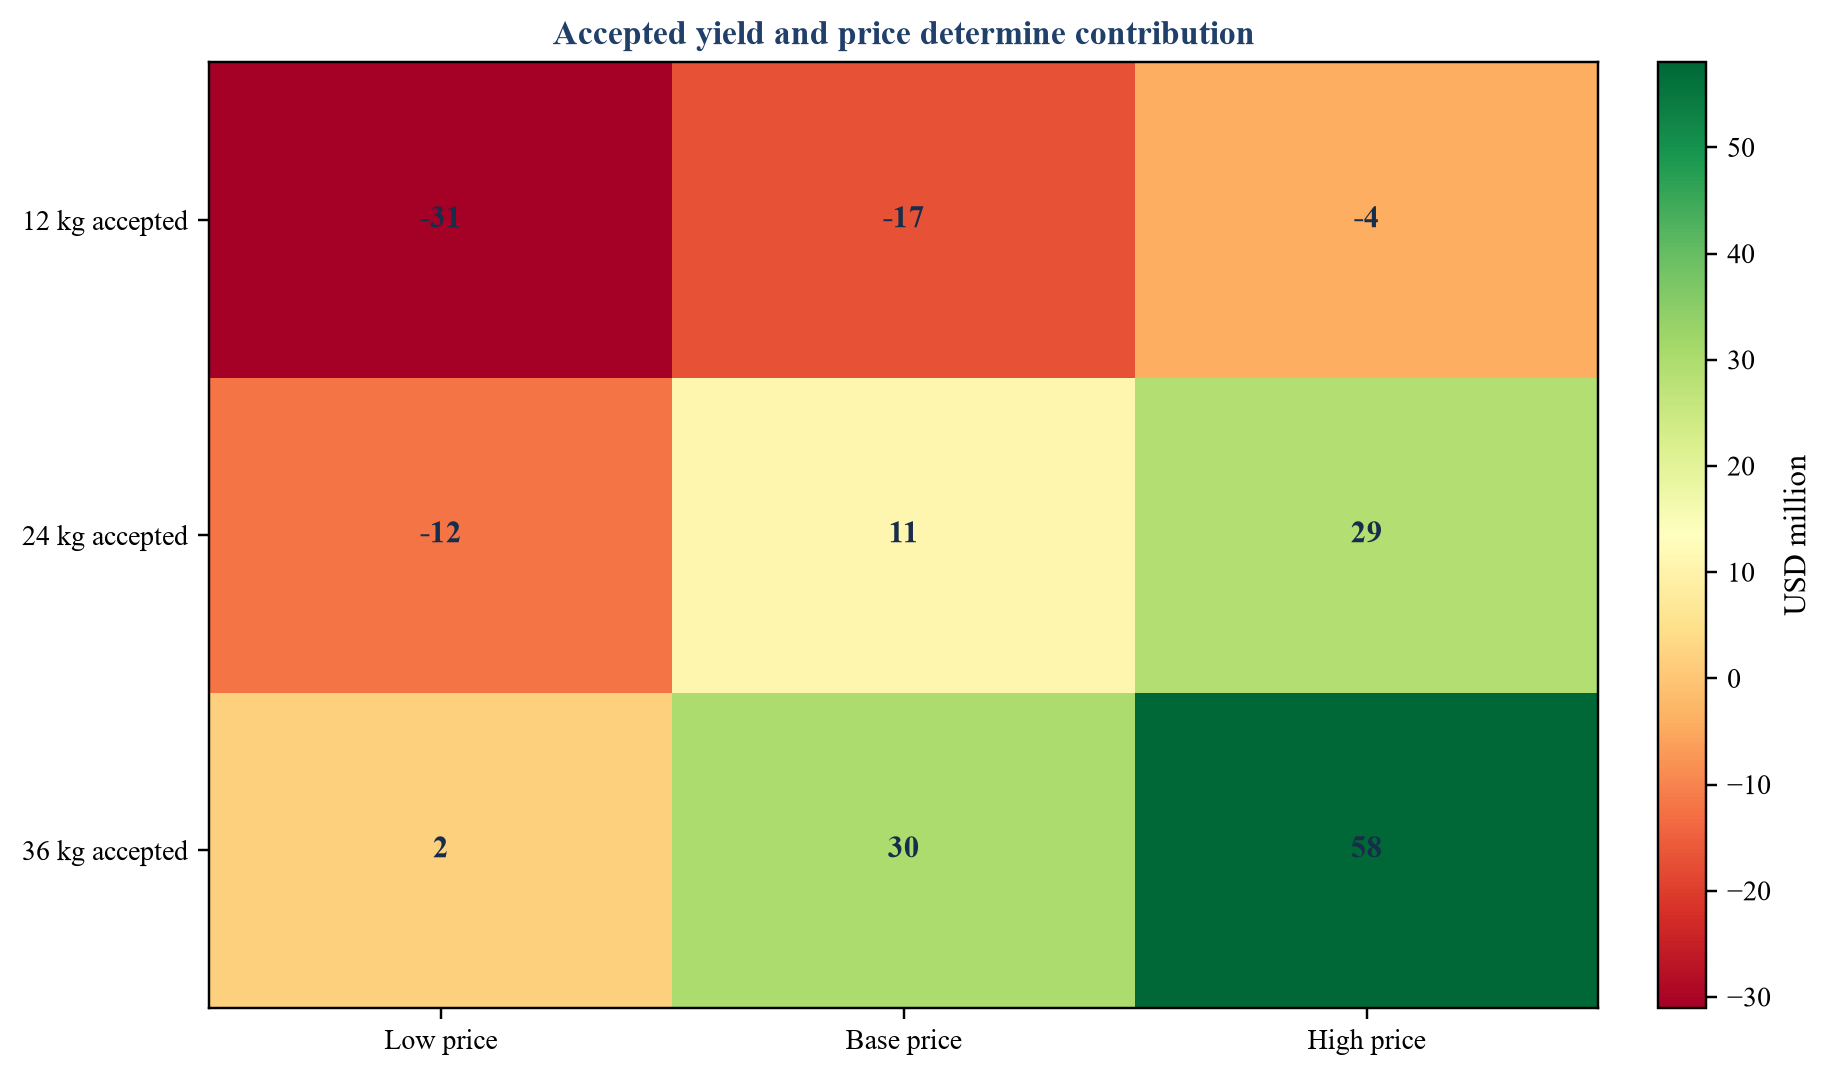
| Delay and low yield | 12 kg | 3 | paid studies only | continuing equity need |
| Base development | 24 kg | 5 | first acceptances | milestone valuation |
| Repeatable production | 36 kg | 6 | repeat orders | operating cash flow plus options |
Hypothetical outcomes; programme-specific evidence is required.
| Gate | Decision question | Minimum evidence |
|---|---|---|
| Product | what exact output is sold | specification and rights map |
| Effect | does orbit create a measured advantage | controlled comparative result |
| Yield | how much output reaches acceptance | end to end yield waterfall |
| Return | can product return on schedule | licensed vehicle and recovery plan |
| Customer | who pays and under what conditions | signed contract and acceptance protocol |
| Finance | is the next milestone fully funded | sources uses delay case and reserves |
| Scale | can contribution repeat at cadence | completed cycles and repeat order |
Proposed minimum approval record.
Sources
- NASA, In Space Production Applications. Read the primary source
- NASA, Applications Within Reach, 1 October 2023. Read the primary source
- NASA, Optical Fiber Production, 25 March 2024. Read the primary source
- NASA, In Space Production Applications Overview, October 2023. Read the primary source
- Federal Aviation Administration, Getting Started with Licensing. Read the primary source
- Federal Aviation Administration, Varda Licence VOL 24-130. Read the primary source
- European Space Agency, Space Rider Programme. Read the primary source
- NASA, Low Earth Orbit Microgravity Strategy, 16 December 2024. Read the primary source
- Federal Aviation Administration, Varda Reentry Environmental Assessment. Read the primary source
- NASA, In Space Production Applications Best Practices. Read the primary source
- Redwire Corporation, 2025 Annual Report. Read the primary source
- Varda Space Industries, W-4 Mission. Read the primary source
- UK Space Agency, National Microgravity Research Centre opens in Swansea, 6 March 2026. Read the primary source
- UK Space Agency, New studies for manufacturing advanced materials in orbit, 9 February 2026. Read the primary source
- UK Space Agency, Made in Space funding boosts breakthrough space technologies, 10 June 2026. Read the primary source
- NASA, Commercial Low Earth Orbit Economy. Read the primary source
- NASA, International Space Station Transition Plan Frequently Asked Questions. Read the primary source
- NASA, Commercial Space Frequently Asked Questions. Read the primary source
- NASA, In Space Production Applications Overview, May 2022. Read the primary source
- NASA, In Space Production Applications materials mini book, June 2025. Read the primary source
- NASA, Ames Partnerships Office Annual Report 2025. Read the primary source
- NASA, Advanced Manufacturing Technologies. Read the primary source
- NASA, Biomanufacturing in Space of Drug Delivery Medical Devices, 30 March 2026. Read the primary source
- NASA, In Space Liver Tissue Manufacturing Demonstration. Read the primary source
- NASA, Space Station Technology Demonstration. Read the primary source
- NASA, Commercial Low Earth Orbit Destinations procurement. Read the primary source
- UK Space Agency, Annual Report and Accounts 2025 to 2026. Read the primary source
- UK Government, Space Industrial Plan. Read the primary source
- UK Space Agency, UK space sector factsheet August 2025. Read the primary source
- Redwire Corporation, 2024 Annual Report. Read the primary source
